Form ADT-1 Online for Auditor Appointment
File Form ADT-1 accurately and on time with RegisterKaro. Get expert support to notify the ROC about auditor appointments as per MCA rules, fast, compliant, and stress-free.
 ADT-1 Preparation and Filing SupportMCA and ROC Filing AssistanceAuditor Appointment Documentation SupportFiling Status and SRN SupportTrusted by 2 Lakh+ Businesses


 What Sets Us ApartWhat Sets Us Apart
What is Form ADT-1?
ADT-1 does not have a separate acronym expansion; "ADT" is the MCA's auditor-related e-form series, and ADT-1 is specifically the intimation of an auditor's appointment to the ROC.
Form ADT-1 is an MCA form used by a company to notify the Registrar of Companies (ROC) about the appointment of its auditor. It records important details about the company, the auditor, the appointment, and the auditor's period of appointment.
Form ADT-1 is prescribed under Section 139 of the Companies Act, 2013, and Rule 4(2) of the Companies (Audit and Auditors) Rules, 2014. For appointments where ADT-1 filing is applicable, the form is generally filed with the ROC within 15 days of the meeting in which the auditor is appointed.
The revised Form ADT-1, effective from 14 July 2025, includes options for different types of auditor appointments. These include appointment or reappointment at an AGM, appointment in a casual vacancy, and first-auditor appointments.
Following the Ministry of Corporate Affairs (MCA) notification G.S.R. 359(E) dated May 30, 2025, effective July 14, 2025, the revised Form ADT-1 introduced a specific category for the appointment of a company's first auditor. While Section 139(6) does not expressly mandate ADT-1 for a Board-appointed first auditor, the revised form (from 14 July 2025) includes a first-auditor category, and the MCA V3 portal now effectively requires it. Filing is strongly recommended; non-filing can block later filings such as AOC-4. This differs from the earlier ADT-1 framework, which did not specifically include the first auditor appointment category.
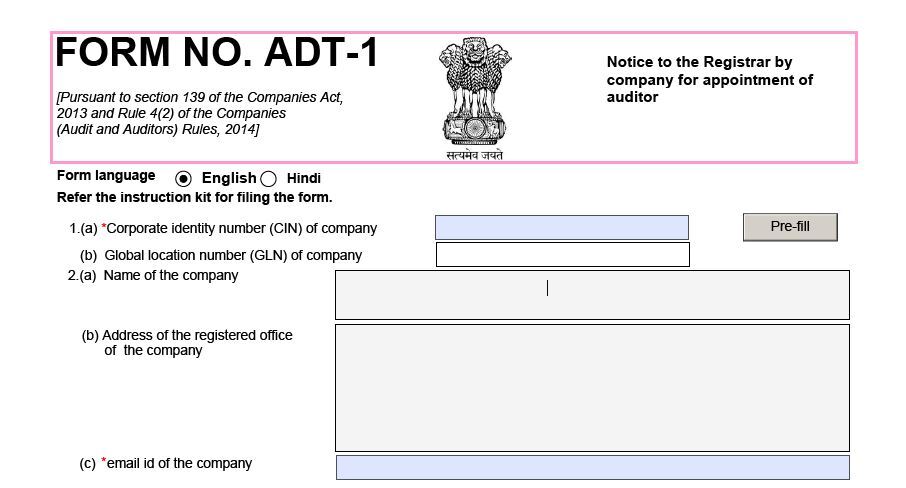
Details of the Auditor to be Submitted in Form ADT-1
When filing the form, you must provide specific details about the auditor, each with a clear purpose:
- Category of Auditor: Individual or Firm.
- Income Tax PAN: A unique identifier for the auditing entity.
- Membership/Firm Registration Number: To verify the auditor's credentials with the Institute of Chartered Accountants of India (ICAI).
- Address and Email ID: For official communication.
- Period of Appointment: Specifies the exact financial years the audit engagement covers. This is critical for tracking the auditor's term.
- Date of Appointment Resolution: The date of the Board Meeting or Annual General Meeting (AGM) where the appointment was approved, which sets the clock for the filing deadline.
Appointing the First Auditor and Filing Form ADT-1
The appointment of the first auditor and filing Form ADT-1 are two separate steps. Under Section 139(6) of the Companies Act, 2013, the Board generally appoints the first auditor within 30 days of registration. If the Board fails to do so, the members appoint the auditor within the prescribed period. The company must obtain the auditor's consent and eligibility certificate before the appointment.
Form ADT-1 serves as an intimation to the ROC about the auditor's appointment. For first auditor appointments, the revised ADT-1 includes a specific filing category, while the detailed filing requirement should be considered separately based on the applicable MCA provisions.
Is Form ADT-1 Required for the First Auditor?
Filing Form ADT-1 for the first auditor is not mandatory under the applicable provisions. However, the revised form includes a specific category for first auditor appointments, and filing it is preferred to formally intimate the ROC and keep the company's auditor records updated.
Appointing Subsequent Auditors and Reappointing Existing Auditors: ADT-1
Once the first auditor's term ends at the conclusion of the first AGM, subsequent auditors are appointed by the company's shareholders at the AGM. The shareholders may appoint a new auditor or reappoint the existing auditor, subject to the applicable provisions of the Companies Act, 2013.
The key requirements for subsequent auditor appointments include the following:
- Appointment for a Five-Year Term: An auditor appointed at an AGM generally holds office from the conclusion of that meeting until the conclusion of the sixth AGM, subject to applicable provisions, including auditor rotation.
- Rotation of Auditors: Auditor rotation applies to certain classes of companies, including:
- All listed companies.
- Unlisted public companies with paid-up share capital of ₹10 crore or more.
- Private companies with paid-up share capital of ₹50 crore or more.
- Companies with public borrowings from financial institutions or public deposits of ₹50 crore or more.
- Tenure Limits and Cooling-Off Period: Companies subject to rotation requirements cannot appoint an individual auditor for more than one term of five consecutive years or an audit firm for more than two consecutive terms of five years each. A five-year cooling-off period applies before the same auditor can be reappointed. One Person Companies and small companies are exempt from these rotation requirements.
- Timeline for Filing: Where ADT-1 filing is applicable, the form is generally filed with the ROC within 15 days of the AGM at which the auditor is appointed or reappointed.
Why Timely ADT-1 Filing Matters?
Filing Form ADT-1 helps a company meet its applicable ROC filing requirements and keep its auditor appointment details updated with the MCA. It also helps maintain accurate corporate records and avoid additional filing fees that may apply to delayed filings.
- Avoids Penalties: Timely filing is the simplest way to prevent heavy financial penalties.
- Official Intimation: It formally notifies the ROC about the auditor's appointment, including their identity and term.
- Ensures Legal Compliance: It keeps the company compliant, maintaining its active status and good legal standing.
- Promotes Transparency: It ensures the auditor's details are on public record, promoting accountability.
- Good Governance: The form strengthens corporate governance by ensuring the auditor appointment process is properly documented and transparent.
Who Needs to File ADT-1 in Indian Companies?
Form ADT-1 is filed by companies, other than Limited Liability Partnerships, to officially inform the MCA about the appointment of an auditor. The following categories of companies may need to file Form ADT-1:
- Private Limited Companies
- Public Limited Companies
- One Person Companies (OPCs)
- Small Companies
- Dormant Companies
- Listed and Unlisted Companies
Note: LLPs are governed by a separate law (LLP Act, 2008) and are not required to file Form ADT-1.
- Auditor Appointment or Reappointment at the AGM: The most common scenario for filing ADT-1 arises when shareholders, during their Annual General Meeting, approve the appointment of a new auditor or the re-appointment of an existing auditor.
- First Auditor Appointment: Form ADT-1 may also be filed to intimate the ROC about the appointment of the first auditor. Following the Companies (Audit and Auditors) Amendment Rules, 2025, the revised form includes the first auditor's appointment as a filing category.
- Filling of Casual Vacancies: When an auditor's position becomes vacant mid-term (e.g., due to resignation), and a new auditor is appointed, the company is required to file Form ADT-1 to inform the ROC.
Documents Required for Form ADT-1 Filing
To complete the ADT-1 filing, you will need the following key documents, attached to the e-form:
- Consent Letter from the Auditor: A written letter issued by the auditor clearly stating their willingness to accept the role of statutory auditor for the company.
- Eligibility Certificate under Section 141: The proposed auditor must provide a certificate confirming their eligibility as per Section 141 of the Companies Act, 2013. This certificate should declare that:
-
- The auditor is not disqualified under the law,
- The number of company audits does not exceed the statutory limit prescribed under Section 141(3)(g), and
- There are no disciplinary or legal proceedings pending against them.
- Certified Copy of the Board or AGM Resolution: A copy of the resolution passed in the Board meeting or Annual General Meeting (AGM), approving the appointment of the auditor. This document should be signed and certified by an authorized officer or director of the company.
- Formal Appointment Letter (Optional but Recommended): A formal appointment letter is not mandatory for ADT-1 filing. However, it can document key terms of the auditor's engagement, such as the appointment period and remuneration.
- Digital Signatures (Mandatory for Filing):
-
- The e-form must be digitally signed by a Director or Manager of the company.
- Additionally, the form must be certified by a practicing Chartered Accountant (CA), Company Secretary (CS), or Cost Accountant (CMA) using their Digital Signature Certificate (DSC).
Step-by-Step Process for ADT-1 Form Filing
The ADT-1 filing procedure is conducted online through the MCA V3 portal:
- Convene a Meeting: Hold a Board Meeting or AGM to pass the auditor appointment resolution.
- Obtain Auditor Documents: Secure the signed consent letter and eligibility certificate from the auditor.
- Download Form ADT-1: Access the latest version of the e-form from the MCA portal.
- Fill the Form: Accurately enter all details, including the Company's Corporate Identification Number (CIN), auditor's details, and appointment tenure.
- Attach Documents: Attach scanned copies of the required documents (Resolution, Consent, etc.)
- Digital Signature & Certification: The form must be digitally signed by a Director and certified by a practicing professional (CA, CS, or CMA) where applicable.
- File and Pay Fees: Upload the form to the MCA portal and pay the statutory fees for filing ADT-1.
- Receive Acknowledgment: An SRN (Service Request Number) is generated upon successful submission, which serves as proof of filing.
For the full auditor-appointment process, eligibility, and rotation rules, see our detailed guide on Auditor Appointment.
Fees Charged for Form ADT-1 Filing
The government filing fee for Form ADT-1 starts at ₹200 and can go up to ₹600, depending on the company's nominal share capital. The applicable government filing fee is based on the company's nominal share capital, as shown below:
| Nominal Share Capital | Government Filing Fee (INR) |
| Less than ₹1,00,000 | ₹200 |
| ₹1,00,000 to ₹4,99,999 | ₹300 |
| ₹5,00,000 to ₹24,99,999 | ₹400 |
| ₹25,00,000 to ₹99,99,999 | ₹500 |
| ₹1,00,00,000 or more | ₹600 |
| Company not having share capital | ₹200 |
If Form ADT-1 is filed after the prescribed due date, additional filing fees apply based on the period of delay. The additional fee can range from 2 times to 12 times the normal filing fee, depending on the delay period.
Timeline, Due Date & Validity of Form ADT-1
Form ADT-1 is generally filed within 15 days of the meeting in which the auditor's appointment is made or confirmed. The applicable due date depends on whether the appointment relates to the first auditor, a subsequent auditor, or another appointment covered by the form.
Due Date for Filing Form ADT-1
The deadline for filing Form ADT-1 depends on the type of auditor being appointed:
a) Appointment of First Auditor
- As per Section 139(6) of the Companies Act, 2013, the Board of Directors must appoint the first auditor within 30 days of the incorporation of the company.
- Filing Form ADT-1 for the first auditor is not mandatory. However, the revised form includes a specific category for this appointment, and filing it is preferred as an ROC intimation.
b) Appointment of Subsequent Auditor
- For auditors appointed or reappointed at the AGM, Form ADT-1 is generally filed as the prescribed ROC intimation.
- The form must be filed within 15 days from the date of the Annual General Meeting in which the auditor's appointment is confirmed.
Illustration: If the AGM is held on 25th September, the last date to file ADT-1 would be 10th October.
How Long Does Form ADT-1 Remain Relevant?
Form ADT-1 serves as an intimation to the ROC about the auditor's appointment. It remains relevant for the period covered by that appointment and until a subsequent appointment or change in the auditor's details is reported, as applicable.
a) First Auditor
The validity extends until the conclusion of the first Annual General Meeting.
b) Subsequent Auditor
As per Section 139(1) of the Companies Act, 2013, an auditor appointed at an AGM generally holds office until the conclusion of the sixth AGM (a five-year term). Section 139(2) separately prescribes auditor rotation for certain classes of companies. ADT-1 filed for such an appointment is valid for the entire approved term. There is no need to file Form ADT-1 every year during the auditor's term unless:
- There is a change in the auditor,
- The auditor resigns or is removed, or
- A new appointment is made after term completion.
Consequences of Not Filing Form ADT-1: Penalties and Other Risks
Filing Form ADT-1 is a legal requirement under the Companies Act, 2013. If a company does not file it by the due date, it can face penalties and other issues that may affect its operations and reputation.
1. Statutory Violations
Not filing ADT-1 on time goes against the law (Section 139 of the Companies Act). This can lead to legal action under Section 147.
2. Fees for Late Filing
The penalty for late filing of ADT-1 is severe and escalates with the delay. The law prescribes a flat penalty on the company and its officers, and the MCA imposes additional late filing fees on the form itself. The additional fee structure is as follows:
| Period of Delay | Additional Normal Filing Fee Payable |
| Up to 30 days | 2 times |
| More than 30 and up to 60 days | 4 times |
| More than 60 and up to 90 days | 6 times |
| More than 90 and up to 180 days | 10 times |
| More than 180 days | 12 times |
Example: If a company with ₹10 lakh authorised capital delays the filing by 100 days, the base fee is ₹400. Since the delay is over 90 days but under 180, the payable fee becomes ₹400 × 10 = ₹4,000.
3. Statutory Penalty Under Section 147
Beyond the late filing fee above, non-compliance may attract consequences under Section 147 of the Companies Act, 2013. The applicable consequence depends on the nature of the default.
- The company can be fined between ₹25,000 and ₹5,00,000.
- Every officer in default can be fined between ₹10,000 and ₹1,00,000.
The late filing fee is an additional amount paid to the MCA based on the length of the delay, while a statutory penalty is a separate consequence for a specific legal default.
4. Non-Compliant Tag on MCA Portal
The company may be marked as "non-compliant" on the Ministry of Corporate Affairs (MCA) website. This status is visible to the public and can cause problems like:
- Difficulty getting bank loans or credit,
- Trouble bidding for government tenders,
- A bad impression during audits or investor checks.
5. Issues in Future Filings and Increased Scrutiny
If ADT-1 is not filed, the auditor's details may not be updated in MCA records. This can cause issues when filing other forms, such as financial statements or annual returns. Repeated delays or non-compliance may also result in ROC notices, inspections, or further scrutiny of the company's activities.
Laws Governing the ADT-1 Form
The legal framework for auditor appointments and the filing of Form ADT-1 is primarily governed by:
- Section 139 of the Companies Act, 2013: This section covers the rules for the appointment of the first auditor, subsequent auditors, auditor rotation, and the filling of casual vacancies.
- The Companies (Audit and Auditors) Rules, 2014: These rules prescribe the procedures for auditor appointments and the filing of Form ADT-1 as the applicable ROC intimation.
- The Companies (Audit and Auditors) Amendment Rules, 2025: Notified via G.S.R. 359(E) on May 30, 2025, and effective from July 14, 2025, this amendment substituted the ADT-1 form and, most notably, substituted the ADT-1 form and added a specific category for first auditor appointments.
Connect with RegisterKaro and let our experts handle the legal hassle while you grow your business.
Frequently Asked Questions (FAQs)
When is ADT-1 to be filed?
Where ADT-1 filing is applicable, it is generally filed within 15 days from the date of the auditor's appointment or the relevant meeting. Missing the deadline may result in additional fees and penalties as per MCA norms.
How to check whether ADT-1 is filed or not?
You can check the status of ADT-1 filing by searching the company's Master Data or using the "View Public Documents" service on the MCA website. You'll be able to see whether the appointment has been officially recorded.
Is ADT-1 required to be filed every year?
No, ADT-1 is not filed every year. It is submitted only when a new auditor is appointed or an existing one is reappointed after their term ends. However, it must be refiled if there is any change in the auditor during the term.
What if ADT-1 is not filed?
Non-filing of ADT-1 attracts penalties under Section 147 of the Companies Act. The company can be fined between ₹25,000 and ₹5,00,000, and officers in default can be penalised from ₹10,000 to ₹1,00,000, in addition to the escalating late filing fee on the form itself.
What is the fee for filing ADT-1?
The government filing fee for ADT-1 varies based on the company's nominal share capital, ranging from ₹200 to ₹600. Late filing also attracts additional fees based on the number of days delayed, from 2 times the normal fee up to 12 times for delays beyond 180 days.
What documents are required for the ADT-1 form filing?
Documents required for the Form ADT-1 are the auditor's consent letter, a certificate of eligibility, and a copy of the Board or AGM resolution for appointment. All attachments must be submitted in PDF format and digitally signed.
Is ADT-1 required for the appointment of the first auditor?
No, filing Form ADT-1 for the first auditor is not mandatory. However, the revised ADT-1 includes a specific category for first auditor appointments, and filing it is preferred to formally intimate the ROC about the appointment.
Is it mandatory to attach any documents along with the ADT-1 Form?
Yes, ADT-1 must be accompanied by key documents such as the auditor's consent, eligibility certificate, and appointment resolution. Without these, the form may be marked as defective or rejected.
Can a company file the ADT-1 Form after the due date?
Yes, companies can file ADT-1 after the due date, but they will be liable to pay additional fees as per MCA norms. Persistent delays may attract legal penalties and scrutiny from the ROC.
Can an auditor be reappointed through the ADT-1 Form?
Yes, the same ADT-1 form is used for both the appointment and reappointment of an auditor after completion of their term. Reappointment must also be approved at the AGM and filed within 15 days.
Can Form ADT-1 be revised?
Yes, Form ADT-1 can be revised if any incorrect details were submitted initially. The company is allowed to submit the form again with the correct particulars, as permitted under the Companies Act, 2013.
Can we file ADT-1 without filing ADT-3?
Yes, ADT-1 and ADT-3 are separate filings. ADT-3 is used only when an auditor resigns and is not a prerequisite for filing ADT-1. You can proceed with the ADT-1 filing if no resignation has occurred.

Reviewed by
Joel DsouzaJoel Dsouza is a Chartered Accountant (CA) and compliance expert with over 7 years of hands-on experience in company registration, tax structuring, GST, ROC filings, and MCA compliance. As a qualified member of the Institute of Chartered Accountants of India (ICAI) and Co-Founder at RegisterKaro, he has personally advised more than 1,000 startups and SMEs across India, helping founders navigate incorporation, regulatory frameworks, and financial planning from Day 1. With deep expertise across all three levels of Finance and Portfolio Management, Joel is committed to promoting financial literacy and simplifying India's startup ecosystem through clear, actionable guidance that entrepreneurs can act on immediately.
Why Choose RegisterKaro for ADT-1 Filing Service?
RegisterKaro provides practical support for preparing and filing Form ADT-1 with the MCA. Our service covers document review, form preparation, filing, and post-filing support.
- End-to-End Filing Support: Assistance with document review, Form ADT-1 preparation, and submission on the MCA portal.
- Compliance-Focused Assistance: Support from professionals familiar with auditor appointment and ROC filing requirements.
- Transparent Pricing: Clear service charges with no hidden costs.
- Filing Updates: Receive updates on your filing status and applicable compliance requirements.
- Trusted by Businesses Across India: Supporting startups, companies, and other businesses with their registration and compliance requirements.
What Our Clients Say
View All
Hariharan Murugesan
 Verified
Thank you so much for your help with incorporating my company. Vaidehi Gupta was helpful and handled the process efficiently. I really appreciate the... Read more

Aayush
Verified"The support I received for incorporation of my company was outstanding. The process was clearly explained, and the team was responsive and knowledgea... Read more

Joel Kennedy Kovuru
VerifiedRegistarkaro team is the best in all aspects. From my company incorporation to all the complainces, they are professionally handling all my company as... Read more

Manasa Prasanna Kuma...
VerifiedWe at INTELWEAVE PVT LIMITED sincerely appreciate the support of Anchal, Harshita, Saloni, and Aman at Registerkaro for assisting Intelweave in succes... Read more

Anand Vardhan
VerifiedRegisterkaro provided seamless assistance in incorporating my Section 8 company. Shubh, my SPOC, was exceptional in managing the entire process hassle... Read more

newton george
VerifiedHaving a wonderful experience with register karo special thanks to NEHA LAKRA who alleviated and drove us from time to time and made the process smoot... Read more

MSM V'RESH
VerifiedI had a good experience with RegisterKaro for my business compliance requirements. Their team was supportive and guided me through the registration pr... Read more

Srinivasa Kannappan
VerifiedThe experience depends on which team you are working with. As their client, I got to work with a team who was very proactive. Menka, the PoC from thei... Read more

Anil karwa
VerifiedHad a very smooth experience with RegisterKaro for our compliance and filing work. The team was supportive and professional throughout the process. Sp... Read more

Satish Dinavahi
VerifiedVansh has been my poc from Register karo to handle compliances for our company and he has been very responsive and responsible and following up and fi... Read more
Related Blogs
View All
Section 8 Company Directors: Appointment, Remuneration & Reports
How to Convert Section 8 Company to Public Limited Company
Trademark Class 10 in India: Surgical & Medical Instruments
How to Convert Proprietorship to Private Limited Company in India
Appointment of Auditor Under the Companies Act, 2013
Appointment of Auditor in LLP: Procedure & Rules 2026
GST ARN Number: What It Is, Format & How to Track It
How to Close an LLP With Pending Annual Compliance in India?
Companies Compliance Facilitation Scheme, 2026: 90% Relief on ROC Compliance
A Complete Step-by-Step Guide to Darpan Registration Certificate