

How to Convert an LLP to a Private Limited Company in India

LLPs can convert into Private Limited Companies to raise equity funding, offer Employee Stock Option Plans (ESOPs), and create more opportunities for business expansion. The LLP to Pvt Ltd Company conversion process takes around 30 to 45 days and follows Section 366 of the Companies Act, 2013, read with the Companies (Authorized to Register) Rules, 2014. It involves four main steps:
- The partners give their written consent and reserve a company name.
- The LLP publishes a notice in Form URC-2 in one English and one vernacular newspaper.
- After the 21-day objection period ends, the LLP files Form URC-1 with the SPICe+ incorporation forms.
- The Registrar issues a Certificate of Incorporation with a new CIN.
Once the conversion is complete, the Private Limited Company assumes the LLP’s assets, liabilities, contracts, and pending proceedings. This change in business structure can help the partners attract equity investors, offer Employee Stock Option Plans (ESOPs), and access the concessional corporate tax regime.
Key Takeaways
- An LLP converts into a Private Limited Company by registering as a company under Section 366 of the Companies Act, 2013, which the law treats as a fresh registration.
- Every partner must consent in writing, because even one dissenting partner can block the conversion.
- The LLP publishes Form URC-2 in two newspapers and waits 21 days for objections before filing Form URC-1 with the SPICe+ incorporation forms.
- The Registrar issues a new Certificate of Incorporation and CIN, usually within 30 to 45 days.
- On conversion, the company takes over the LLP’s assets, liabilities, contracts, and pending cases, and the LLP stands dissolved.
- The conversion is tax-neutral under Section 70(1)(zd) of the Income-tax Act, 2025, if the partners receive only shares and keep 50% of the voting power for five years.
- The converted Pvt Ltd company gets a new PAN and TAN through SPICe+ and needs a fresh GST registration if the LLP was GST-registered.
Why Convert Your LLP to a Private Limited Company?
An LLP works well for many businesses, but a Private Limited Company offers more flexibility when raising investment, rewarding employees, or planning long-term expansion.
Here’s how the two structures compare for different scenarios:
| Factor | LLP | Private Limited Company |
| Equity funding | Cannot issue shares to investors. | Can issue equity shares to angel investors and venture capitalists. |
| Fundraising options | Has fewer options for raising equity-based funds. | Can raise funds through equity shares, preference shares, debentures, and eligible convertible instruments such as CCPS and convertible notes. |
| Employee Stock Options (ESOPs) | Cannot offer share-based ESOPs because it has no share capital. | Can offer ESOPs to attract and retain employees. |
| Income tax | Generally pays 30% tax, plus applicable surcharge and cess. | May qualify for the 22% tax regime under Section 200 of the Income Tax Act, 2025, with an effective rate of 25.17%, or pay 25% under the applicable regular regime. |
| Foreign investment | FDI is subject to specific sectoral and eligibility conditions. | Can receive FDI in a wider range of sectors, subject to applicable investment rules. |
| Business credibility | May be less suitable when investors or large clients require a corporate structure. | Formal governance and reporting requirements can support investor confidence and larger business relationships. |
| Ownership changes | Adding or removing partners generally requires changes to the LLP agreement and applicable filings. | Shares can be transferred subject to the Companies Act, 2013, and the Articles of Association (AOA). |
| Business continuity | Continues as an LLP unless converted or dissolved. | A statutory conversion can transfer the LLP’s assets, liabilities, contracts, and pending legal proceedings to the company under the applicable provisions, including Sections 368 to 370 of the Companies Act, 2013. |
| Public listing | Cannot list shares on a stock exchange. | Can convert into a Public Limited Company and pursue a stock exchange listing if it meets the applicable requirements. |
Before deciding to convert, read our detailed guide on LLP vs Private Limited Company to compare ownership, taxation, and compliance requirements and understand which structure better suits your business goals.
Tax Implications of Converting an LLP into a Private Limited Company
Converting an LLP into a Private Limited Company may qualify for capital gains tax relief, meaning tax may not be charged on the transfer of business assets if all prescribed conditions are met. Section 70(1)(zd) of the Income Tax Act (formerly Section 47(xiii) of the Income Tax Act, 1961) provides this exemption for qualifying firm-to-company successions.
Under this exemption, transferring the LLP’s assets to the company does not attract capital gains tax if all the following conditions are met:
- All assets and liabilities of the LLP immediately before conversion become the assets and liabilities of the company.
- All partners become shareholders in the same proportion as their capital account balances on the date of conversion.
- The partners receive only shares in the company, with no cash, other consideration, or additional benefit.
- The former partners collectively retain at least 50% of the company’s voting power for five years from the date of conversion.
If any condition is breached within the 5 years, the exemption is withdrawn. The capital gain that was not taxed then becomes taxable in the company’s hands in the year of the breach.
Other Tax Effects of Converting an LLP into a Private Limited Company
Converting an LLP into a Private Limited Company affects more than the applied capital gains tax.
The table below outlines the key tax implications of conversion and the compliance requirements to consider in each area:
| Tax Area | Effect of Conversion | What to Watch |
| Business losses and depreciation | The company can carry forward the LLP’s accumulated losses and unabsorbed depreciation under Section 116(8) of the Income Tax Act, 2025 (formerly Section 72A(6)) | The same four conditions under Section 70(1)(zd) apply. If any is breached, the loss already set off becomes taxable as the company’s income in the year of the breach (Section 116(9)). |
| Asset revaluation | Revaluing assets before conversion inflates the partners’ capital accounts | It can count as consideration beyond shares and put the exemption at risk |
| GST | The LLP’s GSTIN cannot be transferred, so the company needs a fresh registration within 30 days | Unused input tax credit moves to the company through Form GST ITC-02 |
| Stamp duty | The LLP’s property vests in the company under Section 368 of the Companies Act, 2013 | State law decides whether duty is payable on immovable property |
Legal Obligations for Converting an LLP to a Private Limited Company
The LLP Act, 2008 doesn’t provide a direct route for an LLP to become a company. Instead, the Companies Act, 2013 allows an existing LLP to register as a company, and separate provisions govern what happens to its property, liabilities, and pending cases afterward.
However, the process of converting a Private Limited Company into an LLP works differently. Under Section 56 and the Third Schedule of the LLP Act, 2008, a private limited company can convert directly into an LLP by filing Form 18 with the Registrar.
The key legal provisions for the conversion of an LLP to a Private Company are:
| Legal Provision | Purpose |
| Section 366 of the Companies Act, 2013 | Permits eligible entities, including LLPs, to register as companies under the Companies Act. |
| Section 374, Companies Act, 2013 | Requires secured creditors’ consent and a public notice before registration. An LLP registered as a company is deemed dissolved without further action. |
| Companies (Authorized to Register) Rules, 2014 | Prescribe the eligibility conditions, documents, public notice requirements, Forms URC-1 and URC-2, declarations, and the registration procedure. |
| Companies (Incorporation) Rules, 2014 | Govern the incorporation process through SPICe+, e-MOA, e-AOA, AGILE-PRO-S, INC-9, and other incorporation requirements. |
| Section 368, Companies Act, 2013 | Vests all the LLP’s movable and immovable property in the company. |
| Section 369, Companies Act, 2013 | Keeps the LLP’s debts, liabilities, obligations, and contracts in force against the company. |
| Section 370, Companies Act, 2013 | Allows pending suits and legal proceedings by or against the LLP to continue in the company’s name. |
| Section 70(1)(zd), Income-tax Act, 2025 | Exempts the transfer of the LLP’s assets from capital gains tax if the prescribed conditions are met (formerly Section 47(xiii) of the 1961 Act). |
Eligibility Criteria for Conversion of LLP to Private Limited Company Under Section 366
Not every LLP can convert into a Private Limited Company, as unresolved compliance issues or failure to meet Section 366 requirements may make it ineligible. Therefore, before initiating the conversion, ensure that your LLP meets the following eligibility requirements:
- Have at Least Two Partners: The LLP must have at least two partners on the date of application.
- Obtain Unanimous Consent from All Partners: All partners must provide their written consent to the conversion. Every partner must sign the notarized affidavit required under Section 374(c) and become a shareholder to keep the tax exemption. In practice, this means the conversion cannot proceed if even one partner refuses. The LLP should also pass a resolution approving the conversion.
- Complete Statutory Compliances: The LLP must have filed all its returns with the Registrar, including Form 8 (Statement of Account and Solvency) and Form 11 (Annual Return), up to the date of application.
- Obtain NOCs from Secured Creditors: Under Section 374(a), the LLP must get the consent or no objection of all secured creditors before registration. If it has no secured debt, it must submit a declaration to that effect.
- Have no insolvency or winding-up proceedings pending: An LLP under insolvency resolution or winding up cannot apply for conversion.
- Make every partner a shareholder: All existing partners must become shareholders of the new company. This is also one of the conditions for the tax exemption under Section 70(1)(zd).
- Meet the Minimum Company Requirements: As with any incorporation of a Private Limited Company, the proposed company must have:
- At least 2 shareholders
- At least 2 directors
- At least 1 resident director (a person who stayed in India for at least 182 days during the financial year)
Documents Required for Conversion of LLP to Private Limited Company
To convert an LLP into a Private Limited Company, you must submit the Unregistered Companies-1 (URC-1) form along with the SPICe+ incorporation forms and supporting documents to the ROC:
| Category | Documents and Forms |
| Partner approval | The partners’ resolution approving the conversion |
| List of partners | A list of partners as on a date not more than six clear days before the application, with the shares each will hold |
| Proposed directors | A list of proposed directors with their DIN, address, other interests and consent to act, verified by two or more proposed directors |
| LLP records | The LLP Agreement, the LLP’s Certificate of Incorporation, and proof of Form 8 and Form 11 filings |
| Financial statements | A statement of accounts certified by the auditor, prepared not more than 15 days before the application, plus the previous year’s audited financial statements and the latest ITR |
| Creditors and regulators | NOC from secured creditors and charge holders, where applicable, and sectoral regulator approvals where needed |
| Registered office and KYC | Registered office proof, and the PAN, Aadhaar (passport for foreign nationals) and Digital Signature Certificates of each director and subscriber |
| SPICe+ Part A | Reserve the proposed company name |
| Form URC-2 | A public notice in one English and one vernacular newspaper, inviting objections within 21 clear days. Attach copies of the advertisements and proof of service on the Registrar (LLP). |
| Form URC-1 | The application to register the LLP as a Private Limited Company under Section 366 |
| SPICe+ Part B, e-MOA (INC-33) and e-AOA (INC-34) | Company incorporation, allotment of CIN, and filing of Memorandum and Articles of Association |
| DIR-2 and INC-9 | Each proposed director’s consent to act, and the declaration by the subscribers and first directors |
| AGILE-PRO-S | Registers the company for EPFO, ESIC, and a bank account, plus GST and professional tax where applicable |
What is the Step-by-Step Procedure to Convert an LLP to a Private Limited Company?
You can convert an LLP to a Private Limited Company through a series of steps, starting with partner approval and director documentation.
Here’s how the procedure for converting an LLP to a Private Limited Company works:
Step 1: Obtain Approval from All Partners
Begin by obtaining the written consent of all partners. The LLP must pass a resolution approving the conversion and authorize one or more designated partners to sign and file the required forms.
Step 2: Obtain DSC and DIN for All Proposed Directors
Every proposed director and subscriber must obtain a Class 3 DSC to sign electronic forms on the MCA portal. Directors without a DIN can get one through SPICe+ during incorporation. The proposed company must have at least two directors, including one resident director.
If you do not have a DSC yet, check out our step-by-step guide to registering a DSC on the MCA V3 portal.
Step 3: Apply for Name Approval via SPICe+ Part A
Apply for name approval through SPICe+ Part A. In most cases, businesses retain the LLP’s existing name by replacing “LLP” with “Private Limited”, subject to the MCA’s name availability guidelines.
Note: Reserved names are valid for 20 days. Complete the incorporation and URC-1 filing before the reservation expires. You can also extend the reservation under Rule 9A before it expires to 40 days for ₹1,000, or to 60 days for ₹3,000 in one payment. Otherwise, the name will lapse, and you may need to reapply and pay the ₹1,000 fee again.
Step 4: Publish Newspaper Advertisement in Form URC-2
After reserving the name, publish Form URC-2 in an English newspaper and a vernacular newspaper circulating in the district of the LLP’s registered office. Also, send a copy of the notice to the Registrar. The notice invites objections within 21 clear days.
Step 5: File Form URC-1 with the Registrar of Companies
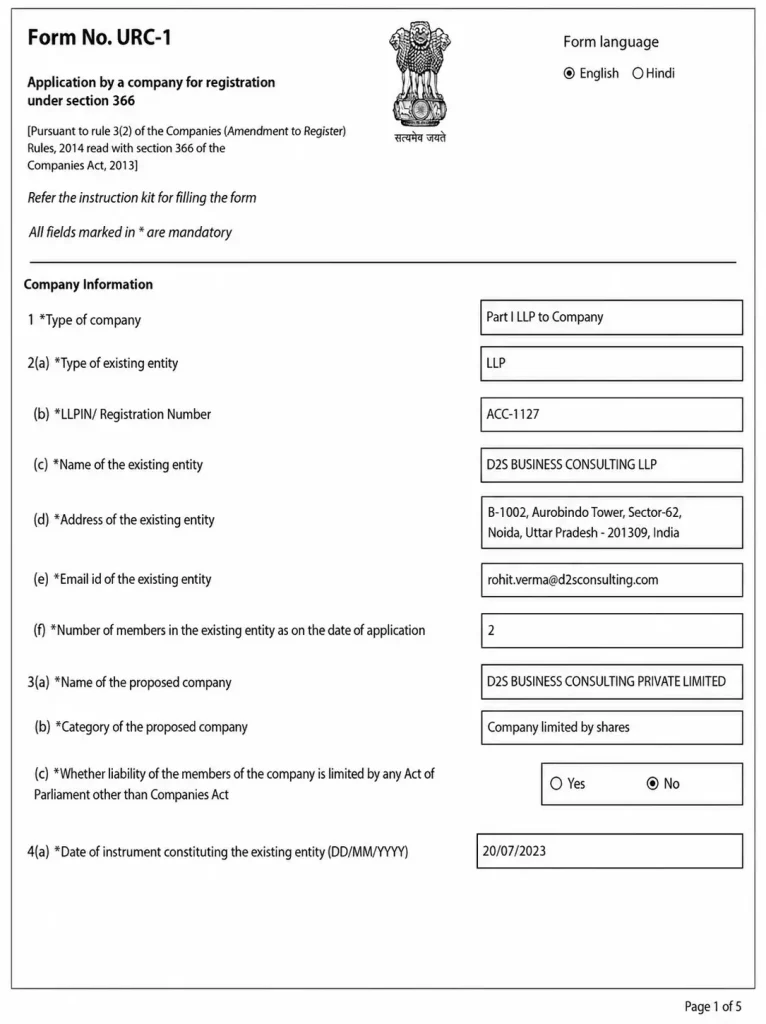
Once the objection period ends, file Form URC-1 along with SPICe+ (Part B), e-MOA (INC-33), e-AOA (INC-34), AGILE-PRO-S, INC-9, and DIR-2 with the Registrar of Companies. Attach all the prescribed documents, including:
- The partners’ consent and resolution
- Certified financial statements and the latest ITR of the LLP
- LLP Agreement
- List of partners with their proposed shareholding
- Creditor NOCs
- Form URC-2 advertisements, with proof of service on the Registrar
- Proof of statutory compliance
If someone raises an objection during the 21-day notice period, address it before the Registrar can proceed with the conversion. First, serve the URC-2 notice on the objecting party, usually a creditor, and try to resolve the concern by obtaining a NOC or settling the claim. Then submit the objection and your response to the Registrar for review. The ROC can proceed with the conversion once it is satisfied that the objection has been resolved.
Step 6: Certificate of Incorporation
Under Rule 4(3), the Registrar considers the application along with any objections received within 30 days of the advertisement. If the application meets the requirements of the Companies Act, 2013, and the Companies (Authorized to Register) Rules, 2014, the Registrar:
- Issues a Certificate of Incorporation with a new Corporate Identity Number (CIN).
- Records the LLP as dissolved from the date of registration.
- Registers the Private Limited Company, which takes over the LLP’s business, assets, liabilities, rights, and obligations.
LLP to Private Limited Company Conversion Timeline
The conversion of an LLP to a Private Company usually takes 30 to 45 days. The 21-day objection period is the longest fixed stage, so the other steps are planned around it:
| Stage | Typical Time | What Affects It |
| Partner consent and documents | 3 to 5 days | Collecting signatures, the certified statements, and creditor NOCs |
| DSC and DIN | 1 to 2 days | Video verification for each director and subscriber |
| URC-2 notice and objection period | 21 clear days from publication | Fixed by Rule 4(1). It can’t be shortened. |
| Name reservation (SPICe+ Part A) | 2 to 3 working days | Timed so the 20-day validity covers the URC-1 filing date |
| URC-1 and SPICe+ filing | 1 to 2 days after the objection period | Accuracy of attachments, and any objections received |
| Registrar’s review and COI | Within 30 days of the advertisement | Rule 4(3). Resubmission requests add time. |
| Total | 30 to 45 days | Assuming there are no objections or resubmissions |
The name reservation must be timed carefully because the approved name is valid for only 20 days, while the objection period lasts 21 days. Apply for name approval during the objection period so the name remains valid when you file Form URC-1.
Government Fees and Other Costs of Converting an LLP into a Pvt Ltd Company
The government and third-party costs of converting an LLP into a Private Limited Company start from about ₹19,500, plus state stamp duty. The final cost depends on the authorized capital, the number of directors, and the state of registration. Here’s a breakdown of the cost:
| Particulars | Estimated Cost | Paid To |
| Name Reservation | ₹1,000 | MCA |
| Government fee (Form URC-1), based on authorized capital | Starts at ₹200 for nominal share capital below ₹1 lakh, and rises by slab to ₹600 for capital of ₹1 crore or more | MCA |
| DSC (per director) | ₹2,500 | Licensed Certifying Authority |
| CA certification of the Statement of Assets and Liabilities | ₹5,000–₹15,000 | Chartered Accountant |
| MOA and AOA Drafting (if charged separately) | ₹3,000–₹8,000 | Professional Service Provider |
| Form URC-2 Newspaper Advertisement | ₹2,000–₹10,000 | Newspaper Publisher |
| Stamp Duty on MOA and AOA | Varies by state and authorized share capital | State Government |
Professional fees charged by our Company Secretary, Chartered Accountant, or other service provider for handling the conversion usually start from ₹1,499, plus 18% GST.
Several of these costs, such as the name reservation fee, DSCs, and stamp duty, are the same as for a new company. Our breakdown of Pvt Ltd registration fees covers them in detail, including state-wise stamp duty.
Compliance After LLP to Private Limited Company Conversion
After the LLP converts into a Private Limited Company, the company has one-time steps to complete, followed by its regular annual company compliance.
One-Time Steps After Conversion
- Hold the first board meeting within 30 days of incorporation.
- Appoint the first auditor within 30 days of incorporation.
- Issue share certificates to the former partners within 2 months of incorporation.
- Apply for a new PAN and TAN if SPICe+ did not allot them, because the LLP’s PAN cannot be carried forward.
- Obtain a fresh GST registration, cancel the LLP’s GSTIN, and transfer eligible ITC through Form GST ITC-02.
- Use the EPFO and ESIC numbers allotted through AGILE-PRO-S, and apply for a fresh Udyam registration.
- Update bank accounts and licenses such as IEC, FSSAI, and professional tax.
- Request a novation or fresh agreements from counterparties who ask for them, though Section 369 transfers contracts automatically.
- Display the company name, CIN, and registered office address at every place of business, and update invoices and letterheads.
- Pay the state stamp duty and update the property records if the LLP’s immovable property transfers to the company.
Ongoing Company Compliance
- Hold at least four board meetings a year, or two for a small company.
- Conduct the first AGM within 9 months of the end of the first financial year, then within 6 months of each year end.
- Get the accounts audited every year by a practicing Chartered Accountant.
- File AOC-4 within 30 days and MGT-7 or MGT-7A within 60 days of the AGM.
- Submit DIR-3 KYC once every three years.
- File ITR-6 by October 31 each year (extended to November 21, 2026 for AY 2026-27).
Common Mistakes to Avoid During LLP to Private Limited Company Conversion
Avoid these mistakes to prevent delays, rejection by the ROC, or the loss of tax benefits:
- Pending LLP Compliances: File all overdue Form 8, Form 11, and DIR-3 KYC (where applicable) before applying.
- Expired financial statements: Use an auditor-certified statement of accounts prepared not more than 15 days before the application, along with the previous year’s audited financial statements.
- Missing Partner Consent: Obtain the written consent of all partners. Even one missing signature can invalidate the application.
- Skipping Form URC-2: Publish Form URC-2 in one English and one vernacular newspaper and complete the 21-day objection period before filing Form URC-1.
- Mismatched personal details: Make sure names, addresses, and dates of birth match across PAN, Aadhaar, DSC, and passport records for every partner and director.
- Poor timeline planning: The name stays reserved for only 20 days, while the URC-2 objection period alone runs for 21 days. Plan the name reservation and newspaper notice together so the name doesn’t lapse before URC-1 is filed.
- Missing Creditor NOCs: Obtain NOCs from all secured creditors and required sectoral regulators before filing.
- Incorrect Share Allotment: Ensure partners receive shares in the same proportion as their capital accounts on the date of conversion to retain tax neutrality.
- Breaching the Five-Year Lock-in: Former partners must collectively retain at least 50% voting power for five years to preserve the capital gains tax exemption.
Conclusion
For an LLP planning to raise equity or expand its team, converting into a Private Limited Company can be a logical next step. However, a company has higher annual compliance requirements, and tax-neutral treatment requires partners to retain at least 50% voting power for five years after conversion.
With proper planning, the conversion process can proceed smoothly. RegisterKaro’s experts can handle your LLP to Private Limited Company conversion end to end, from obtaining partner consent and publishing the URC-2 notice to securing the Certificate of Incorporation. Sole proprietors can also move to a company structure through a separate process. Read our guide to learn more about how to convert a proprietorship into a Private Limited Company.
