GSTR-9 Annual Return Filing Online in India
Avoid penalties and last-minute stress with reliable GSTR-9 return filing. Stay compliant with GST laws and ensure your business meets all regulatory requirements before the due date.
 Expert-Led Filing Support & AcknowledgementAccurate Computation & ReconciliationGSTIN-Level Reporting & ValidationGSTR-9 / GSTR-9C Applicability AssessmentGSTR-1/3B Reconciliation & Late-Fee Advisory


 What Sets Us ApartWhat Sets Us Apart
What is GSTR-9?
GSTR-9 is an annual return that registered GST taxpayers must file every year for the relevant financial year, subject to applicable exemptions. It consolidates details of outward supplies, inward supplies, Input Tax Credit (ITC), tax paid, refunds, demands, and other required information.
The return primarily draws information from the taxpayer's periodic GST returns and accounting records. Taxpayers should reconcile these records before submitting GSTR-9 to ensure that the reported information is accurate and complete.
What Does GST-9 Contain?
GSTR-9 generally contains information relating to:
- Outward and inward supplies
- Taxable, exempt, and zero-rated supplies
- Input Tax Credit (ITC) availed and reversed
- Tax payable and tax paid
- Refunds and demands
- Previous financial year's transactions reported in the relevant period
- HSN-wise details, wherever applicable
- Late fees and other required information
The annual return therefore gives a consolidated view of GST reporting for the financial year.
Different GST Annual Return Forms
While GSTR-9 is the main annual return form under GST, there are a few related forms designed for different types of taxpayers and reporting needs. Each serves a specific purpose depending on the taxpayer’s registration type, turnover, and role in the GST system. Here’s a breakdown of the different forms:
- GSTR-9: This is the standard annual return form for regular taxpayers registered under GST. It includes consolidated details of outward and inward supplies, ITC, tax paid, and other related information for the full financial year.
- GSTR-9C: This is a reconciliation statement for taxpayers whose annual turnover exceeds ₹5 crores (applicable from FY 2020–21 onwards; earlier the limit was ₹2 crore).
It includes:
- A comparison between the data filed in GSTR-9 and the financial statements.
- The form must be self-certified by the taxpayer (audit by a CA or CMA was required earlier, but is now optional).
- Helps ensure transparency and accuracy in reporting.
Choosing the right form and understanding your GSTR-9 filing eligibility is essential to ensure error-free annual return filing under GST.
Note: In place of GSTR-9A, GSTR-4 is used for annual filing from FY 2019-20 onwards. This form is meant for taxpayers under the Composition Scheme, which allows small businesses to pay tax at a fixed rate.
Who Needs to File GSTR-9?
For FY 2024-25 onwards and ongoing in 2026-27, registered persons with aggregate turnover up to ₹2 crore are exempt from filing GSTR-9. Those with aggregate turnover above ₹2 crore generally need to file GSTR-9, unless a specific exemption applies.
The exemption for taxpayers with aggregate turnover up to ₹2 crore applies from FY 2024-25 onwards under Notification No. 15/2025-Central Tax dated September 17, 2025.
| Aggregate turnover | GSTR-9 requirement |
| Up to ₹2 crore | Exempt from GSTR-9 filing |
| Above ₹2 crore up to ₹5 crore | GSTR-9 generally required |
| Above ₹5 crore | GSTR-9 generally required; GSTR-9C also applicable |
The ₹5 crore threshold applies separately to GSTR-9C. Registered persons whose aggregate turnover exceeds ₹5 crore in the relevant financial year must furnish a self-certified GSTR-9C along with GSTR-9, subject to the applicable rules.
Who is Exempt From GSTR-9 Filing?
The GST law excludes certain categories from the annual return requirement, while separate notifications may provide additional exemptions based on turnover. The following categories generally fall outside the GSTR-9 requirement under Section 44:
- Input Service Distributors (ISDs)
- Persons liable to deduct tax under Section 51
- Persons liable to collect tax under Section 52
- Casual taxable persons
- Non-resident taxable persons
Composition taxpayers follow the annual return requirements applicable to the Composition Scheme rather than filing the regular GSTR-9. For taxpayers covered by the general composition scheme, the applicable turnover limit is ₹1.5 crore in the preceding financial year, subject to the conditions and provisions of the scheme. They generally file Form GSTR-4 as the annual return and Form CMP-08 as the quarterly statement for payment of self-assessed tax.
Taxpayers should check the rules applicable to their registration type and the relevant financial year before determining whether GSTR-9 filing is required.
GSTR-9 vs GSTR-9C vs GSTR-4: What is the Difference?
GSTR-9 is the annual GST return for applicable regular taxpayers, while GSTR-9C is a self-certified reconciliation statement required when the applicable turnover threshold is exceeded. Composition taxpayers follow the applicable annual return requirements through GSTR-4 rather than the regular GSTR-9 filing framework.
| Particulars | GSTR-9 | GSTR-9C | GSTR-4 |
| Purpose | Annual GST return | Reconciliation of GST data with financial records | Annual return for taxpayers under the Composition Scheme |
| General applicability | Above ₹2 crore, subject to applicable exemption | Aggregate turnover exceeding ₹5 crore | Composition taxpayers covered by the applicable scheme |
| Main information | Supplies, ITC, tax paid, refunds, demands, and other details | Reconciliation of turnover, tax liability, and other financial information | Summary of supplies, inward supplies, tax liability, and other applicable details |
| Certification | Filed by the taxpayer | Self-certified by the taxpayer | Filed by the taxpayer |
| Filing relationship | Annual return under Section 44 | Furnished along with GSTR-9 where applicable | Annual return applicable to Composition Scheme taxpayers |
For taxpayers to whom GSTR-9C applies, the annual return under Section 44 is complete only when both GSTR-9 and GSTR-9C have been furnished.
GSTR-4 is the annual return applicable to taxpayers who have opted for the Composition Scheme during the financial year, subject to the applicable rules and conditions.
Documents Required to File GSTR-9 in India
To correctly file GSTR-9 online, you will need these documents and information:
- GSTR-1 data: Details of all sales for the financial year.
- GSTR-3B data: Summary of GST taxes owed and ITC claimed for the financial year.
- Financial Statements: Profit & Loss Account and Balance Sheet, especially if you need to file GSTR-9C for reconciliation.
- Books of Accounts: Purchase and sales records, expense ledgers, and other accounting documents for cross-checking data.
- Reconciliation Statements: Documents showing any differences between your GSTR-1, GSTR-3B, and accounting books.
- ITC Register: Details of all input tax credits taken, reversed, or denied during the year.
- HSN-wise Summary: Details of outward supplies reported under HSN codes are required in Table 17 of GSTR-9, subject to the applicable reporting requirements. Table 18, which covers inward supplies, has separate reporting provisions and has been optional for eligible taxpayers in applicable periods.
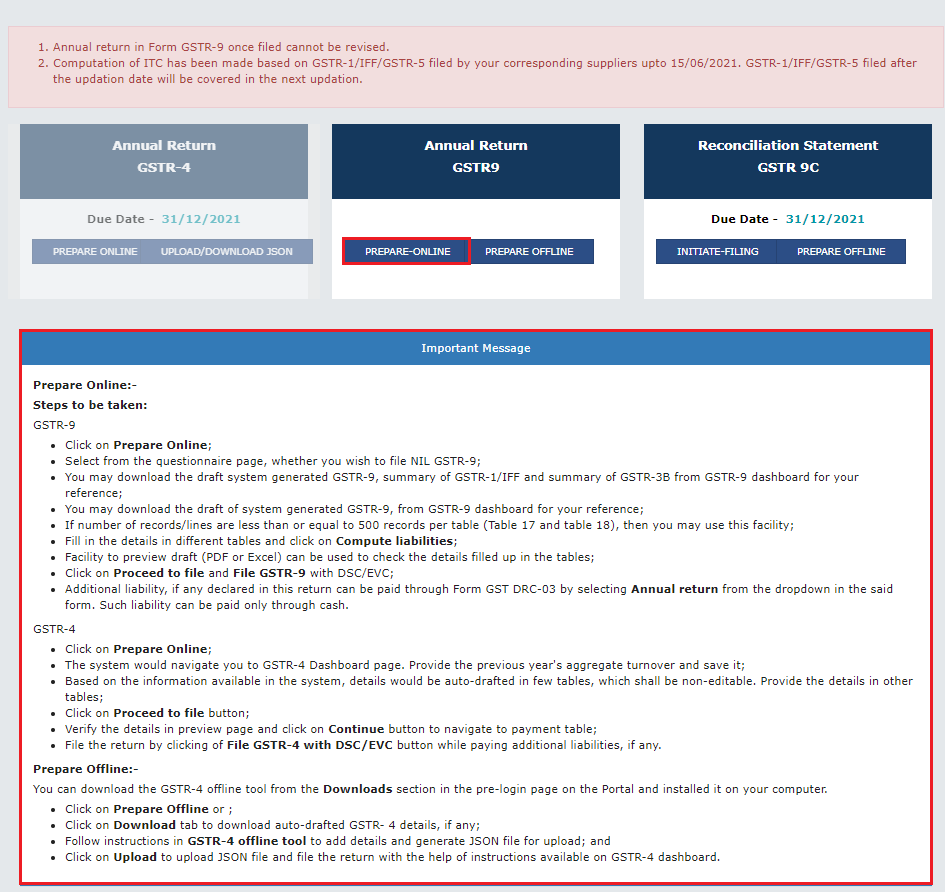
How to File GSTR-9 Online in 2026?
You must file GSTR-1 and GSTR-3B for the full financial year before filing GSTR-9. The GSTR-9 filing process involves several steps to ensure accuracy and follow the rules. Here's how to file the GSTR-9 annual return online:
- Log in to the GST Portal: Go to the GST portal (gst.gov.in) using your login details.
- Go to the Returns Dashboard: Select the financial year for which you want to file GSTR-9.
- Start GSTR-9 Filing: Choose "Prepare Online" or "Prepare Offline" (using the GSTR-9 offline utility for large data volumes). The 'Prepare Online' option is suitable for taxpayers with a smaller volume of data.
- Check Auto-Populated Data: The system will fill in many fields based on your filed GSTR-1 and GSTR-3B returns. Carefully check this data against your records.
- Enter Missing Details: Manually enter any additional required information in the various tables of GSTR-9, such as:
-
- Details of ITC reported, reversed, or not allowed.
- Details of tax paid, including tax due and tax paid by cash or ITC.
- Include any changes or corrections made this year for transactions from the previous financial year. These revised entries are reported in the current year's return.
- Review HSN Details: Check the HSN-wise outward supply details required in Table 17 and complete the applicable reporting in Table 18 based on the requirements for the relevant financial year.
- Calculate Taxes Due: Review any additional tax liability shown in the return and make the required payment through the applicable mechanism.
- Make Payment (if any): Pay any outstanding taxes or late filing fees.
- Preview and Check: Download the draft GSTR-9 and carefully look over all the details for errors before final submission.
- Submit the Return: Once satisfied, send the return using a Digital Signature Certificate (DSC) or Electronic Verification Code (EVC).
- Downloading GSTR-9: You can download the draft or filed GSTR-9 as a PDF/Excel from the Returns Dashboard on the GST portal (Annual Return → GSTR-9 → Download).
- File GSTR-9C (if it applies): If your aggregate turnover exceeds ₹5 crore, furnish the self-certified GSTR-9C along with GSTR-9 as part of the complete annual return.
Note: You must file GSTR-1 and GSTR-3B for the entire financial year before submitting GSTR-9.
GSTR-9 Due Date
The standard due date for GSTR-9 is 31 December following the end of the relevant financial year, unless the government extends or changes the deadline.
For example, the due date for FY 2025-26 is 31 December 2026 (the FY 2024-25 due date was 31 December 2025).
Taxpayers should check the latest GST notification before filing because the government can extend annual return deadlines for specific financial years or taxpayer categories.
GSTR-9 Late Fees and Interest
Late filing of GSTR-9 can attract a late fee under Section 47 of the CGST Act and the corresponding State or Union Territory GST law. From FY 2022-23 onward, the late fee for GSTR-9 follows turnover-based slabs prescribed through Notification No. 07/2023-Central Tax.
| Aggregate turnover in the relevant financial year | Combined late fee per day | Maximum late fee |
| Up to ₹5 crore | ₹50 | 0.04% of turnover in the State or Union Territory |
| Above ₹5 crore and up to ₹20 crore | ₹100 | 0.04% of turnover in the State or Union Territory |
| Above ₹20 crore | ₹200 | 0.50% of turnover in the State or Union Territory |
The combined daily amount represents the CGST and SGST/UTGST components together. For example, the ₹50 daily late fee comprises ₹25 under CGST and ₹25 under the corresponding SGST/UTGST law. For turnover above ₹20 crore, the ₹200 daily amount comprises ₹100 under each applicable law.
Where GSTR-9C is applicable, the annual return under Section 44 is complete only when both GSTR-9 and GSTR-9C have been furnished. Under CBIC Circular No. 246/03/2025-GST (dated 30 January 2025), late fee is calculated for the delay in furnishing the complete annual return, rather than as separate late fees for GSTR-9 and GSTR-9C from the original due date. The calculation continues from the annual return due date until the date on which the complete annual return is furnished.
Interest can apply separately when a taxpayer has an outstanding tax liability. Interest and late fee are separate statutory liabilities, so payment of one does not replace the other.
Has the GSTR-9 Due Date Been Extended?
The statutory due date for GSTR-9 is 31 December following the end of the relevant financial year, as prescribed under Section 44 of the CGST Act and Rule 80 of the CGST Rules.
The government has extended GSTR-9 filing deadlines for certain financial years in the past. For example, the deadlines for the initial GST financial years were extended through government orders and notifications.
For FY 2025-26, the statutory due date is 31 December 2026. No extension has been notified as of September 2026. Taxpayers should check the latest CBIC or GST portal notification before filing because the government can extend the deadline for a particular financial year or taxpayer category.
Format of GSTR-9 Annual Return
The GSTR-9 return is divided into six parts covering taxpayer details, supplies, Input Tax Credit (ITC), tax paid, previous-year adjustments, and other information.
- Part I: Basic Details: Financial Year, GSTIN, legal name, and trade name.
- Part II: Details of Outward and Inward Supplies: Details of taxable, zero-rated, exempt, and reverse-charge supplies reported during the financial year.
- Part III: Details of ITC: Information on ITC availed, reversed, and reported in the GST returns filed during the financial year.
- Part IV: Details of Tax Paid: Details of tax payable and tax paid for the financial year, including applicable interest and late fees.
- Part V: Previous-Year Transactions: Details of transactions relating to the previous financial year that were reported in the returns of the current financial year within the permitted period. For applicable adjustments, the reporting window extends up to 30 November of the following financial year or the date of filing the annual return, whichever is earlier.
- Part VI: Other Information: Details such as demands and refunds, HSN-wise summary, and late fees payable and paid.
GSTR-9 Reconciliation Process
The GSTR-9 reconciliation process involves comparing the figures reported in the annual return with the taxpayer's GST returns and accounting records. Taxpayers should review the following areas before filing:
- Sales Reconciliation: Compare outward supplies reported in GSTR-1 and GSTR-3B with the sales recorded in the books of accounts.
- ITC Reconciliation: Match ITC reported in GSTR-3B with eligible ITC records and identify reversals or differences.
- Tax Liability Reconciliation: Verify that the tax liability reported in the annual return agrees with the tax paid through the periodic returns.
- Previous-Year Adjustments: Review transactions from the previous financial year reported in the subsequent year's returns within the permitted reporting period.
- Financial Records Reconciliation: Where GSTR-9C applies, reconcile the relevant GST figures with the financial statements and prepare the required self-certified reconciliation statement.
Completing these reconciliations before filing helps identify differences and supports accurate reporting in GSTR-9.
Connect with RegisterKaro and let our experts handle the legal hassle while you grow your business.
Frequently Asked Questions (FAQs)
Is GSTR-9 mandatory for all GST-registered taxpayers?
No, GSTR-9 is not mandatory for every GST-registered taxpayer in India. For FY 2024-25, taxpayers with aggregate turnover up to ₹2 crore are exempt from filing GSTR-9. Taxpayers exceeding ₹2 crore generally need to file GSTR-9, subject to applicable exemptions, taxpayer categories, and government notifications.
What is the turnover limit for GSTR-9 filing?
The current exemption applies to taxpayers with aggregate turnover up to ₹2 crore for FY 2024-25 onwards. Taxpayers exceeding ₹2 crore generally need to file GSTR-9 for the relevant financial year. Businesses should calculate aggregate turnover according to GST rules before determining their annual return filing requirement.
What is the due date for filing GSTR-9?
The standard due date for GSTR-9 is 31 December following the financial year. For FY 2025-26, the due date is 31 December 2026, unless the government extends or changes it. Always check the latest GST notification before filing, as the government can extend annual return deadlines for specific years or taxpayer categories.
What is the difference between GSTR-9 and GSTR-9C?
GSTR-9 is the annual GST return, while GSTR-9C reconciles GST information with the taxpayer's financial records. Taxpayers exceeding the applicable ₹5 crore turnover threshold generally need to furnish GSTR-9C. The taxpayer self-certifies GSTR-9C, and both forms complete the annual return when reconciliation applies.
What documents are required for GSTR-9 filing?
Taxpayers generally need GSTR-1, GSTR-3B, sales records, purchase records, ITC details, financial statements, and reconciliation workings for GSTR-9 filing. Businesses should also keep credit notes, debit notes, refund details, tax payment records, and applicable HSN information ready before preparing the annual return for accurate reporting.
Can I file GSTR-9 without filing GSTR-1 and GSTR-3B?
No, taxpayers should complete their applicable periodic GST returns before preparing GSTR-9. The annual return consolidates information reported during the financial year, so businesses must reconcile GSTR-1, GSTR-3B, and accounting records. Reviewing these records beforehand helps identify differences and prevents incorrect information in the annual return.
How can I file GSTR-9 online?
You can file GSTR-9 online through the GST portal after completing the applicable periodic returns. Select the relevant financial year under the annual return section, review available information, reconcile it with your records, enter required details, verify the return, and submit it using the applicable authentication method.
What is the late fee for filing GSTR-9 after the due date?
The GSTR-9 late fee is ₹50 per day for turnover up to ₹5 crore, ₹100 per day for turnover above ₹5 crore and up to ₹20 crore, and ₹200 per day for turnover above ₹20 crore, subject to the applicable maximum based on turnover. Interest may also apply if tax remains unpaid.
Does GSTR-9C also have a late fee?
No separate late fee applies to GSTR-9C from its own original due date. Where GSTR-9C applies, the late fee is calculated for the delay in furnishing the complete annual return, which includes both GSTR-9 and GSTR-9C. The calculation runs until both forms have been furnished.
Can GSTR-9 be revised after filing?
No, GSTR-9 does not provide a general revision facility after submission. Taxpayers should reconcile their GST returns, accounting records, ITC, tax payments, and other information before filing. If an error remains after submission, the taxpayer should examine the applicable GST provisions and available correction mechanisms.

Reviewed by
Joel DsouzaJoel Dsouza is a Chartered Accountant (CA) and compliance expert with over 7 years of hands-on experience in company registration, tax structuring, GST, ROC filings, and MCA compliance. As a qualified member of the Institute of Chartered Accountants of India (ICAI) and Co-Founder at RegisterKaro, he has personally advised more than 1,000 startups and SMEs across India, helping founders navigate incorporation, regulatory frameworks, and financial planning from Day 1. With deep expertise across all three levels of Finance and Portfolio Management, Joel is committed to promoting financial literacy and simplifying India's startup ecosystem through clear, actionable guidance that entrepreneurs can act on immediately.
Why Choose RegisterKaro for GSTR-9 Annual Return Filing?
Filing GSTR-9 requires accurate data, proper reconciliation, and careful review of the annual return before submission. RegisterKaro provides structured support throughout the filing process to help businesses prepare and submit their annual GST returns correctly.
- Experienced GST Filing Support: Get assistance from professionals experienced in annual GST return preparation and filing requirements.
- GSTR-1 and GSTR-3B Reconciliation: Compare periodic GST return data with accounting records to identify differences before filing GSTR-9.
- ITC and Tax Liability Review: Review Input Tax Credit, tax liability, tax payments, reversals, and other applicable details before submission.
- GSTR-9C Applicability Check: Determine whether your business needs to furnish the self-certified GSTR-9C based on the applicable aggregate turnover threshold.
- HSN and Return Data Validation: Review HSN-wise outward supply details and other applicable reporting requirements before submitting the annual return.
- Filing and Acknowledgement Support: Receive assistance with online submission and confirmation of the completed GSTR-9 filing.
What Our Clients Say
View All
Saniya Sheikh
 Verified
It was an amazing experience working with Registarkro! The entire process was incredibly smooth and well-handled. A special shout-out to my SPOC, Faha... Read more

Rajat Sharma
VerifiedI got my first LLP incorporated from registerkaro and it was such a hassle free and easy experience. Jiya made sure to keep me updated with the entire... Read more

alok pundir
VerifiedI am very much happy and fully satisfied with work of mr aman ajmera his service is amezing . There were no need to ask any work regarding my company... Read more

Pragya Mehta
VerifiedService and followup was great. I would specially like to thank Shubham for coordinating all formalities needed to incorporate the Company. I will def... Read more

SANTOSH KUMAR Yadav
VerifiedReally it was satisfactory experience with registerkaro for company incorporation got continuous support from their end now waiting for startup regist... Read more

Sonal Gakhar
VerifiedA big thank you for the outstanding support provided by your team, especially Mahima, Devesh and Kashish, in registering my company. Your team's dedic... Read more

Himaja Sree Tanneeru
VerifiedI had an amazing experience with RegisterKaro while opening my LLP. From the initial consultation to the final registration, their team was profession... Read more

Mystic Matrix
VerifiedThank you to the entire Register Karo team for providing excellent professional services to me and my company. We truly appreciate your patience and s... Read more

infotaxes fast
VerifiedI received excellent service; specifically, Shruti Pandey handled all aspects of setting up my company incorporation and provided timely updates. Than... Read more

Abhisek Agarwal
VerifiedIt was a nice experience getting my incorporation done through RegusterKaro. Jiya was a great help throughout the process. Thank you Jiya and Register... Read more
Related Blogs
View All
How to Start a Masala Business in India?

How to Start a Coaching Institute in India?

How to Start a Bottled Water Business in India?
Compliance Calendar for Producer Company in India
How to Apply for DIN Number: DIR-3 Process & SPICe+ for Directors
Virtual CFO Cost in India for Startups: Fees & Pricing
Accounting Outsourcing Cost in India: Complete Pricing Guide
Documents Required for GST Registration in India (Checklist)

How to Start a Scrap Business in India: Setup & Profit
How to Register a Media Company in India: Process & Licenses