GST Calculator Online - Calculate GST in India (2026 Rates)
What is GST and its Features?
Goods and Services Tax (GST) is an indirect tax system that came into effect in India in 2017. The government introduced GST to replace multiple old taxes, including Value-Added Tax (VAT), Excise Duty, and Service Tax. GST follows the principle of "One Nation, One Tax," ensuring uniform taxation across India.
Key Characteristics of GST
- Single Indirect Tax System: GST has replaced multiple indirect taxes such as VAT, Service Tax, and Excise Duty, bringing everything under one unified tax system.
- Uniform Tax Structure: GST offers the same tax rates and policies across all states in India. This helps prevent tax-related confusion.
- Digital Compliance: All GST processes like registration, return filing, and tax payment are done online. This ensures transparency, reduces paperwork, and simplifies business operations.
- Destination-Based Tax: GST is charged at the point of consumption, not where goods are produced.
- Input Tax Credit (ITC): GST enables businesses to claim credit for taxes paid on their purchases to adjust against their final tax liability. This avoids double taxation and reduces the cost of goods and services.
How Does GST Work? GST Calculation Method
GST reduces the cascading effect of taxes by allowing businesses to claim Input Tax Credit (ITC) on eligible purchases. This prevents repeated taxation as goods and services move through the supply chain.
The method works in two directions at once. At each stage, a business charges GST on its full selling price and collects it from its buyer. It then deducts the GST it already paid on its own purchases and deposits only the difference with the government. The result is that each business is effectively taxed only on the value it adds.
The final consumer is the exception. They cannot claim ITC, so they bear GST on the full value of the finished product, which is also why the total tax the government collects across the whole chain equals the GST on the final sale price, no matter how many hands the goods pass through.
See the worked examples below for how this plays out on a single invoice and across a full supply chain.
GST Tax Slabs in India: Complete List of Applicable Rates (2026)
India's GST structure has four primary slabs (0%, 5%, 18%, and 40%) following the 2025 tax reforms. A few niche rates still apply to specific categories too.
Primary Slabs
- 0% (Nil rate): Applies to essential items considered necessities, such as fresh milk, unbranded food grains, certain medicines, and educational materials.
- 5% Tax Rate: A lower tax rate for many common goods and basic household items like packaged cereals and pulses, hair oil, toothpaste, and soap.
- 18% Tax Rate: The standard rate for most consumer goods and services. Example: electronics, mobile phones, telecom and financial services, and most processed foods.
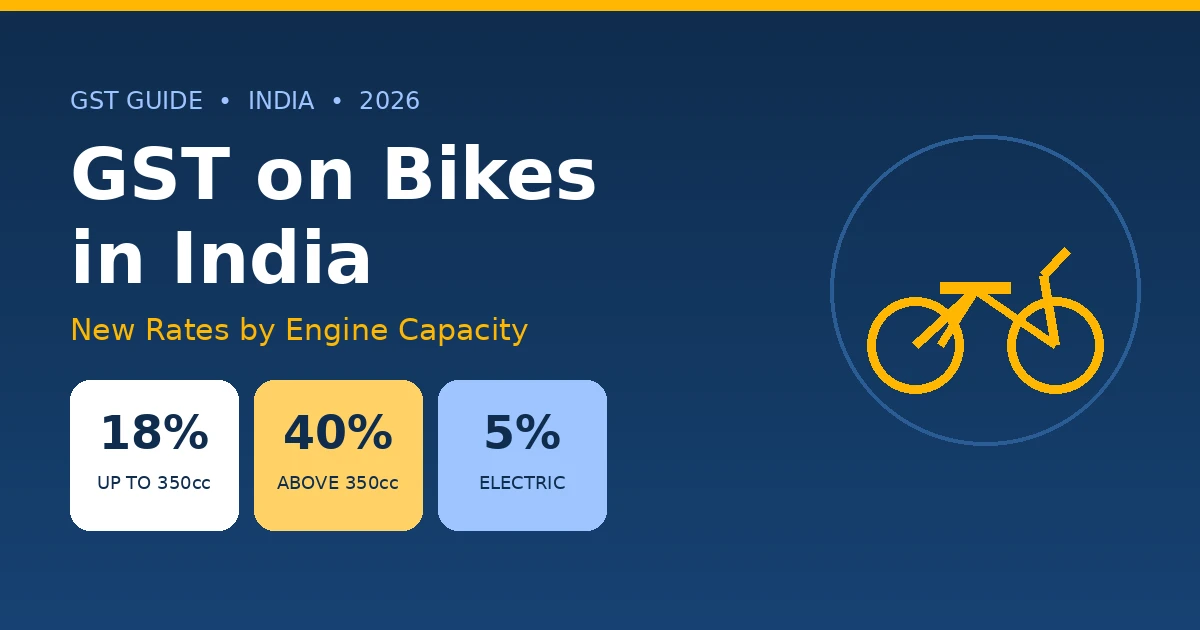
- 40% (Special/Demerit Rate): Applied to select luxury, sin, or premium goods considered non-essential, such as pan masala, unmanufactured tobacco, cigars, cigarettes and nicotine products (from 1 February 2026 - bidis remain at 18%); aerated, carbonated and caffeinated beverages; motor cars above 1500cc; motorcycles above 350cc; yachts and private aircraft; revolvers and pistols; betting, gambling, casinos, lottery and online money gaming; and admission to IPL-class sporting events
Niche GST Rates That Still Apply
A handful of specific categories fall outside the four primary slabs:
- 0.1% - Merchant exports (0.05% CGST + 0.05% SGST intra-state)
- 0.25% - Rough diamonds and unworked precious or semi-precious stones
- 1% - Composition scheme for traders and manufacturers; also the effective rate on affordable housing
- 1.5% - Cut and polished diamonds, and diamond job-work services
- 3% - Gold, silver, platinum and jewellery. GST 2.0 did not change this rate
- 6% - Composition scheme for service providers under Section 10(2A); also bricks and fly-ash blocks supplied without ITC
Use the calculator above to select the exact rate that applies to your specific goods or services.
GST Rate Changes 2026: What Moved From 12% and 28%
Before 22 September 2025, India had six GST slabs. GST 2.0 collapsed them to four.
| Old rate | Now | What moved |
| 12% | 5% or 18% | Most 12% goods went to 5%; all 12% services went to 18% |
| 28% | 18% or 40% | Consumer durables and cement to 18%; luxury cars, tobacco and aerated drinks to 40% |
| 28% + cess | 40%, no cess | Compensation cess was folded into the headline rate |
Which rate applies to an older invoice? The rate in force on the date of supply. An invoice dated 20 September 2025 carries the old rate; 22 September 2025 onwards carries the new one.
GST Compensation Cess: Why It No Longer Applies
Compensation cess was discontinued on almost all goods from 22 September 2025, with the incidence folded into the GST rate itself, that is the reason the 40% slab exists. Notification 03/2025-Compensation Cess (Rate) then reduced cess on tobacco products to nil from 1 February 2026. It has been replaced by a revived central excise duty and the Health Security and National Security (HSSNS) Cess.
What this means for your calculation: you no longer add compensation cess on top of GST for cars, coal or aerated drinks. The 40% rate already contains it. An invoice charging 28% plus cess for a current supply is using a structure that no longer exists.
Who Should Register for GST?
GST registration is mandatory for:
- Businesses supplying goods with an annual turnover of above ₹40 lakh.
- Service providers whose annual turnover crosses ₹20 lakh.
- Special category states have lower thresholds, ₹20 lakh for goods and ₹10 lakh for services, but the two apply to different sets of states. ₹10 lakh for services applies in only four: Manipur, Mizoram, Nagaland and Tripura. ₹20 lakh for goods applies in ten: Arunachal Pradesh, Meghalaya, Mizoram, Manipur, Nagaland, Sikkim, Tripura, Uttarakhand, Puducherry and Telangana. Jammu & Kashmir, Ladakh and Assam opted up to the standard ₹40 lakh.
- Inter-state suppliers of goods must register regardless of turnover. Inter-state suppliers of services below ₹20 lakh (₹10 lakh in the four special category states) are exempt under Notification 10/2017-Integrated Tax.
- E-commerce operators must register regardless of turnover under Section 24(x). Sellers on those platforms are treated differently: since 1 October 2023, a seller of goods below the threshold is exempt if they supply through an ECO in a single State or UT, make no inter-state supply, hold a PAN and obtain an enrolment number on the portal (Notification 34/2023-CT). Service sellers below the threshold are exempt under Notification 65/2017-CT, except where the operator pays under Section 9(5).
- For a casual or non-resident taxable person, registration is mandatory.
These businesses can file GST returns for safe business accounting and a comprehensive record of a business's financial activities.
What are the Different Types of GST? Key Categories
GST is divided into four different categories. Each type applies depending on whether goods or services are supplied within a state, across states, or in a Union Territory. Here's how each one works:
- Central Goods and Services Tax (CGST): CGST is a tax collected by the Central Government on the sale of goods and services within the same state.
- State Goods and Services Tax (SGST): SGST is collected by the State Government on intra-state transactions (buying and selling within the same state). On an intra-state transaction, GST is divided between the state and central government. This creates two different components, CGST and SGST.
- Integrated Goods and Services Tax (IGST): IGST is charged when goods or services move from one state to another (inter-state trade). The central government collects this and later divides the portion among the states where the goods are consumed.
- Union Territory Goods and Services Tax (UTGST): UTGST applies to Union Territories (like Chandigarh, Lakshadweep). This is collected by Union Territory administrators and shared with the central government.
How to Calculate Exclusive & Inclusive GST: Example Using Formula
GST calculations can be done in two ways, depending on whether the given amount excludes GST or already includes GST.
1. GST Exclusive Calculation: Add GST to a Base Price
GST Exclusive Price refers to the base price of a product or service before adding GST. To get the final price payable, GST is added to this base amount.
- Formula:
- GST amount = (Base Price × GST%) ÷ 100
- Invoice Value = Base Price + GST amount
- Example:
- Base Price = ₹1,000
- GST percentage = 18%
- GST amount = (1,000 × 18) ÷ 100 = ₹180
- Invoice Value = 1,000 + 180 = ₹1,180
2. GST Inclusive Calculator: Remove GST From a Total
GST Inclusive Price means the amount you pay with GST added to it. To find the base price, the GST portion needs to be calculated and deducted.
- Formula:
- GST amount = Invoice Value − [Invoice Value × 100 ÷ (100 + GST%)]
- Base Price = Invoice Value − GST amount
- Example:
- Invoice Value (GST inclusive) = ₹1,180
- GST percentage = 18%
- GST amount = 1,180 − [1,180 × 100 ÷ 118] = ₹180
- Base Price = 1,180 − 180 = ₹1,000
How to Calculate GST Percentage From Any Amount
Sometimes you know the amounts but not the rate; a supplier sends a total, or you are checking whether an invoice used the right slab. There are two situations.
If you know the base price and the GST amount:
GST % = (GST amount ÷ Base Price) × 100
A base price of ₹1,000 with ₹180 GST gives (180 ÷ 1,000) × 100 = 18%.
If you only know the base price and the total:
GST % = [(Invoice Value − Base Price) ÷ Base Price] × 100
A base of ₹1,000 and a total of ₹1,180 gives [(1,180 − 1,000) ÷ 1,000] × 100 = 18%.
To pull the GST portion out of a total when you already know the rate:
GST amount = Invoice Value × GST% ÷ (100 + GST%)
On ₹1,180 at 18%: 1,180 × 18 ÷ 118 = ₹180.
A quick sanity check: if the calculated percentage does not land on 0%, 5%, 18% or 40%, or one of the special rates of 0.1%, 0.25%, 1%, 1.5%, 3% or 6%, the invoice is either using an obsolete slab or has a rounding error.
Note on rounding: Under Section 170 of the CGST Act, GST is rounded to the nearest rupee, 50 paise and above rounds up, below 50 paise is ignored. Rounding is applied per invoice and per tax head separately, so CGST and SGST are each rounded on their own rather than the combined figure. This is the most common reason a manually calculated total differs by a rupee or two from accounting software.
GST Calculation Examples
The two calculations below show GST in its simplest form and then across a full supply chain. Both use 18% for illustration, check the rate that actually applies to your goods or services before you invoice.
Example 1: GST on a Single Invoice
A business in Maharashtra sells goods with a base price of ₹10,000 at 18% GST.
| Particulars | Amount |
| Base price | ₹10,000 |
| GST rate | 18% |
| GST amount | ₹1,800 |
| CGST (intra-state) | ₹900 |
| SGST (intra-state) | ₹900 |
| IGST (inter-state) | ₹1,800 |
| Invoice value | ₹11,800 |
If the buyer is also in Maharashtra, the ₹1,800 splits equally into ₹900 CGST and ₹900 SGST. If the buyer is in Gujarat, the whole ₹1,800 is charged as IGST instead. The customer pays ₹11,800 either way, only the split between the state and the centre changes.
Example 2: GST Across a Supply Chain
Follow a chair from timber to shop floor. Each business charges GST on its full selling price, claims credit for the GST it already paid, and deposits only the difference.
Step 1: Timber seller to manufacturer
The manufacturer buys wood for ₹1,000 and pays 18% GST of ₹180, so the invoice is ₹1,180. The timber seller deposits that ₹180 with the government.
Step 2: Manufacturer to wholesaler
After making the chair, the manufacturer sells it for ₹2,000 plus 18% GST of ₹360, an invoice of ₹2,360. Because they already paid ₹180 GST on the wood, they claim Input Tax Credit and deposit only ₹360 − ₹180 = ₹180.
Step 3: Wholesaler to retailer
The wholesaler adds a margin and sells at ₹2,500 plus 18% GST of ₹450, an invoice of ₹2,950. They claim ITC on the ₹360 already paid and deposit ₹450 − ₹360 = ₹90.
Step 4: Retailer to customer
The retailer sells the chair at ₹3,000 plus 18% GST of ₹540, so the customer pays ₹3,540. The retailer claims ITC on the ₹450 already paid and deposits ₹540 − ₹450 = ₹90.
| Stage | Sale value | GST charged | ITC claimed | Deposited to government |
| Timber seller | ₹1,000 | ₹180 | – | ₹180 |
| Manufacturer | ₹2,000 | ₹360 | ₹180 | ₹180 |
| Wholesaler | ₹2,500 | ₹450 | ₹360 | ₹90 |
| Retailer | ₹3,000 | ₹540 | ₹450 | ₹90 |
| Total | ₹540 |
What the numbers show: The government collects ₹540 in total, exactly 18% of the final ₹3,000 sale price, and exactly what the customer paid. No stage was taxed twice, because each business only remitted tax on the value it added: ₹1,000 + ₹1,000 + ₹500 + ₹500 = ₹3,000.
This is the difference GST made. Under the old VAT and excise system, tax charged at one stage often could not be credited at the next, so it accumulated in the price. Here it does not.
How to Use RegisterKaro’s Free Online GST Calculator?
Calculating GST manually for large amounts, multiple items, or different transactions can take time. Small errors can throw off your invoicing or tax filings too. Our free online GST Calculator handles this instantly, giving you an accurate breakdown in seconds. Here's exactly how to use it:
Step 1. Enter the amount: Type in the value you're working with. This could be the base price of your product or service before tax, or the final price a customer actually pays, depending on what you already know.
Step 2. Select the GST rate: Choose the applicable rate from the dropdown: 0%, 0.1%, 0.25%, 1%, 1.5%, 3%, 5%, 6%, 18%, or 40%.
Step 3. Specify whether the amount includes GST: If you entered the price before tax, select "No." If you entered the final price a customer pays, with GST already included, select "Yes."
This tells the calculator which formula to apply: GST Exclusive or GST Inclusive.
Step 4. Indicate whether you're selling within the same state: This determines how your GST breaks down. For a same-state (intra-state sale), the tool splits the tax equally into CGST and SGST components. For a different-state (inter-state sale), the tool calculates the full amount as IGST instead.
Step 5. Review your results: The calculator instantly displays the GST amount, or the CGST/SGST split, or the IGST, depending on your transaction type. It also shows the total invoice value, amount plus GST, and the base price before GST, if you started from a GST-inclusive figure.
This makes the tool useful for generating invoices, verifying a supplier's bill, budgeting a purchase, or double-checking your GST return figures before filing.
Why Use RegisterKaro’s Free GST Calculator?
You can also use RegisterKaro's GST calculator to compute your GST amount. Our calculator has the following advantages:
- Fast and Accurate Calculations: RegisterKaro's GST calculator ensures fast and accurate GST calculations within seconds.
- Supports Inclusive & Exclusive GST: It helps find GST-inclusive or exclusive prices based on chosen tax slabs.
- User-Friendly and Easy GST Calculator: It supports a simple and user-friendly tool suitable for individuals and businesses. It is a free GST calculator, so anyone can use it online.
- Prevents Manual Errors: It reduces manual errors and supports better tax compliance.
- Helps in Tax Compliance: The calculator provides accurate tax components, making return filing and invoicing easier.
- Suitable for All GST Slabs: Covers every rate in force under the 2026 structure; 0%, 5%, 18% and 40%, plus the special rates for gold, diamonds, merchant exports and composition taxpayers.
Frequently Asked Questions
GST calculations get complicated with different slabs and components like CGST, SGST, and IGST. A GST calculator gives instant, accurate results, especially useful for billing, budgeting, and comparing prices across suppliers.