

AOC-4 is the MCA filing form used by companies to submit their financial statements and related documents to the Registrar of Companies (RoC). Companies file AOC-4 through the MCA V3 portal to ensure transparency and accountability in a company’s financial reporting. The requirement comes from Section 137 of the Companies Act, 2013, read with Rule 12 of the Companies (Accounts) Rules, 2014. Missing the deadline attracts an additional fee of ₹100 per day with no upper cap, along with applicable penalties for continued default.
Banks, investors, lenders, and regulators may rely on these filed statements when assessing or dealing with the company. Along with Form MGT-7, timely filing keeps the company’s RoC compliance status in order. It also preserves its eligibility for certain exemptions, such as the private company exemption from auditor reporting on internal financial controls.
Key Takeaways
AOC-4 is the MCA e-form used by companies to file their annual financial statements and related documents with the Registrar of Companies (RoC).
The filing generally includes the Balance Sheet, Statement of Profit and Loss, the Cash Flow Statement (where applicable), the Auditor's Report, and the Board's Report, along with other prescribed information.
Most companies registered under the Companies Act, 2013, including Private Limited Companies, Public Limited Companies, OPCs, and Section 8 Companies, must file AOC-4, subject to applicable exemptions and filing formats.
Companies with specific reporting requirements may need AOC-4 XBRL, AOC-4 CFS, or AOC-4 NBFC (Ind AS) instead of the standard AOC-4 form. Companies that prepare consolidated financial statements also file AOC-4 CFS alongside their standalone form.
Most companies must file AOC-4 within 30 days of their Annual General Meeting, while a One Person Company files within 180 days of the financial year-end.
Since the MCA V3 rollout, AOC-4 is filed as an online web form (with the Board's and Auditor's Reports as linked forms).
What is the AOC-4 Form?
Form AOC-4 is the annual e-form through which a company files its financial statements and related documents with the RoC. The full form of AOC-4 is “Form for Filing Financial Statements and Other Documents with the Registrar.” The form is filed online through the MCA V3 portal (mca.gov.in), creating an official record of the company's financial reporting.
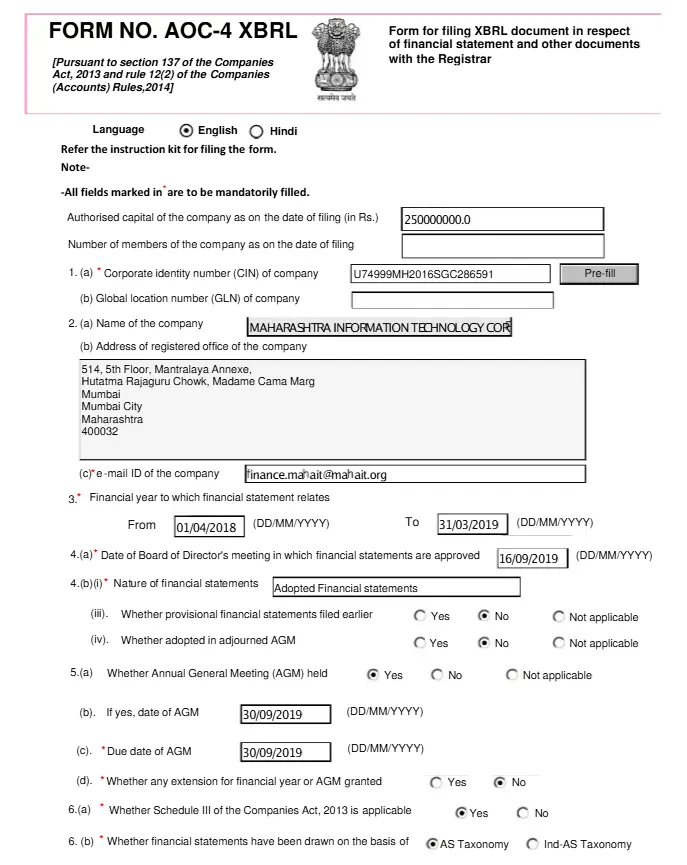
Through Form AOC-4, a company submits:
Balance Sheet
Profit and Loss Account
Cash Flow Statement (where applicable)
Auditor's Report
Board's Report
Why is Filing Form AOC-4 Important?
Filing Form AOC-4 is a statutory requirement that keeps a company's financial reporting up to date with the RoC. It is important because it:
Fulfills a statutory requirement: Section 137 requires companies to file their financial statements with the RoC, and late filing can result in additional fees and penalties.
Records the company's financial position: The filing reports key financial information, including income, expenses, assets, and liabilities, for the relevant financial year.
Helps stakeholders assess the company: Shareholders, investors, lenders, and creditors can use the filed financial statements when evaluating the company's financial position and making informed decisions.
Maintains an accessible corporate record: AOC-4 filings become part of the company's records available through the MCA portal, subject to applicable access rules.
Supports business credibility: Consistent and timely financial reporting demonstrates that the company is meeting its statutory disclosure requirements.
Note: A company with no business activity must still ordinarily file AOC-4 unless it has obtained dormant status under the Companies Act. A company with dormant status must file Form MSC-3 instead.
Who Can Sign and Certify Form AOC-4?
Form AOC-4 must be digitally signed before filing, and most companies also require certification by a practicing professional.
Company signatory: A director authorized by the Board signs the form using their Digital Signature Certificate (DSC).
Professional certification: Where applicable, a practicing Chartered Accountant, Company Secretary, or Cost Accountant certifies the form after verifying the information against the company's books and records.
Note: One Person Companies and small companies are exempt from professional certification and can file AOC-4 using the authorized director's DSC.
Types of AOC-4 Form: AOC-4, AOC-4 XBRL, and AOC-4 CFS
AOC-4 is available in different formats based on the company's reporting requirements, financial reporting framework, and whether consolidated financial statements are required.
These include:
Form | What It Covers | Filing Format |
AOC-4 (standard) | Standalone financial statements | Web form with PDF attachments |
AOC-4 XBRL | Standalone and consolidated financial statements of XBRL-covered companies | XBRL instance document, prepared with XBRL tagging software and checked with the MCA’s validation tool |
AOC-4 CFS | Consolidated financial statements of non-XBRL companies with subsidiaries, associates, or joint ventures | Web form with PDF attachments, filed in addition to the standalone AOC-4 |
AOC-4 NBFC (Ind AS) | Standalone financial statements of NBFCs reporting under Ind AS. Consolidated statements go through the linked AOC-4 CFS NBFC (Ind AS) | Separate form for Ind AS NBFCs, which are excluded from XBRL filing |
Who Needs to File AOC-4?
Almost every company registered in India must file Form AOC-4 each financial year to submit its financial statements to the Registrar of Companies. The form a company uses depends on its category:
All registered companies: Private, public, OPC, and Section 8 companies must file AOC-4. This includes inactive companies with no business activity. A company with dormant status under Section 455 files Form MSC-3 instead.
Companies covered under XBRL: Listed companies and their Indian subsidiaries, companies with paid-up capital of ₹5 crore or more, companies with turnover of ₹100 crore or more, and companies that prepare accounts under Ind AS must use AOC-4 XBRL. This filing may continue in later years even if the company falls below these thresholds.
Companies with subsidiaries, associates, or joint ventures: These companies must file consolidated financial statements through AOC-4 CFS, along with their standalone AOC-4. XBRL-covered companies file both through AOC-4 XBRL.
Non-Banking Financial Companies (NBFCs): NBFCs that prepare their accounts under Ind AS must file AOC-4 NBFC (Ind AS) for standalone or consolidated financial statements.
Companies with CSR obligations: Companies covered by Section 135 must file Form CSR-2 as a linked form with AOC-4 from FY 2024-25 onward.
When is the AOC-4 Form Due?
The AOC-4 due date depends on the type of company and whether it holds an Annual General Meeting (AGM):
Companies holding an AGM: File within 30 days of the AGM. This is the same rule for private, public, and Section 8 companies.
One Person Companies (OPCs): File within 180 days from the end of the financial year, as an OPC is not required to hold an AGM.
Companies not holding an AGM: File within 30 days of the date on which the AGM should have been held, along with the reasons for not holding it.
Adjourned AGM: If the company does not adopt its financial statements at the original AGM, it must file the unadopted statements and other documents required under Section 137(1) within 30 days of that AGM. The Registrar records these filings provisionally. Once the company adopts the financial statements at the adjourned AGM, it must file the adopted statements within 30 days of that meeting.
For example, if a company's financial year ends on 31 March 2027 and it holds its AGM on 30 September 2027, it must file AOC-4 by 30 October 2027, unless an extension applies.
Note: The MCA introduced the Companies Compliance Facilitation Scheme 2026 (CCFS-2026) to help companies clear pending filings, offering a 90% waiver on additional RoC filing fees for overdue forms, including AOC-4. The scheme was extended until 15 September 2026 and has now closed. Companies with pending filings should check the MCA portal for any new compliance scheme or extension before relying on a fee waiver.
AOC-4 Filing Deadlines for FY 2026-27
Type of company | Filing frequency | Due date (FY 2026-27) | Remarks |
One Person Company (OPC) | Yearly | 27 September 2027 | Within 180 days of the financial year-end (no AGM required) |
Yearly | 30 October 2027 | Within 30 days of the AGM (if held on 30 September 2027) | |
Yearly | 30 October 2027 | Within 30 days of the AGM | |
Yearly | 30 October 2027 | Within 30 days of the AGM | |
Company with subsidiaries (AOC-4 CFS) | Yearly | 30 October 2027 | File AOC-4 and AOC-4 CFS within 30 days of the AGM |
Note: These deadlines assume the AGM is held on the last permissible day (30 September 2027). The actual due date is 30 days from your company's own AGM date, and can shift if the MCA announces an extension.
Which Documents do you Need to File with Form AOC-4?
The documents required with AOC-4 depend on the company's type and activities, but most filings follow a common set of requirements. These are:
Audited financial statements: Balance Sheet, Profit and Loss Account, Cash Flow Statement where applicable, and notes to accounts.
Board's Report and Auditor's Report: Completed through linked web forms on MCA V3 rather than attached separately as PDFs.
Form AOC-1: Required where the company has subsidiaries, associates, or joint ventures.
Form CSR-2: Required as a linked form for companies covered by Section 135.
Secretarial Audit Report: Required for prescribed companies, where applicable.
CAG comments: Required for government companies, where applicable.
Related-party transaction details and other declarations: Required where applicable for the relevant financial year.
Notes:
Under the MCA V3 portal, some documents that were previously uploaded as PDFs, particularly the Board's Report and Auditor's Report, are now completed through linked web forms.
For AOC-4 XBRL, the company must submit the XBRL data file and a signed PDF of the financial statements. The filing generally requires certification by a practicing Chartered Accountant or Company Secretary, except where OPCs and small companies are exempt from such certification.
How to File Form AOC-4 on the MCA V3 Portal?
Since 14 July 2025, AOC-4 filing has moved to the MCA V3 portal, which uses web-based forms instead of the earlier download-and-upload process. Follow these steps to fill in and file AOC-4:
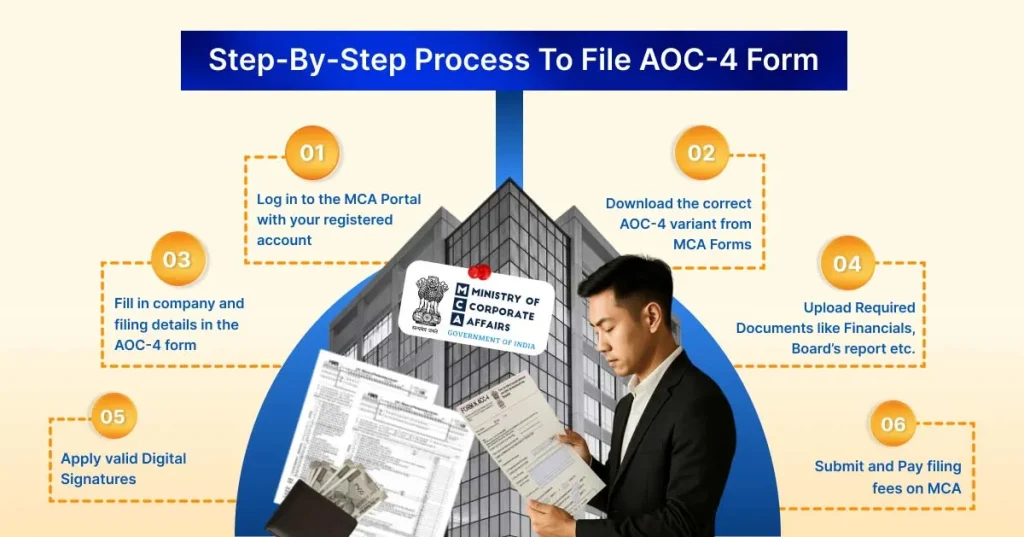
Log in to MCA V3: Sign in to the MCA portal using your registered business user account.
Select the AOC-4 variant: Choose the applicable form: AOC-4, AOC-4 XBRL, AOC-4 CFS, or AOC-4 NBFC (Ind AS). V3 supports both online filing and the offline Excel utility.
Complete linked forms: Fill in the Board's Report and Auditor's Report through the linked web forms. File CSR-2 as a linked form where applicable.
Enter financial details: Complete the financial statement fields and attach the audited financial statements and other required documents, such as AOC-1 where applicable.
Apply DSC: Digitally sign the form using the authorized director's DSC and, where required, the certifying professional's DSC.
Submit and pay: Submit the form, pay the applicable filing fee online, and note the SRN generated for tracking.
How to Access Form AOC-4 on the MCA V3 Portal?
On the MCA V3 portal, AOC-4 is available as a web-based form, with an offline utility available where applicable. To access it:
Visit the MCA portal and sign in with your registered account, or create one if required.
Go to MCA Services → e-Filing → Company Forms and select the applicable variant: AOC-4, AOC-4 XBRL, AOC-4 CFS, or AOC-4 NBFC (Ind AS).
Complete the form online or use the offline Excel utility, where available, to prepare and upload the required data.
Review the relevant MCA instruction kit before completing the form to understand the required fields, attachments, and certification requirements.
The applicable AOC-4 variant and filing mode depend on the company's reporting requirements.
Fees for Filing Form AOC-4
The Companies (Registration Offices and Fees) Rules, 2014, prescribe the filing fees for Form AOC-4, which vary based on the company’s nominal share capital.
Nominal Share Capital | Fee Applicable |
Less than ₹1,00,000 | ₹200 per document |
₹1,00,000 to ₹4,99,999 | ₹300 per document |
₹5,00,000 to ₹24,99,999 | ₹400 per document |
₹25,00,000 to ₹99,99,999 | ₹500 per document |
₹1,00,00,000 or more | ₹600 per document |
Note: For companies without share capital, the fee is a flat ₹200 per document.
What Happens If You File Form AOC-4 Late?
Late AOC-4 filing can result in both additional filing fees and statutory penalties.
Additional filing fee: ₹100 per day of delay under Section 403 of the Companies Act, 2013, with no maximum cap.
Company: ₹10,000 plus ₹100 per day of continuing default, subject to a maximum of ₹2 lakh, under Section 137(3).
Managing Director/CFO or responsible director: ₹10,000 plus ₹100 per day of continuing default, subject to a maximum of ₹50,000, under Section 137(3).
Director disqualification: Under Section 164(2), if a company fails to file its financial statements or annual returns for three consecutive financial years, every director of the company becomes disqualified for five years. During this period, the director cannot be reappointed in that company or appointed as a director in any other company.
Note: The ₹100-per-day additional filing fee under Section 403 and the penalties under Section 137(3) are separate consequences and can apply together. The additional filing fee continues until the form is filed, while the Section 137(3) penalty applies to the statutory default.
Common Mistakes to Avoid When Filing AOC-4
Errors in AOC-4 can lead to resubmission requests, filing delays, or additional fees. Check these common issues before submitting the form:
Choosing the wrong variant: Filing standard AOC-4 when AOC-4 XBRL, AOC-4 CFS, or AOC-4 NBFC (Ind AS) applies can result in rejection or require resubmission.
Omitting AOC-1: Companies with subsidiaries, associates, or joint ventures may need to attach the prescribed AOC-1 statement with details of these entities.
Uploading incomplete XBRL documents: XBRL filers must submit the XBRL data file along with the required signed PDF of the financial statements.
Reporting mismatched figures: Figures entered in AOC-4 should match the audited financial statements and supporting documents. Differences can trigger queries or resubmission.
Using an invalid DSC or missing certification: The authorized director's DSC must be valid, and professional certification must be completed where applicable. OPCs and small companies are exempt from this certification requirement.
Missing linked forms: Check that the required Board's Report, Auditor's Report, and other linked web forms are completed before submitting the filing on MCA V3.
AOC-4 vs MGT-7: What's the Difference
While AOC-4 and MGT-7 are annual filings with the RoC, they serve different purposes. AOC-4 covers financial statements, while MGT-7 covers the annual return and corporate information. Here’s how they differ:
Aspect | Form AOC-4 | Form MGT-7 / MGT-7A |
Purpose | Filing of financial statements | Filing of the annual return |
What it contains | Balance Sheet, Profit & Loss, Cash Flow (if applicable), Auditor's Report, Board's Report | Company details, registered office, shareholding pattern, directors, and changes during the year |
Legal basis | Section 137, Rule 12 of the Companies (Accounts) Rules, 2014 | Section 92, Rule 11 of the Companies (Management and Administration) Rules, 2014 |
Due date | Within 30 days of the AGM | Within 60 days of the AGM |
Form used | AOC-4 (and its variants) | MGT-7, or MGT-7A for OPCs and small companies |
In short, AOC-4 tells the RoC how the company performed financially, while MGT-7 tells it who owns and runs the company. Both are due after the AGM and both attract the ₹100-per-day late fee if missed, as part of your company’s annual ROC compliance.

Comments
Be the first to comment!