
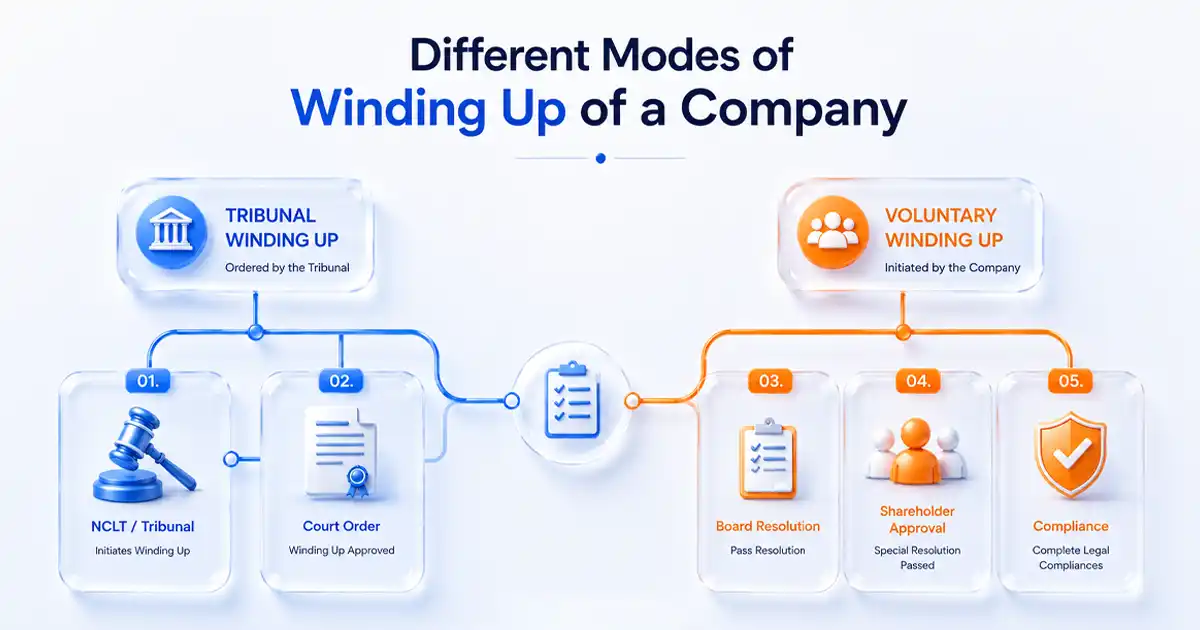
The three modes of winding up of a company in India are voluntary liquidation of a solvent company, liquidation of an insolvent company, and compulsory winding up by the Tribunal. The applicable route depends mainly on the company’s financial position and the circumstances leading to closure.
The route a company takes depends on its financial position and the circumstances leading to closure:
- If the company can pay its debts (solvent): The owners can choose voluntary liquidation under Section 59 of the Insolvency and Bankruptcy Code, 2016 (IBC).
- If the company cannot pay its debts (insolvent): It may enter the Corporate Insolvency Resolution Process (CIRP). If no viable rescue plan is approved, the company moves to liquidation.
- If a court orders closure: The NCLT can order compulsory winding up under Section 271 of the Companies Act, 2013, including cases involving fraud or failure to file financial statements or annual returns for the immediately preceding five consecutive financial years.
Each route ultimately leads to dissolution after the company’s assets and liabilities are dealt with according to the applicable law. The IBC (Amendment) Act, 2026 has also changed liquidation timelines and increased creditor involvement in the process.
Key Takeaways
- A company in India winds up through voluntary liquidation, insolvency-led liquidation, or compulsory winding up by the NCLT.
- In voluntary liquidation, directors file a Declaration of Solvency, members pass a special resolution, and the liquidator must finish within 90 days, or 270 days where creditors approve the resolution.
- A default of ₹1 crore or more lets a creditor or the company file for CIRP, and a failed CIRP ends in liquidation, targeted at 180 days plus a 90-day extension.
- Creditors cannot file a winding-up petition under Section 272 of the Companies Act, 2013, and must instead use Sections 7 or 9 of the IBC.
- Members’ and creditors’ voluntary winding-up no longer exist because the IBC omitted Sections 304 to 323 of the Companies Act, 2013.
- Section 59(5A) of the IBC lets a company end voluntary liquidation and resume business, under Regulation 42 effective June 1, 2026.
Did You Know: The Ministry of Corporate Affairs launched the Centre for Processing Accelerated Corporate Exit (C-PACE) in 2023 to process strike-off applications under Section 248 of the Companies Act, 2013.
Modes of Winding Up of a Company at a Glance
The table below compares the three modes at a glance:
| Mode | Governing law | When it’s used | Who initiates it |
| Voluntary liquidation | Section 59, IBC, 2016 | A solvent company that can pay its debts chooses to close | The company’s members (shareholders) |
| Compulsory winding up by the Tribunal | Section 271, Companies Act, 2013 | Closure ordered by the NCLT on specific grounds, such as fraud or five consecutive years of missed annual filings | Petition to the NCLT by the company, a contributory, the Registrar, a person authorized by the Central Government, or the Central or State Government |
| Insolvency-led liquidation | IBC, 2016 (after CIRP) | An insolvent company is liquidated after the resolution process fails | Ordered by the NCLT at the end of the insolvency process |
What is the Winding Up of a Company?
Winding up of a company is the legal process that brings a company’s existence to an end. The company sells its assets, pays its creditors, and distributes any remaining surplus to shareholders based on their shareholding. Section 2(94A) of the Companies Act, 2013, defines winding up as “winding up under this Act or liquidation under the Insolvency and Bankruptcy Code, 2016, as applicable.”
Since the IBC came into force in 2016, the Companies Act and IBC jointly govern winding up of a company. The Companies Act, 2013 governs compulsory winding up by the Tribunal under Section 271. The IBC governs the voluntary liquidation of solvent companies under Section 59, and the liquidation of defaulting companies through the Corporate Insolvency Resolution Process (CIRP).
Throughout this process, the company continues to exist as a legal entity until it is formally dissolved. The difference between winding up and dissolution of a company explains where one ends and the other begins.
Detailed Explanation of Different Modes of Winding Up of a Company
The three types of winding up of a company differ by trigger, governing law, and who controls the process:
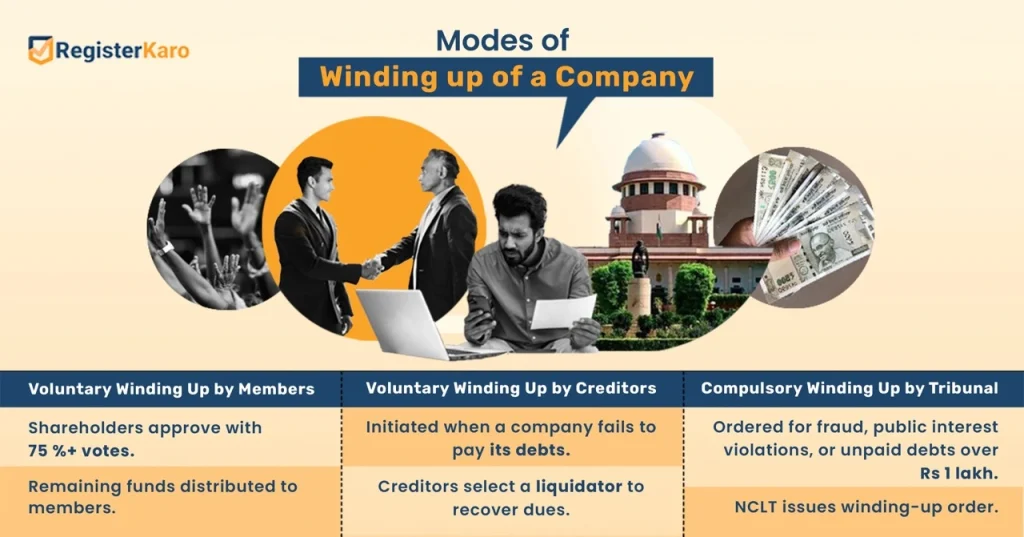
1. Voluntary Liquidation (Section 59, IBC, 2016)
Voluntary liquidation applies to a company that has not defaulted and can pay its debts in full, but chooses to close, often after completing its objectives or on promoter retirement. Section 59 of the IBC and the IBBI (Voluntary Liquidation Process) Regulations, 2017 govern this route.
The voluntary liquidation process involves these steps:
- A majority of directors file a Declaration of Solvency with an affidavit, audited financials for the last two years, and a registered valuer’s report.
- Members pass a special resolution within four weeks of the declaration and appoint an IBBI-registered insolvency professional as liquidator.
- Creditors holding two-thirds of the debt in value approve the resolution within seven days of its passing, where the company owes any debt.
- The liquidator realizes assets, settles claims, and distributes the surplus to members.
- The liquidator files the final report and applies to the NCLT for dissolution.
The liquidator must complete the process within 270 days of commencement where creditors approved the resolution, and within 90 days in all other cases. If the liquidator misses the deadline, they must hold a contributories’ meeting and file a status report with the IBBI.
Note: A company can also exit voluntary liquidation before dissolution. Under Section 59(5A) of the IBC, inserted by the IBC (Amendment) Act, 2026, the company may terminate the process and resume business by passing a special resolution of its members and obtaining creditors’ approval. Regulation 42 of the IBBI (Voluntary Liquidation Process) Regulations, 2017, sets out the procedure, effective from 1 June 2026.
2. Liquidation Following Insolvency (CIRP under the IBC, 2016)
Creditors can no longer file a winding-up petition under the Companies Act, 2013. A creditor must instead start CIRP under Section 7 or 9 of the IBC, and the company itself can file under Section 10. A CIRP application needs a default of at least ₹1 crore.
Process to follow:
- A financial creditor, operational creditor, or the company itself files an application before the NCLT after a payment default.
- The NCLT admits the application and appoints a resolution professional.
- The resolution professional attempts to revive the company through a resolution plan.
- If no viable resolution emerges, the NCLT orders liquidation under Section 33 of the IBC.
- The liquidator sells assets and distributes proceeds according to statutory priority under Section 53 of the IBC.
CIRP must ordinarily finish within 180 days, extendable once by 90 days, with an outer limit of 330 days including litigation delays. However, the Supreme Court in Essar Steel v. Satish Kumar Gupta (2019) allowed the NCLT to extend this in exceptional cases.
Key Changes Under the IBC (Amendment) Act, 2026
The Insolvency and Bankruptcy Code (Amendment) Act, 2026 received Presidential assent on 6 April 2026. The Central Government brought specified provisions into force from 26 May 2026 through S.O. 2625(E) dated 22 May 2026. The amendments shorten liquidation timelines and increase creditor involvement, while provisions on creditor-initiated insolvency and group insolvency await notification by the Central Government. Its key changes include:
- Setting strict timelines: The NCLT must admit or reject a CIRP application within 14 days and pass a liquidation order within 30 days under Section 33(2A).
- Giving creditors greater control: The Committee of Creditors can supervise liquidation under Section 21(11), seek restoration under Section 33(1A) and replace the liquidator with a 66% vote, subject to NCLT approval under Section 34A.
- Introducing CIIRP: The Creditor-Initiated Insolvency Resolution Process will apply only after the Central Government notifies the eligible classes of companies and financial creditors under Sections 58A and 58K. It is therefore not yet operational.
3. Compulsory Winding Up by the Tribunal (Section 271, Companies Act, 2013)
Section 271 of the Companies Act, 2013, allows the NCLT to wind up a company on specific legal and public-interest grounds. The NCLT may order winding up if:
- The company passes a special resolution seeking winding up by the Tribunal.
- The company acts against the sovereignty and integrity of India, state security, public order, decency, or morality.
- The company acts against friendly relations with foreign states.
- The Tribunal finds that the company’s affairs were conducted fraudulently or for an unlawful purpose.
- The company fails to file financial statements or annual returns for the immediately preceding five consecutive financial years.
- The Tribunal considers it just and equitable to wind up the company.
Steps taken by the NCLT:
- An eligible party, such as the company, a contributory, or the Registrar, files a petition in Form WIN-1 or WIN-2.
- The Tribunal examines the grounds under Section 271.
- If satisfied, the Tribunal passes a winding-up order and appoints the Official Liquidator or a liquidator from the panel of insolvency professionals.
- The liquidator takes control of the company’s affairs, settles claims, and completes the dissolution process.
Compulsory winding up has no fixed statutory timeline. Under Section 281, the Company Liquidator must report to the NCLT within 60 days of the winding-up order.
Note: Members’ voluntary winding up, creditors’ voluntary winding up and winding up under Tribunal supervision are no longer applicable modes under Section 270. The IBC omitted Sections 304–323 of the Companies Act, 2013 and moved voluntary liquidation to Section 59 of the IBC. An insolvent company now goes through CIRP instead of creditors’ voluntary winding up. Section 270 currently covers only winding up by the Tribunal.
Strike-Off of a Company: An Alternative to Winding Up
Not every company needs to undergo winding up or liquidation. Companies that have stopped operations and have no assets, liabilities, or pending litigation can apply for strike-off under Section 248 of the Companies Act, 2013.
According to MCA data, the Centre for Processing Accelerated Corporate Exit (C-PACE) processes voluntary company closure applications (Form STK-2) within an average of two months.
By filing Form STK-2, the company can request the Registrar to remove its name from the register of companies. Applications are processed through C-PACE (Centre for Processing Accelerated Corporate Exit), making strike-off the fastest and most cost-effective route for closing a defunct company.
Modes of Winding Up of an LLP
A Limited Liability Partnership can be wound up in two main ways, with a third route available to solvent LLPs:
- Voluntary strike-off (LLP Form 24): An LLP that has stopped carrying on business and cleared its liabilities can apply for LLP strike off by filing LLP Form 24 with the Registrar. Since 27 August 2024, these applications are processed centrally through the C-PACE (Centre for Processing Accelerated Corporate Exit).
- Winding up by the Tribunal: The National Company Law Tribunal can order winding up under the Limited Liability Partnership Act, 2008, and the applicable rules. For example, where the LLP is unable to pay its debts or acts against the national interest.
- Voluntary liquidation under the IBC: A solvent LLP can also opt for voluntary liquidation under the Insolvency and Bankruptcy Code framework, where it can pay its debts in full.
In short, choosing the right process for the winding up of an LLP depends on whether it is solvent and whether all liabilities have been settled, so founders should confirm their status before filing.
Note: The main difference between strike-off and winding up of a company is their scope. While strike-off removes an eligible company’s name from the register without the full liquidation process, winding up involves liquidating assets, paying creditors, and distributing any surplus before dissolution.
Timeline for Winding Up a Company Via Different Modes
The time required to close a company depends on the closure route/modes, regulatory clearances, and the company’s financial position.
| Mode of closure | Typical timeline |
| Strike-off (defunct companies) | Around 3–6 months, with some cases moving faster through C-PACE |
| Voluntary liquidation | 90 days, or 270 days where creditors approved the resolution |
| Insolvency-led liquidation (after CIRP) | CIRP of 180 to 330 days, then liquidation targeted at 180 days plus a 90-day extension |
| Compulsory winding up by the Tribunal | Compulsory winding up has no fixed statutory timeline and depends on the complexity of the case. Under Section 281, the liquidator must submit a report on the company’s affairs to the Tribunal within 60 days of the winding-up order |
Note: Pending income-tax or GST assessments, creditor disputes, and complex asset realization are common reasons for liquidation to exceed these timelines. A company with no assets, liabilities, or pending compliance issues will generally have a simpler and faster exit through strike-off than through formal liquidation.
Consequences of Winding Up a Company
The closure process triggers significant legal, financial, and operational effects for all parties involved. Winding up affects the company, its employees, and its investors in the following ways:
1. Immediate Legal Effects
- The company stops its business, except for what the liquidator needs for a beneficial winding up.
- The company loses legal authority to sign new contracts.
- Existing contracts might end automatically unless liquidators decide otherwise.
- Directors lose decision-making powers completely.
- Liquidators take full control of the company’s affairs.
- The NCLT orders dissolution in liquidation and Tribunal winding up, while the Registrar dissolves a company only in strike-off.
2. Financial Impact on Employees and Stakeholders
- Provident fund, pension fund, and gratuity fund amounts stay outside the liquidation estate under Section 36(4) of the IBC.
- Unpaid employee wages rank ahead of unsecured creditors under Section 53 of the IBC.
- Companies process gratuity and PF settlements before other payments.
- Investors risk losing their entire investment in the company.
- Shareholders receive money only after clearing all creditor dues.
- Final payouts depend entirely on surplus availability after debt clearance.
Best Practices for Smooth Winding Up of a Company
The following practices help a company complete the winding up process smoothly and in compliance with the law.
- Plan before commencement: Review all assets, liabilities, contracts, and outstanding obligations before you initiate winding up. Engage a qualified professional to confirm that each step meets the requirements of the Companies Act, 2013, and the IBC, 2016.
- Prepare the documentation: Obtain board approval and shareholder consent before starting the process. Ensure that every document, from resolutions to financial statements, is accurate and filed within its deadline.
- Communicate with stakeholders: Inform creditors, employees, shareholders, and customers about the proposed closure. Provide regular updates so that every stakeholder stays aware of the progress.
- Manage and distribute assets correctly: Sell the company’s assets fairly and settle debts in the order of priority set by law. Distribute any surplus to shareholders only after the company clears all creditor dues.
- Control risk and keep records: Follow each legal step to limit personal liability for the directors. Maintain complete records of every decision and filing made during the process.
