


Government banks in India, also called Public Sector Banks (PSBs), are institutions where the government holds a majority stake, usually over 50%. There are 12 major PSBs operating today. They hold a significant share of the country’s deposits and credit.
In FY 2025–26, PSBs posted a record combined net profit of ₹1.98 lakh crore. This was up 11.2% year-on-year. It marked their fourth consecutive year of profitability. Aggregate business crossed ₹283.3 lakh crore.
PSBs drive financial inclusion and support small businesses and farmers. These banks also deliver welfare schemes directly to citizens’ doorsteps. They play a central role in executing many government schemes for startups in India. Through these initiatives, entrepreneurs can access credit and financial inclusion benefits.
Key Takeaways
- India has 12 Public Sector Banks after the 2019–2020 consolidation, down from 27.
- PSBs posted a record ₹1.98 lakh crore combined net profit in FY26, with Gross NPA falling to a historic low of 1.93% and Net NPA to 0.39%.
- PM Jan Dhan Yojana has crossed 58.84 crore beneficiary accounts as of 2026, far surpassing earlier milestones.
- SBI remains the largest PSB by every major metric, with a market capitalization of roughly ₹9.99 lakh crore as of August 2026.
- PSBs implement most major financial inclusion schemes, including Jan Dhan Yojana, Mudra Loans, Kisan Credit Cards, and Atal Pension Yojana.
- Despite strong recent performance, PSBs still face challenges around legacy systems, political interference, and competition from faster-moving private banks.
What are Government Banks in India?
Government banks in India are those in which the government holds a majority stake, usually over 50%. This gives them stability, credibility, and a mandate to serve the public interest. They provide savings and current accounts, loans, and digital banking services. They also implement government schemes like the Kisan Credit Card and the PM Jan Dhan Yojana.
Here’s how government banks in India have grown and transformed over the years:
- Early Nationalization (1955): The Imperial Bank of India was nationalized and renamed the State Bank of India (SBI).
- First Phase (1969): The government nationalized 14 major commercial banks, like Canara Bank and Bank of Baroda. This was done to increase access to banking.
- Second Phase (1980): Six more banks came under government ownership. This helped expand their reach.
- Recent Mergers/Consolidations: Several PSBs have merged to improve efficiency and reduce duplication. Examples include the merging of Punjab National Bank with Oriental Bank and United Bank, and SBI with its associate banks.
In FY 2025–26, PSBs’ total business grew 12.8% year-on-year to ₹283.3 lakh crore. Gross advances rose 15.7% to ₹127 lakh crore, while deposits grew 10.6% to ₹156.3 lakh crore. Credit growth remained broad-based across Retail (18.1%), Agriculture (15.5%), and MSME (18.2%) segments. This underscores the continued role PSBs play in financial inclusion and rural India.
They are also crucial in implementing government schemes like Jan Dhan Yojana, Mudra Loans, and Kisan Credit Cards.
Services Offered by Government Banks
Government banks provide a wide range of services for individuals, businesses, and government programs.
- Savings & Current Accounts: Easy-to-open accounts with low minimum balance requirements.
- Loans & Advances: Personal loans, business loans, agricultural loans, education loans, and housing loans.
- Deposits & Investments: Fixed deposits, recurring deposits, government bonds, and pension schemes.
- Digital & Mobile Banking: Online fund transfers, bill payments, UPI transactions, mobile wallets, and app-based banking.
- Government Transactions: Salary accounts, pensions, subsidies, and direct benefit transfers.
- International Banking Services: Foreign exchange, remittances, and overseas account services (available in select PSBs).
- Customer Support Services: 24/7 helplines, grievance redressal, and in-branch assistance.
Government banks combine traditional banking, modern digital solutions, and government-backed services to serve every segment of society.
Challenges Faced by Government Banks
Government banks play a key role in India’s economy, but they face several challenges:
- Non-Performing Assets (NPAs) / Credit Risk: Though NPAs have fallen to record lows, agriculture and MSME lending still carries elevated risk relative to other segments.
- Governance Issues / Political Interference: Decision-making can be influenced by political priorities.
- Slow Decision-Making: Bureaucratic processes can delay approvals and policy changes.
- Legacy Systems / Need for Modernization: Older technology slows operations; tech adoption is essential.
- Competition from Private and Foreign Banks: Faster services, advanced apps, and global standards attract customers.
- Operational Inefficiencies: Large workforce and complex hierarchies reduce efficiency.
- Limited Flexibility: Focus on social objectives sometimes limits profit-driven agility.
- Digital Adoption Challenges: Rural areas and older customers may struggle with online banking.
- Interest Rate Pressures: Government-mandated priority sector lending and low-interest schemes can reduce profits.
- Regulatory Compliance: Continuous RBI and government updates increase operational burden.
- Brand Perception: Some customers perceive PSBs as slower or less customer-friendly.
- Cybersecurity Threats: Growing digital banking usage increases vulnerability to attacks.
- Rural Infrastructure Limitations: Poor connectivity and low financial literacy slow adoption.
- Capital-Raising Requirements: PSBs raised ₹50,551 crore in FY26 alone to support growth and strengthen capital ratios.
Despite these challenges, government banks remain essential, supporting financial inclusion, economic growth, and national schemes across India.
Detailed Government Bank List in India
There are 12 major Public Sector Banks in India after recent mergers. Here’s a list of public sector banks in India:
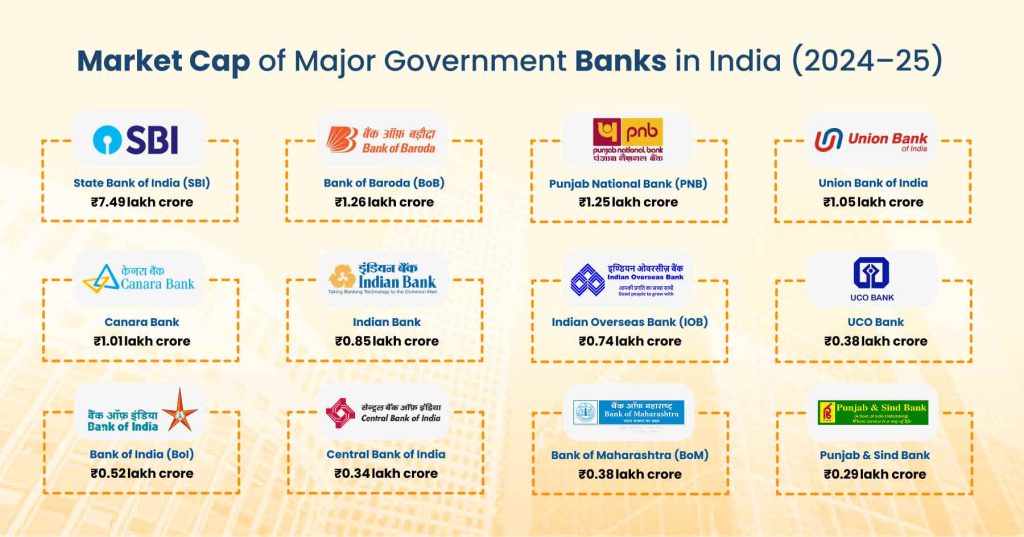
| Bank Name | Founded | Headquarters | Key Features |
|---|---|---|---|
| State Bank of India (SBI) | 1955 (from Imperial Bank) | Mumbai | Largest bank in India, pan-India presence, digital banking via YONO, priority sector lending; merged with 5 associate banks & Bharatiya Mahila Bank |
| Bank of Baroda (BoB) | 1908 | Vadodara, Gujarat | Strong international presence, retail & corporate banking; merged with Dena Bank & Vijaya Bank |
| Punjab National Bank (PNB) | 1894 | New Delhi | Wide branch network, strong rural reach; merged with Oriental Bank & United Bank |
| Union Bank of India | 1919 | Mumbai | Focus on MSMEs, digital banking; merged with Andhra Bank & Corporation Bank |
| Canara Bank | 1906 | Bengaluru | Strong retail presence, priority sector loans, digital services; no recent merger |
| Indian Bank | 1907 | Chennai | Urban & semi-urban focus, government scheme support; merged with Allahabad Bank |
| Indian Overseas Bank (IOB) | 1937 | Chennai | Southern India presence, international branches, retail & corporate banking; no recent merger |
| UCO Bank | 1943 | Kolkata | Eastern India focus, retail & corporate banking; no recent merger |
| Bank of India (BoI) | 1906 | Mumbai | International operations, priority sector lending; no recent merger |
| Central Bank of India | 1911 | Mumbai | One of the oldest PSBs, strong rural reach, government schemes; no recent merger |
| Bank of Maharashtra (BoM) | 1935 | Pune | Maharashtra & nearby states focus, rural banking, MSME support; no recent merger |
| Punjab & Sind Bank | 1908 | New Delhi | Northern India focus, MSME lending, digital banking adoption; no recent merger |
Key Features of Government Banks
Government banks in India offer stability, trust, and wide access. They serve millions across urban and rural areas. Some of the key government bank features include:
- Government Ownership: The government holds a majority stake, ensuring reliability and credibility.
- Pan-India Reach: Branches and ATMs cover cities, towns, and villages.
- Financial Inclusion: They provide loans to farmers, small businesses, and underserved communities.
- Digital Banking: Mobile apps, net banking, UPI, and SBI platforms like YONO make banking easy.
- Secure Deposits: Government backing protects savings and investments.
- Support for Government Schemes: They implement PM Jan Dhan Yojana, Mudra Loans, Kisan Credit Cards, and Atal Pension Yojana.
- Priority Lending: They focus on agriculture, MSMEs, and other priority sectors.
Government banks combine trust, reach, and social responsibility with modern banking solutions.
Major Government Schemes Implemented Through Government Banks
Public Sector Banks play a crucial role in implementing government schemes across India. They help reach every citizen, boost financial inclusion, and support economic growth.
- PM Jan Dhan Yojana (PMJDY): PSBs open zero-balance accounts for the unbanked, ensuring access to savings, insurance, and direct benefit transfers. The scheme has crossed 58.84 crore beneficiary accounts, with total balances exceeding ₹3.1 lakh crore.
- Pradhan Mantri Mudra Yojana (PMMY): Banks provide loans to micro and small enterprises, helping entrepreneurs start or expand businesses. Cumulative sanctions have crossed ₹41 lakh crore across roughly 59 crore loans.
- Kisan Credit Card (KCC): Farmers receive timely credit for agriculture needs, inputs, and equipment. PSBs enable easy access and flexible repayment.
- Atal Pension Yojana (APY): PSBs enroll workers in a government-backed pension scheme, promoting long-term financial security, with over 9 crore cumulative enrolments.
- Stand-Up India Scheme: Banks facilitate loans for women and SC/ST entrepreneurs, promoting entrepreneurship and inclusive growth.
- Direct Benefit Transfers (DBT): PSBs channel subsidies, pensions, and welfare payments directly to beneficiaries’ accounts, reducing leakages and delays.
- National Social Security Schemes: PSBs support schemes like Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) for workers’ social security.
Government banks act as critical links between the government and citizens, ensuring schemes are accessible, transparent, and effective. Their extensive branch network, digital platforms, and rural presence make implementation efficient and inclusive.
Government Banks vs Private Banks vs Cooperative Banks
Public Sector Banks differ from private and cooperative banks in ownership, reach, and focus. Here’s a clear comparison:
| Feature | Public Sector Banks (PSBs) | Private Banks | Cooperative Banks |
|---|---|---|---|
| Ownership | Majority government stake (>50%) | Owned by private companies or individuals | Owned by members of a cooperative society |
| Reach | Pan-India, urban & rural | Mostly urban & semi-urban | Local or regional |
| Focus | Financial inclusion, government schemes, and social responsibility | Profit, technology, customer experience | Serve local communities and small businesses |
| Trust & Stability | High (government-backed) | Moderate, relies on reputation | Moderate, community-backed |
| Digital Banking | Growing rapidly, government-supported apps | Advanced, tech-driven | Limited digital services |
| Loan & Credit Access | Priority sector lending, rural credit | Urban and profitable segments | Local business and member loans |
Latest Developments in Government Banks (2024–25)
Some developments driving strategic growth and performance in government banks include:
- Record Profits: PSBs posted an all-time high combined net profit of ₹1.98 lakh crore in FY26, up 11.2% year-on-year. This marked the fourth consecutive year of profitability.
- Historic Asset Quality Improvement: Gross NPA fell to a record-low 1.93% and Net NPA to 0.39% as of March 2026. Provisioning coverage stayed above 90% across every PSB.
- Stronger Capital Position: Aggregate CRAR improved to 16.6%. This was supported by ₹50,551 crore raised during FY26.
- Broad-Based Credit Growth: Retail advances grew 18.1%, agriculture advances rose 15.5%, and MSME lending increased 18.2% during the year.
- SBI’s Record Year: SBI posted its highest-ever annual net profit of ₹80,032 crore in FY26, up 12.9% year-on-year. Its market capitalization stood at roughly ₹9.99 lakh crore as of August 2026.
- Consolidation Momentum: Industry watchers expect further PSB consolidation to continue. The government is pushing for fewer, larger, globally competitive banks under its Viksit Bharat 2047 vision.
These developments highlight strong financial performance, improved efficiency, and better governance in government banks. However, as with all bank-specific figures, always check current quarterly results before relying on any single data point.
The Future of Government Banks in India
Government banks are rapidly modernizing to meet customer needs and support India’s economy.
- Digital-First Banking & AI: PSBs roll out mobile apps, UPI services, AI chatbots, and platforms like SBI YONO. AI improves fraud detection, credit scoring, and customer support.
- Fintech Collaborations: PSBs partner with fintechs to speed up payments, loans, and digital services for urban and rural users.
- Rural Expansion & Inclusion: PSBs expand rural banking, supporting PM Jan Dhan, Mudra Loans, and Kisan Credit Cards. By 2030, most villages may have full access to formal banking.
- Priority Sector & ESG Lending: Banks focus on agriculture, MSMEs, renewable energy, and sustainable projects, supporting climate goals.
- Cybersecurity Enhancements: PSBs strengthen systems to secure digital transactions.
- Global Expansion: SBI, BoB, and PNB grow overseas, serving NRIs, trade finance, and global clients.
- Customer-Centric Innovation: Personalized loans, digital wealth tools, and AI-driven advice improve banking experiences.
Government banks are set to remain pillars of India’s economy, driving modernization, sustainability, and inclusive growth by 2030.
How to Choose the Right Government Bank for You?
Choosing the right government bank depends on your needs, convenience, and services. Here’s how to decide:
- Evaluate Branch & ATM Access: Pick a bank with branches and ATMs near your home, office, or rural area. Convenience saves time.
- Check Services Offered: Consider what you need, savings accounts, loans, digital banking, or government schemes.
- Look at Digital Capabilities: Banks with strong mobile apps, UPI integration, and online services make transactions faster and easier.
- Compare Interest Rates: Check savings, fixed deposit, and loan interest rates to get better returns or lower borrowing costs.
- Consider Customer Support: Responsive support, grievance redressal, and helplines improve the banking experience.
- Review Reputation & Stability: Choose banks with strong credit ratings, good financial performance, and government backing.
- Specialized Services: Some banks focus on agriculture, MSMEs, startup support, or NRI services. Choosing a bank that actively participates in government grants for startups can make it easier for new businesses to secure funding and scale faster.
- Scheme Accessibility: If you plan to use government schemes, ensure the bank actively supports them.
By assessing your requirements and comparing options, you can choose a government bank that balances convenience, trust, and financial benefits.
