Income Tax Return Filing for Partnership Firms
Ensure timely and accurate ITR filing for your partnership firm with expert guidance on ITR-5, audits, capital accounts, and compliance—RegisterKaro simplifies the entire process.
 Filing Support for ITR-5 FormCapital Account & Profit Distribution ReviewBookkeeping & Statutory Audit AssistanceFull Compliance with Income Tax Act, 1961Dedicated Help from Experienced Tax Experts


 What Sets Us ApartWhat Sets Us Apart
What is a Partnership Firm Tax Return Filing?
Tax return filing for a partnership firm includes submitting the Income Tax Return (ITR-5) to the Income Tax Department of India. Regardless of whether the firm is registered or unregistered, every partnership firm is required to report its income, expenses, and tax liabilities annually. The return must be filed even if the firm has incurred losses or has no taxable income during the financial year.
Filing ensures annual compliance with the Income Tax Act, 2025, and is essential for claiming refunds, carrying forward losses, or maintaining proper financial records. Additionally, if the firm’s turnover exceeds the specified threshold limits, tax audit provisions under Section 44AB may also apply.
These firms primarily fall into two categories:
1. Registered Partnership Firm
A registered partnership firm has completed the formal registration process with the Registrar of Firms under the Indian Partnership Act, 1932, and possesses a registration certificate as proof of its legal standing.
2. Unregistered Partnership Firm
Conversely, an unregistered partnership firm is one that has not obtained a registration certificate from the Registrar of Firms.
At its core, a partnership is an agreement between two or more individuals who have mutually agreed to share the profits or losses generated from a jointly operated business. The individuals in this arrangement are known as 'partners,' and together they form the 'firm'.
Partners must understand the partnership firm tax rate and its implications for profit distribution.
Which ITR Form to Use for a Partnership Firm?
A partnership firm generally files its income tax return using ITR-5 through the Income Tax Department’s e-filing portal. Eligible resident partnership firms, other than LLPs, may use ITR-4 if they meet the prescribed conditions for presumptive taxation under Sections 44AD, 44ADA, or 44AE. Individual partners must file their own income tax returns separately.
Presumptive Taxation for Partnership Firms
Eligible resident partnership firms, other than LLPs, can opt for presumptive taxation under Section 44AD for eligible businesses or Section 44ADA for specified professions. Under Section 44AD, the firm generally declares 8% of turnover or gross receipts as income, or 6% of qualifying digital receipts. The turnover limit is ₹2 crore, increasing to ₹3 crore when cash receipts do not exceed 5% of total turnover.
Under Section 44ADA, eligible professionals generally declare 50% of gross receipts as income. The limit is ₹50 lakh, increasing to ₹75 lakh when cash receipts do not exceed 5% of total receipts. These schemes can remove the tax audit requirement when the firm meets the applicable conditions. However, declaring income below the prescribed rate may trigger bookkeeping and audit requirements.
For Tax Year 2026–27 onward, Section 58 of the Income-tax Act, 2025, consolidates the presumptive taxation provisions.
How is a Partnership Firm Treated Under the Income Tax Act, 2025?
For income-tax purposes, a partnership firm pays tax on its taxable income at a flat rate of 30%. A partner’s share of the firm’s profit is exempt from tax in the partner’s hands under Section 10(2A) of the Income-tax Act, 1961, as the firm has already paid tax on that profit. However, interest on capital and remuneration received from the firm are generally taxable as business income, and each partner must report these amounts in their individual income tax return.
The main tax provisions applicable to a partnership firm include:
- Income tax: A partnership firm generally pays tax at 30% of its taxable income.
- Surcharge: A 12% surcharge applies when the firm’s total income exceeds ₹1 crore, subject to applicable marginal relief.
- Health and Education Cess: A 4% cess applies to the income tax and surcharge, where applicable.
- Interest on partners’ capital: The firm may claim a deduction for interest paid to partners if the partnership deed authorizes the payment and the firm meets the applicable conditions. Under Section 35(e)(iv) of the Income-tax Act, 2025, the deductible interest is capped at 12% simple interest per annum.
- Partner remuneration: Salary, bonus, commission, or other remuneration paid to working partners may qualify for a deduction if the partnership deed authorizes the payment and the firm meets the prescribed conditions and limits under Section 35(e)(iii) of the Income-tax Act, 2025.
A partnership firm remains taxable under the applicable income-tax provisions even if it is unregistered under the Indian Partnership Act, 1932.
A firm may also be liable for Alternate Minimum Tax (AMT) when the applicable conditions are met. The rules governing AMT depend on the tax year. For periods governed by the Income-tax Act, 1961, Section 115JC provides for AMT, generally at 18.5% of adjusted total income, subject to applicable provisions. For Tax Year 2026–27 onward, the corresponding provisions under the Income-tax Act, 2025, should be applied.
Documents Required to File a Partnership Firm’s ITR
Keep these documents and details ready before preparing the firm’s income tax return:
- PAN and partnership deed: The firm’s PAN and the deed showing the partners, profit-sharing ratio, and terms for interest or remuneration.
- Financial statements: Profit and loss account, balance sheet, and books of account, where maintained.
- Bank statements and expense records: Bank transactions, sales and purchase records, business expenses, invoices, and depreciation details.
- Partner payment details: Capital account statements and records of interest, remuneration, salary, bonus, or commission paid to partners.
- Tax records: Form 26AS, Annual Information Statement (AIS), TDS details, advance tax and self-assessment tax challans.
- Audit and presumptive-tax records, where applicable: Tax audit report and related details, or records supporting income declared under the presumptive taxation scheme.
ITR forms are generally attachment-less, so the firm does not usually upload these supporting documents with the return. It should retain them in case the Income Tax Department requests them during assessment or verification.
How to File an Income Tax Return for a Partnership Firm?
To file your partnership firm’s income tax return, prepare the financial records, calculate taxable income, complete ITR-5, submit it through the Income Tax Department’s e-filing portal, and verify the return using an approved method.
The filing process generally involves these steps:
- Prepare the financial information: Compile the firm’s books of account, income, expenses, partner payments, investments, Tax Deducted at Source (TDS) details, and other relevant tax information.
- Calculate taxable income: Apply eligible deductions, disallowances, depreciation, and other applicable provisions to determine the firm’s taxable income.
- Complete ITR-5: Enter the firm’s business, income, tax, partner, and other required details in the applicable schedules.
- File the return electronically: Submit ITR-5 through the Income Tax Department’s e-filing portal using the applicable authentication method.
- Complete verification: Verify the return through the method permitted for the firm. A firm required to file its return using a Digital Signature Certificate must complete the verification through DSC.
A partnership firm generally does not attach supporting documents to ITR-5 at the time of filing. However, it should retain books, invoices, bank records, tax statements, partnership documents, and other supporting evidence because the Income Tax Department may request them during assessment or verification.
Where the firm is subject to a tax audit, it must also comply with the applicable audit-report filing requirements within the prescribed timelines.
What is the Cost of Filing a Partnership Tax Return?
The cost of filing a partnership firm’s income tax return depends on the complexity of its accounts, transaction volume, and whether a tax audit is required. The following table provides estimated professional fees based on published service prices and market estimates:
| Filing Type | Estimated Cost |
| Self-filing through the Income Tax Department portal | ₹0 in government filing fees |
| Professional ITR filing without a tax audit | ₹3,000–₹10,000 |
| ITR filing with a tax audit | ₹15,000–₹50,000 or more |
| Complex returns requiring additional accounting, reconciliation, or tax advisory | Depends on the scope of services |
Note: These amounts are indicative of professional fees, not government-prescribed rates. The final cost may vary with the firm’s financial records, transaction volume, audit requirements, and additional services. Confirm whether the quoted fee includes tax computation, financial statement preparation, audit work, and notice support.
Deductions and Allowances for Partnership Firms
A partnership firm can deduct eligible business expenses and certain payments to partners when calculating taxable income. The firm must meet the applicable tax rules and maintain supporting records.
Interest and Remuneration Paid to Partners
A firm can claim deductions for partner payments when it meets the applicable conditions:
- Interest on capital: Interest paid to partners is generally deductible up to 12% simple interest per annum, subject to the partnership deed and applicable tax rules.
- Remuneration to working partners: Salary, bonus, commission, or other remuneration may qualify for deduction within statutory limits. The partnership deed must authorize the payment.
- Payments to non-working partners: The firm cannot deduct remuneration paid to partners who do not actively participate in its business or profession.
TDS on Payments to Partners Under Section 194T
Under Section 194T of the Income-tax Act, 1961, a partnership firm must deduct TDS at 10% on salary, remuneration, commission, bonus, and interest paid or credited to a partner when the aggregate amount exceeds ₹20,000 during the financial year. The firm must deduct TDS when it credits the amount to the partner’s account, including the capital account, or makes the payment, whichever occurs first.
For Tax Year 2026–27 onward, the corresponding provision appears under Section 393 of the Income-tax Act, 2025.
Other Deductible Business Expenses
A partnership firm can generally deduct expenses incurred wholly and exclusively for its business, subject to applicable tax provisions. These may include business rent, employee salaries, loan interest, repairs, insurance, professional fees, utilities, and eligible depreciation. Personal expenses, capital expenditures claimed as revenue expenses, and payments prohibited by law generally do not qualify.
Does Your Partnership Firm Need a Tax Audit?
A partnership firm must generally get its accounts audited under Section 44AB of the Income-tax Act, 1961, if its business turnover exceeds ₹1 crore. The threshold increases to ₹10 crore when both cash receipts and cash payments do not exceed 5% of their respective totals.
Firms using presumptive taxation may qualify for an exemption, subject to the applicable conditions. For Tax Year 2026–27 onward, Section 63 of the Income-tax Act, 2025, governs tax audits.
How to Check a Partnership Firm’s ITR Status?
After filing an Income Tax Return (ITR), a partnership firm can track its status to confirm the Income Tax Department has verified and processed it. The status also shows whether the return requires further action or has resulted in a refund or tax demand.
Case 1: Checking ITR Status Without Login
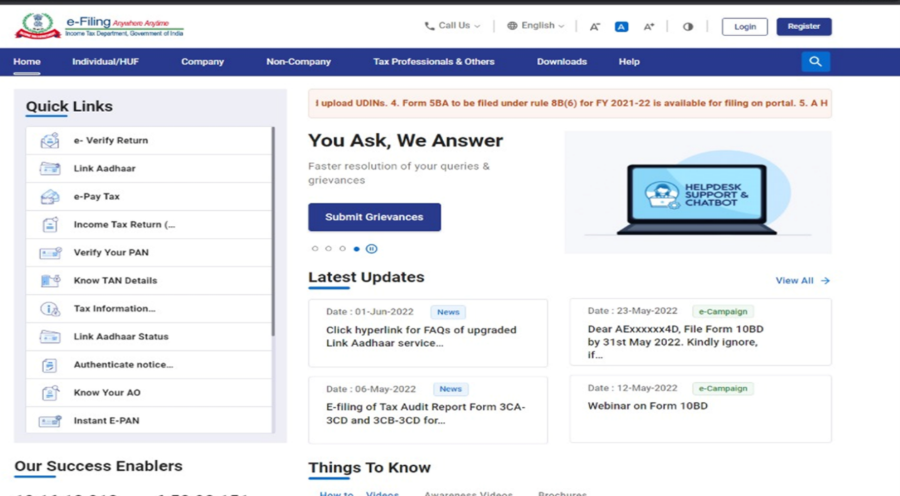
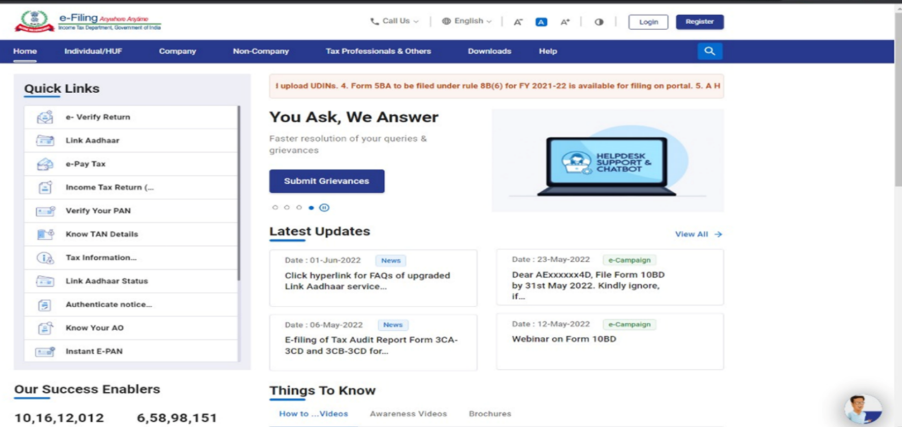
Step 1: Go to the e-Filing portal homepage.
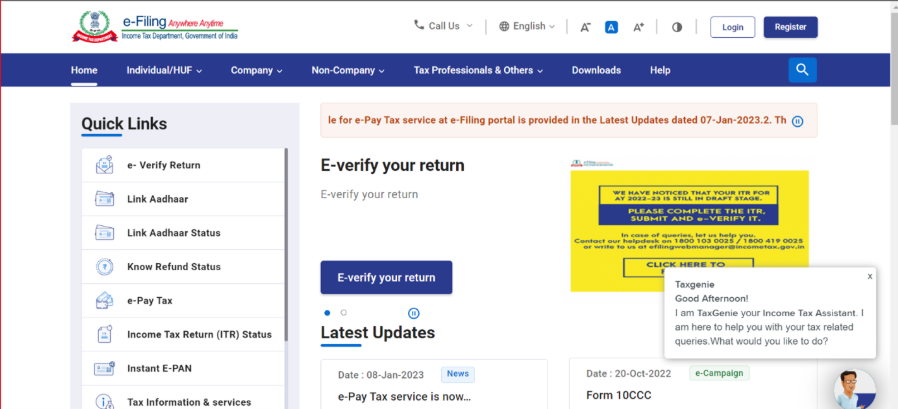
Step 2: Click Income Tax Return (ITR) Status.
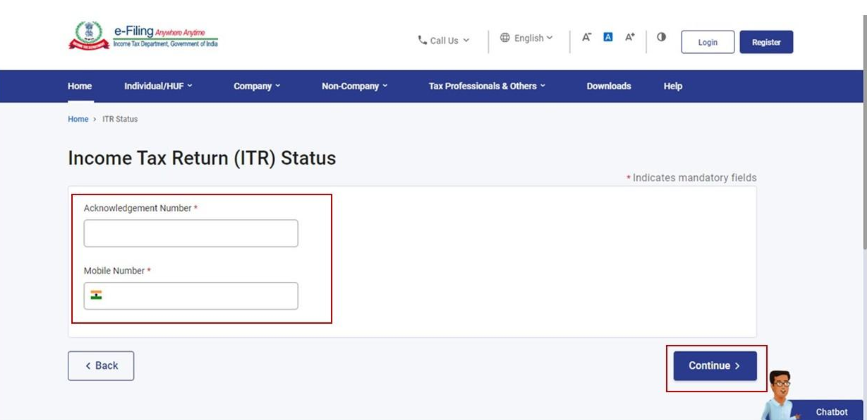
Step 3: On the Income Tax Return (ITR) Status page, enter your acknowledgement number and a valid mobile number, and click Continue.
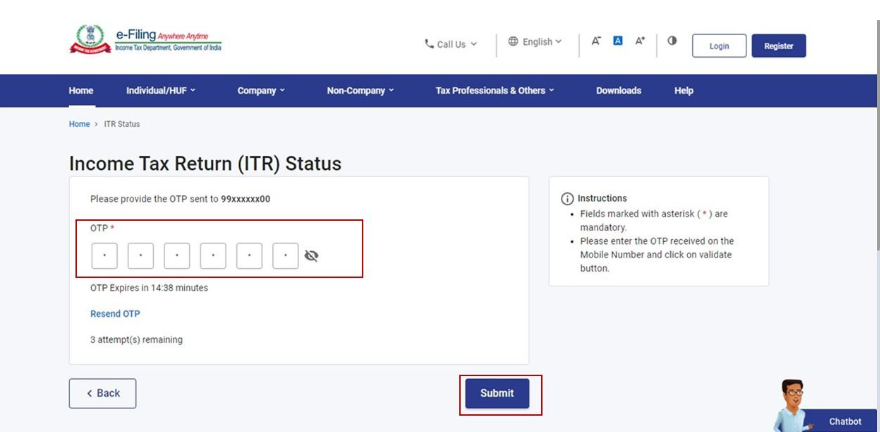
Step 4: Enter the 6-digit OTP received on your mobile number entered in Step 3 and click Submit.
Note:
- The OTP remains valid for 15 minutes.
- The system allows three attempts to enter the correct OTP.
- An on-screen countdown displays the remaining OTP validity.
- Selecting Resend OTP generates and sends a new OTP.
On successful validation, you will be able to view the ITR status.
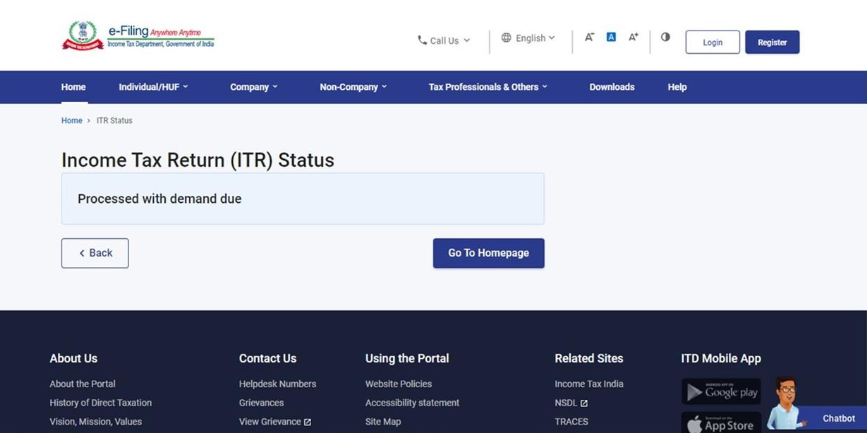
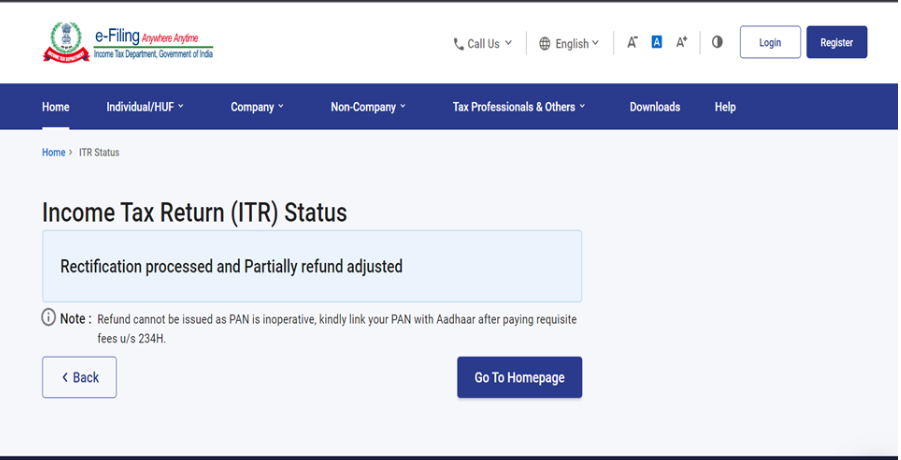
If your PAN is inoperative, a refund cannot be issued. Kindly link your PAN with Aadhaar after paying the requisite fee u/s 234H.
Case 2: Checking ITR Status After Login
Step 1: Log in to the e-Filing portal using your valid user ID and password.
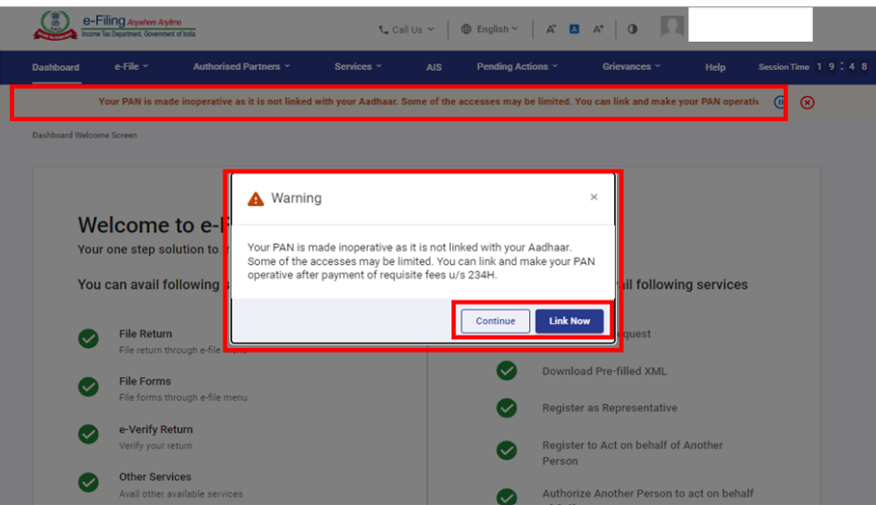
For individual users, if PAN is not linked with Aadhaar, you will see a pop-up message that your PAN is made inoperative as it is not linked with your Aadhaar.
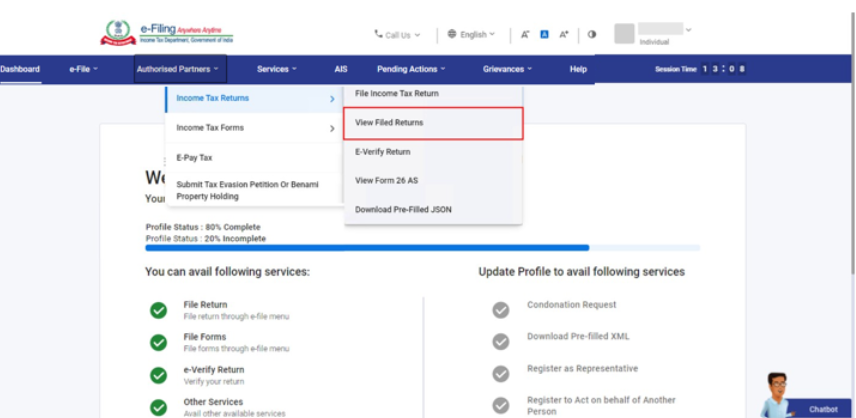
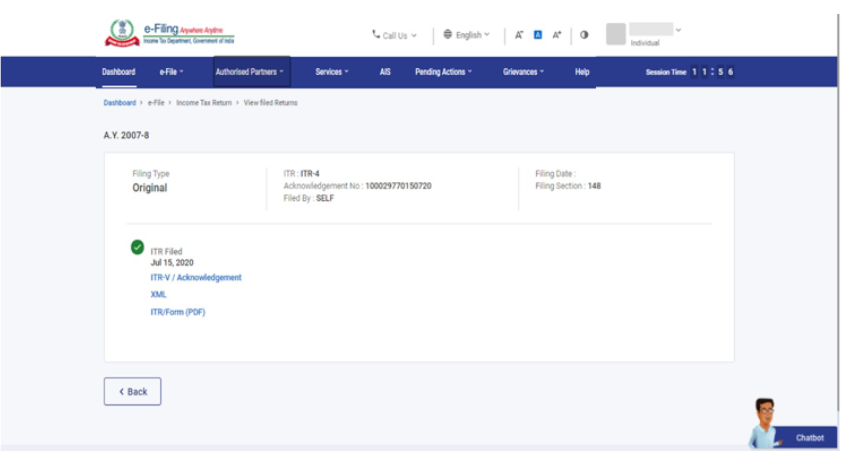
Step 2: Click e-File > Income Tax Returns > View Filed Returns.
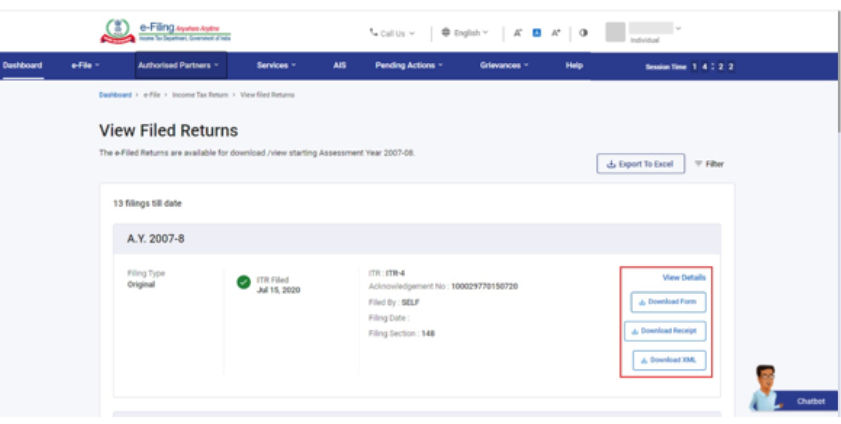
Step 3: On the View Filed Returns page, you will be able to view all the returns filed by you. You will be able to download the ITR-V Acknowledgement, upload JSON (from the offline utility), complete the ITR form in PDF, and the intimation order (by using the options on the right-hand side).
Note:
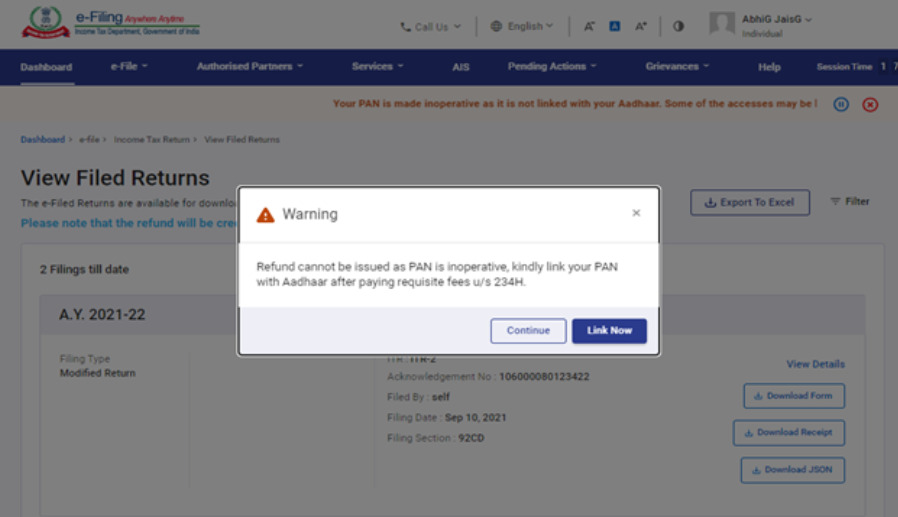
If your PAN is inoperative, you will see a pop-up message that a Refund cannot be issued as your PAN is Inoperative.
Note:
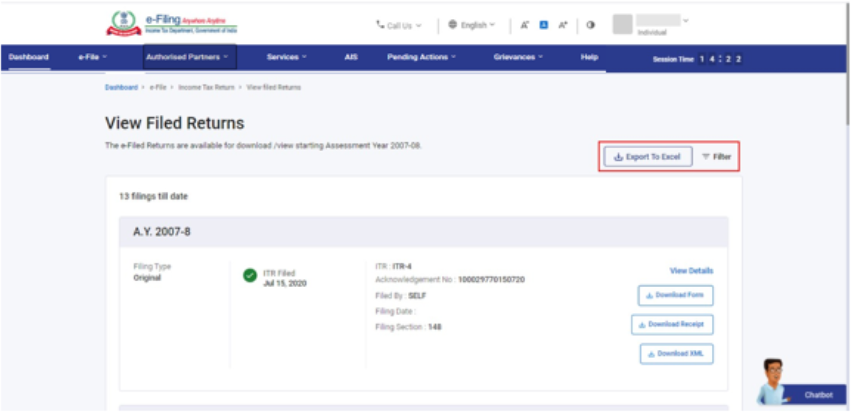
- Click Filter to view your filed returns based on different criteria (AY or Filing Type).
- Click Export to Excel to export your returns data to Excel format.
Click View Details to view the life cycle of the return and action items related to it (e.g., returns pending for e-Verification).
Which Expenses Can a Partnership Firm Claim as Tax Deductions?
A partnership firm can claim eligible business expenses and specified payments as deductions when computing its taxable income. The Income Tax Act also places specific conditions on payments made to partners. Key deductions and limits include:
- Interest on partners’ capital: Interest paid to partners is generally deductible up to 12% per annum, provided the payment meets the conditions under Section 40(b) and the partnership deed authorizes it.
- Business expenses: Expenses incurred wholly and exclusively for the firm’s business can generally be claimed under the applicable provisions, subject to the Act’s requirements.
- Payments covered by specific disallowance rules: The firm cannot claim certain payments or expenses where the Income Tax Act specifically disallows them, including partner payments that do not satisfy the prescribed conditions.
- Remuneration to working partners: Salary, bonus, commission, or other remuneration paid to working partners may qualify for deduction within the prescribed limits. Under Section 40(b) of the Income-tax Act, 1961, the combined deduction for all working partners is capped at 90% of the first ₹6,00,000 of book profit, or ₹3,00,000, whichever is higher, and 60% of the remaining book profit. If the firm incurs a loss, the minimum limit is ₹3,00,000. These limits apply from AY 2025–26. From Tax Year 2026–27 onward, Section 35(e)(iii) of the Income-tax Act, 2025, governs the remuneration limit.
The partnership deed should clearly authorize interest and remuneration payable to partners. The firm should also maintain supporting records for the expenses claimed in its income tax return.
What Should a Partnership Firm Do After Receiving an Income Tax Notice?
An income tax notice does not automatically mean that the partnership firm has violated tax laws. The Income Tax Department may issue a notice to correct a defective return, seek additional information, communicate a tax adjustment, examine the return, or recover an outstanding demand.
The firm should verify the notice, understand the issue, collect the relevant records, and submit a response within the prescribed time. The appropriate action depends on the section mentioned in the notice and the matter raised by the Department.
What is an Income Tax Notice?
An income tax notice is an official communication that asks a partnership firm to provide information, correct a return, or address a tax issue. Common notices include Section 139(9) for defective returns, Section 142(1) for information requests, Section 143(2) for scrutiny assessment, and Section 156 for outstanding tax demands.
How Should a Partnership Firm Respond to an Income Tax Notice?
The firm should handle the notice based on the specific issue rather than submitting a generic reply. Follow these steps:
- Verify the notice: Check the firm’s PAN, relevant tax year, notice reference number, and response deadline.
- Understand the reason: Identify whether the notice concerns a defective return, income mismatch, missing documents, or unpaid tax.
- Gather supporting documents: Collect the relevant ITR-5, financial statements, bank records, TDS details, tax challans, and partnership deed.
- Review the information: Compare the notice with the firm’s records and identify any errors or differences that require explanation.
- Submit a response: Reply through the Income Tax e-Filing portal using the method specified in the notice, and attach relevant supporting documents.
- Resolve outstanding demands: Pay the confirmed tax demand or submit a response explaining why the demand is incorrect or already paid.
- Save the records: Keep a copy of the notice, submitted response, supporting documents, and acknowledgement for future reference.
When Should a Partnership Firm File Its Income Tax Return?
The income tax return deadline for a partnership firm depends primarily on whether the firm is required to get its accounts audited under the Income Tax Act.
- Partnership firms not subject to tax audit: The due date for AY 2026–27 was 31 August 2026.
- Partnership firms subject to tax audit: The original due date of 31 October 2026 has been extended to 21 November 2026. The tax audit report is due by 21 October 2026.
- Firms subject to transfer pricing requirements: The return filing due date is 30 November 2026.
A firm should also complete the applicable tax audit and audit-report filing requirements before the income tax return deadline. Missing the prescribed return date can result in late-filing consequences and may affect the firm's ability to claim certain benefits.
Connect with RegisterKaro and let our experts handle the legal hassle while you grow your business.
Frequently Asked Questions (FAQs)
Is income tax return filing mandatory for a partnership firm?
Yes, every partnership firm must file an income tax return regardless of whether it earns a profit or incurs a loss. This requirement applies to registered and unregistered partnership firms. The firm generally uses ITR-5 to report its income, expenses, deductions, tax liability, and other required information to the Income Tax Department.
Which ITR form should a partnership firm use?
A partnership firm generally files its income tax return using ITR-5. The form applies to firms and several other taxpayer categories under the Income Tax Act. Individual partners do not report the firm's income through the firm's ITR-5; each partner must file their own applicable income tax return separately.
What is the income tax rate for a partnership firm?
A partnership firm generally pays income tax at a flat rate of 30% on its taxable income. A 12% surcharge applies when taxable income exceeds ₹1 crore, subject to marginal relief. The firm must also pay Health and Education Cess at 4% on income tax and applicable surcharge.
Does a partnership firm have to file a return if it has no income?
Yes, a partnership firm must file its income tax return even when it has no profit or incurs a loss. The Income Tax Department treats return filing as mandatory for partnership firms, regardless of their income or loss position. Timely filing can also preserve eligibility for applicable loss carry-forward benefits.
Can a partnership firm claim interest paid on partners’ capital?
Yes, a partnership firm can generally claim interest paid on partners’ capital as a deduction when it satisfies Section 40(b) conditions. The partnership deed must authorize the payment, and the deductible interest rate cannot exceed 12% per annum. The firm should maintain proper records supporting the capital balance and interest calculation.
Is remuneration paid to partners deductible for a partnership firm?
Yes, remuneration paid to eligible working partners can qualify as a deduction when the firm meets the conditions under Section 40(b). The partnership deed must authorize the payment, and the firm must stay within the prescribed statutory limits. The firm should maintain supporting records for remuneration calculations and payments.
When must a partnership firm undergo a tax audit?
A partnership firm must obtain a tax audit when its business or professional activities cross the applicable Section 44AB conditions. The audit threshold depends on the nature of the activity and specified cash receipt or payment conditions. The firm should assess its turnover, receipts, payments, and applicable presumptive taxation provisions before determining its audit requirement.
What is the due date for filing a partnership firm’s ITR?
The due date depends on whether the firm requires a tax audit and on the assessment year. For AY 2026-27, the general due date for non-audit business cases was 31 August 2026, while audit cases had a 31 October deadline. CBDT later extended specified audit-case filings to 21 November 2026.
How can a partnership firm file its income tax return online?
A partnership firm can file ITR-5 through the Income Tax Department’s e-Filing portal after preparing its financial and tax information. The firm should reconcile income, expenses, TDS, taxes paid, partner-related entries, and deductions before submission. It must then complete verification using the authentication method applicable to the firm.
How can a partnership firm check its ITR status?
A partnership firm can check its ITR status online using the acknowledgement number and a valid mobile number without logging into the portal. After entering the required OTP, the portal displays the return status. After logging in, the firm can also access filed returns, acknowledgements, intimation orders, and pending verification actions.
What should a partnership firm do after receiving an income tax notice?
A partnership firm should first verify the notice, identify the issue, and compare the information with its tax records. It should then collect relevant documents and submit a response within the specified deadline. The e-Proceedings facility allows taxpayers to view and respond to eligible notices, intimations, and clarification requests online.
What happens if a partnership firm files its ITR after the due date?
A partnership firm that files its return late may pay a fee of ₹5,000 under Section 234F, reduced to ₹1,000 if its total income does not exceed ₹5 lakh. It may also owe interest under Section 234A on unpaid tax. For AY 2026–27, the firm can generally file a belated return by 31 December 2026, subject to the applicable conditions. Business losses, except unabsorbed depreciation, generally cannot be carried forward unless the firm files its return by the due date. For Tax Year 2026–27 onward, Section 428 of the Income-tax Act, 2025, governs the late-filing fee.
How can a partnership firm verify its ITR without a DSC?
A partnership firm can verify its ITR without a Digital Signature Certificate (DSC) by using an Electronic Verification Code (EVC) or another permitted verification method, provided the firm is not required to use a DSC. The firm can generate an EVC through an eligible, pre-validated bank account or demat account or use net banking where available. However, firms subject to a tax audit under Section 44AB must verify their returns using a DSC.

Reviewed by
Joel DsouzaJoel Dsouza is a Chartered Accountant (CA) and compliance expert with over 7 years of hands-on experience in company registration, tax structuring, GST, ROC filings, and MCA compliance. As a qualified member of the Institute of Chartered Accountants of India (ICAI) and Co-Founder at RegisterKaro, he has personally advised more than 1,000 startups and SMEs across India, helping founders navigate incorporation, regulatory frameworks, and financial planning from Day 1. With deep expertise across all three levels of Finance and Portfolio Management, Joel is committed to promoting financial literacy and simplifying India's startup ecosystem through clear, actionable guidance that entrepreneurs can act on immediately.
Why Choose RegisterKaro for Partnership Firm ITR Filing?
RegisterKaro helps partnership firms prepare and file their income tax returns with a focus on accurate financial reporting, partner-related entries, deductions, and applicable tax requirements.
- ITR-5 Filing Support: Get assistance with preparing and filing ITR-5 for the partnership firm.
- Financial Data Review: We review income, expenses, partner capital accounts, remuneration, interest, and other relevant financial details before filing.
- Tax and Deduction Checks: We help identify applicable deductions and review the firm's tax computation and TDS reconciliation before submission.
- Audit and Compliance Support: If the firm falls under tax audit requirements, we can assist with the related compliance and filing requirements.
- Notice and Post-Filing Assistance: Get support with eligible post-filing requirements and broader partnership firm annual compliance, including responding to applicable income tax notices.
- Online Filing and Status Tracking: Complete the filing process online and track the return status through the applicable Income Tax Department facilities.
What Our Clients Say
View All
Gautam Arora
 Verified
I am very much impressed with your work. Suhani sachdev not only handled my queries but also managed to deliver a smooth and efficient completion of a... Read more

Pinu Upadhyaya
VerifiedAman Ajmera has been a consistent and reliable contributor. He is always responsive and proactive in addressing issues and finding solutions. I apprec... Read more

NITI AGRO
VerifiedRegisterKaro provided an excellent experience throughout our company registration process. A special thanks to Ms. Harshita for her outstanding suppor... Read more

Avijit Banerjee
VerifiedIncorporating my LLP felt like less of a legal hurdle and more like a victory lap! RegisterKaro streamlined the whole thing – they're like the Usain B... Read more

kajal pal
VerifiedRegisterKaro has provided reliable and timely support throughout my journey. Archana has always been responsive, professional, and easy to work with.... Read more

Akash Rai
VerifiedIt was a seamless experience with all the compliances done. Sunidhi was very helpful and patient throughout the process. Very professional service. Hi... Read more

Rehan Shaikh
VerifiedRegistration process was smooth overall. Special thanks to Tanu for being supportive, responsive, and assisting throughout the process. Appreciate the... Read more

Ashok Benial
VerifiedI recently had the pleasure of working with Madhur for my company’s registration process, and I couldn’t be more satisfied with the experience. From s... Read more

KULDEEP KHANNA
VerifiedIt's a nice experience with register Karo...team ..special thanks to entire team& supportive team who keep calling and provide a good support while ur... Read more

Sabrin Khan
VerifiedShe works well under pressure by herself and with other team members. She is detail-oriented and completes tasks in a timely manner.thanks Nehalakra .... Read more
Related Blogs
View All
Form 3 LLP: Filing, Due Date, Fees & Penalty (2026)
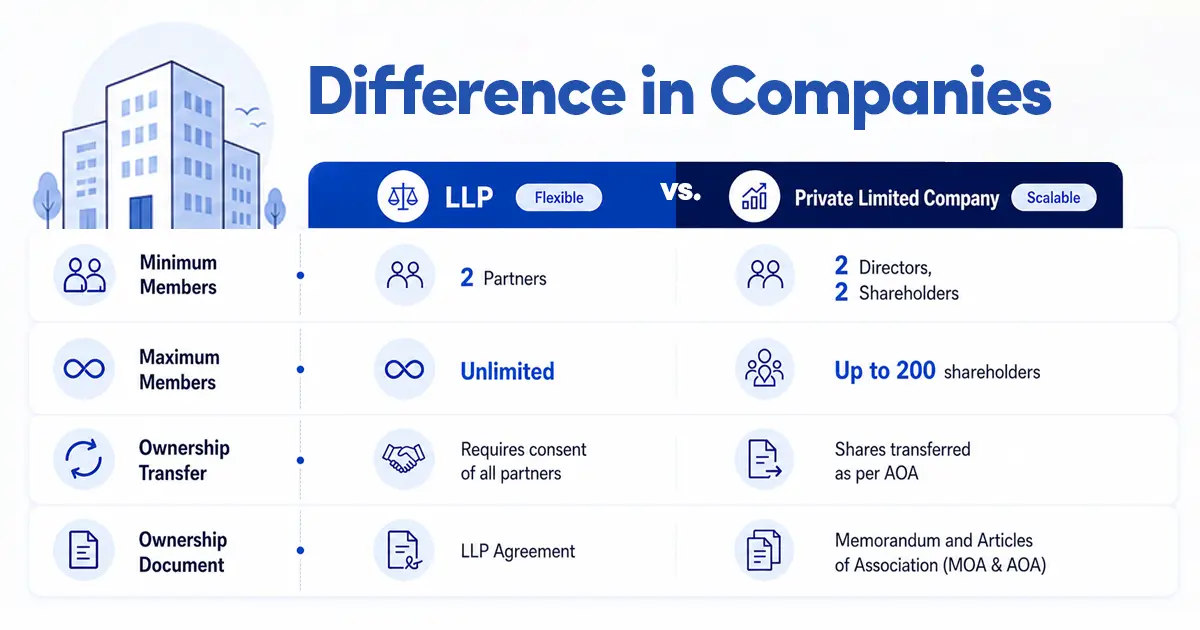
Difference Between Private Limited Company and LLP in India
How to Convert a Private Limited Company into an LLP (2026)
How to Convert Sole Proprietorship to LLP in India (2026): Process & Fees
LLP Audit Applicability 2026: Statutory & Tax Audit Limits
LLP Form 8: Due Date, Late Fee, Filing Process, and Format
Difference Between Partnership and Joint Stock Company in India
How to Convert an LLP to a Private Limited Company in India
LLP Registration Fees in India (2026): Govt Costs & Stamp Duty Charges
LLP Registration for NRIs & Foreign Nationals in India