

A partnership succeeds when partners combine their resources, skills, and effort toward a shared goal. That success depends on a clear understanding of the rights and duties of partners in a partnership firm. Whether it’s participating in business, reviewing books, or analyzing profits, without the clarity of rights, businesses can face serious challenges, including disputes and operational inefficiencies.
Partnership firm registration formalizes the agreement between partners and secures legal recognition of their arrangement. The Indian Partnership Act, 1932, sets out the rights and duties of partners, which brings transparency and fairness to their dealings and fixes clear expectations for each partner. When partners follow this framework, they manage their roles with confidence and prevent most conflicts before they start.
In this guide, we will explore the key rights, duties, and liabilities of partners in a partnership firm under the Indian Partnership Act, 1932. It will help you understand their roles and responsibilities for maintaining a successful business relationship.
Key Takeaways
- Partners have important rights, including participating in business management, sharing profits, accessing financial records, and being consulted on key decisions.
- The Indian Partnership Act, 1932, defines the rights, duties, and liabilities of partners, ensuring transparency and fairness in partnership firms.
- Partners are required to act in good faith, avoid conflicts of interest, maintain proper records, and share profits and losses as agreed.
- Every partner has joint and several liability, making them legally responsible for the firm’s debts and obligations.
- A well-drafted partnership deed clearly defines each partner’s role, minimizes disputes, and supports the firm’s long-term growth and stability.
What are the Rights of Partners in a Partnership Firm?
Every partner in a partnership firm holds certain rights that allow them to make decisions, share profits, and take part in daily operations. The Indian Partnership Act, 1932 defines these rights as follows:
1. Right to Participate in the Business Management: Section 12(a)
Each partner has the right to participate in the business’s management. According to Section 12(a) of the rights and duties of partners in the Partnership Act 1932, unless otherwise agreed upon, every partner has the right to take part in the decision-making processes of the firm.
2. Right to Share Profits: Section 13(b)
Partners have the right to share profits as per the partnership agreement under Section 13(b). Typically, profits are shared equally unless a different ratio has been specified in the partnership deed. This right ensures that all partners are rewarded for their contributions to the partnership firm.
3. Right to Indemnity: Section 13(e)
If a partner has to bear any expenses or liabilities due to the firm’s activities, they have the right to seek indemnity from the firm. This particular right under Section 13(e) means the firm must reimburse the partner for any losses they incur while carrying out their responsibilities, including any liabilities arising from the firm’s activities. This right is an essential part of the rights and duties of partners.
4. Right to Access Information: Section 12(d)
Partners have the right to access the firm’s financial records and other important business information as per Section 12(d). Financial transparency is crucial for fostering trust and ensuring efficient business operations. This right is a fundamental aspect of the rights and duties of partners under the Partnership Act 1932.
5. Right to Be Consulted: Section 12(c)
Section 12(c) allows partners to settle ordinary business matters by majority, and it gives each partner the right to express their view before the firm reaches a decision. Partners cannot change the nature of the business itself without the consent of all partners.
6. Right to Prevent Admission of a New Partner: Section 31
Existing partners have the right to stop the admission of a new partner into the firm as per Section 31. The firm can admit a new partner only with the consent of all existing partners, unless the partnership deed states otherwise.
7. Right to Retire: Section 32(1)
As per Section 32(1), any partner can retire from the partnership firm with the consent of all other partners. In a partnership at will, a partner may retire by giving written notice to all remaining partners, without requiring their consent.
8. Right Not to Be Expelled: Section 33
Every partner has the right to continue as a member of the firm. The firm cannot expel a partner merely by a majority decision.
Partners may expel a partner only if:
- The partnership deed expressly allows expulsion
- Partners exercise the power in good faith
- Expulsion benefits the partnership firm
9. Right to Dissolve the Firm: Section 40
Partners may dissolve the partnership firm with the consent of all partners under Section 40. In a partnership at will, any partner can dissolve the firm by issuing a written notice to all other partners stating the intention to dissolve.
What are the Duties of Partners in the Partnership Act 1932?
Alongside their rights, partners also have specific duties towards each other and the firm. These duties of partners in a partnership firm ensure its smooth functioning and promote mutual trust. Here are the main duties of partners in the Partnership Act, 1932:
1. Duty to Act in Good Faith
Section 9 requires every partner to act in good faith and to place the interest of the firm above personal gain. Any act that breaks trust or harms the firm’s reputation breaches this duty.
2. Duty to Contribute to the Capital
Each partner must contribute capital to the firm on the terms set in the partnership agreement. A partner who fails to contribute may face legal consequences and may see their profit share affected. To avoid such legal consequences of a partnership deed, a firm must have a well-drafted document.
3. Duty to Share Losses
Along with sharing profits, partners are also responsible for sharing the firm’s losses. Unless otherwise agreed, losses are typically distributed in the same ratio as the profits. This is another important aspect of the rights and duties of partners.
4. Duty to Avoid Conflicts of Interest
A partner must not let personal interest conflict with the interest of the firm. Under Section 16, a partner must not use the firm’s property or business connection for personal profit, and must account to the firm for any such gain.
5. Duty to Maintain Books and Records
Maintaining accurate and up-to-date books of accounts is a critical responsibility of each partner. This ensures that financial records are transparent, helping in business audits and resolving disputes when necessary.
6. Duty to Not Compete
Section 16 also restrains a partner from conducting a competing business without the consent of the other partners. A partner who breaches this duty must account to the firm for the profits of that competing business.
Liabilities of Partners in a Partnership Firm
Along with the rights and duties of partners in the Partnership Act, 1932, the liabilities are of utmost significance. Here’s a closer look at the responsibilities:
a. Joint and Several Liability
Partners in a partnership firm hold joint and several liability for the firm’s debts. This means that if the firm encounters financial issues, each partner is individually responsible for the full debt, though they can seek reimbursement from the other partners for their share
b. Liability for Acts of Other Partners
Every partner is also liable for the actions of other partners, as long as those actions are in the normal course of business. If a partner incurs a debt or enters a contract that benefits the firm, all partners are equally responsible.
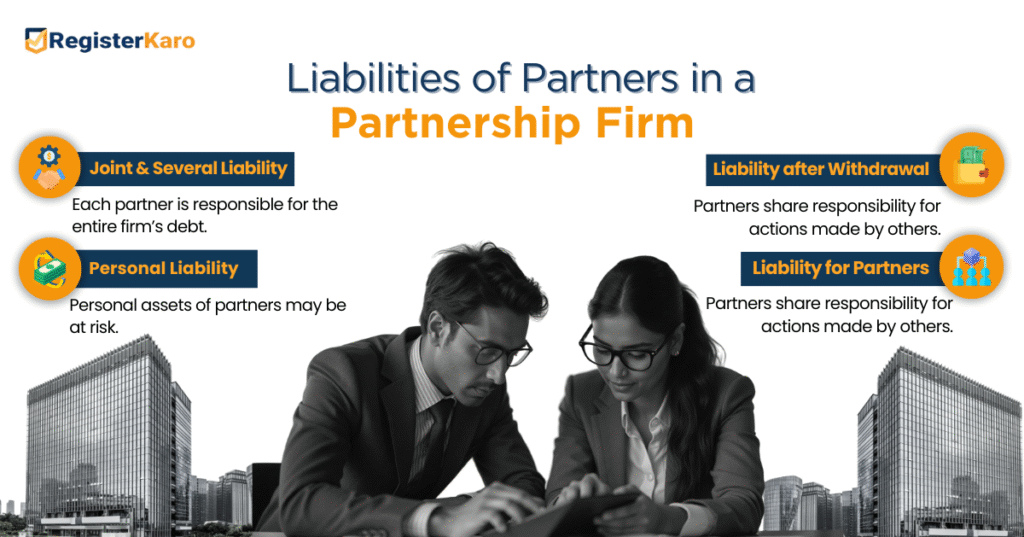
c. Personal Liability
In a general partnership, there is no distinction between the firm’s debts and the personal liabilities of the partners. This means that if the business encounters legal or financial issues, the personal assets of the partners could be exposed to risk.
d. Liability after Withdrawal
A partner remains liable for the firm’s debts even after leaving the business, unless the firm’s creditors release them from liability. This is a key point to remember when considering partnership dissolution. Failure to do so could result in the former partner being held accountable for the firm’s debts even after their departure.
Ending Note
A thorough understanding of the rights and duties of partners determines the success of a partnership firm. When partners define these roles in the partnership agreement, they prevent misunderstandings, build trust, and keep operations running smoothly.
The Indian Partnership Act, 1932, provides a legal framework that protects the interests of every partner and lets them work together with confidence. When partners understand their rights, duties, and liabilities, they safeguard the business and build an environment of mutual respect and steady growth, which positions the firm to succeed over the long term.
