

Difference Between Private Limited Company and LLP in India
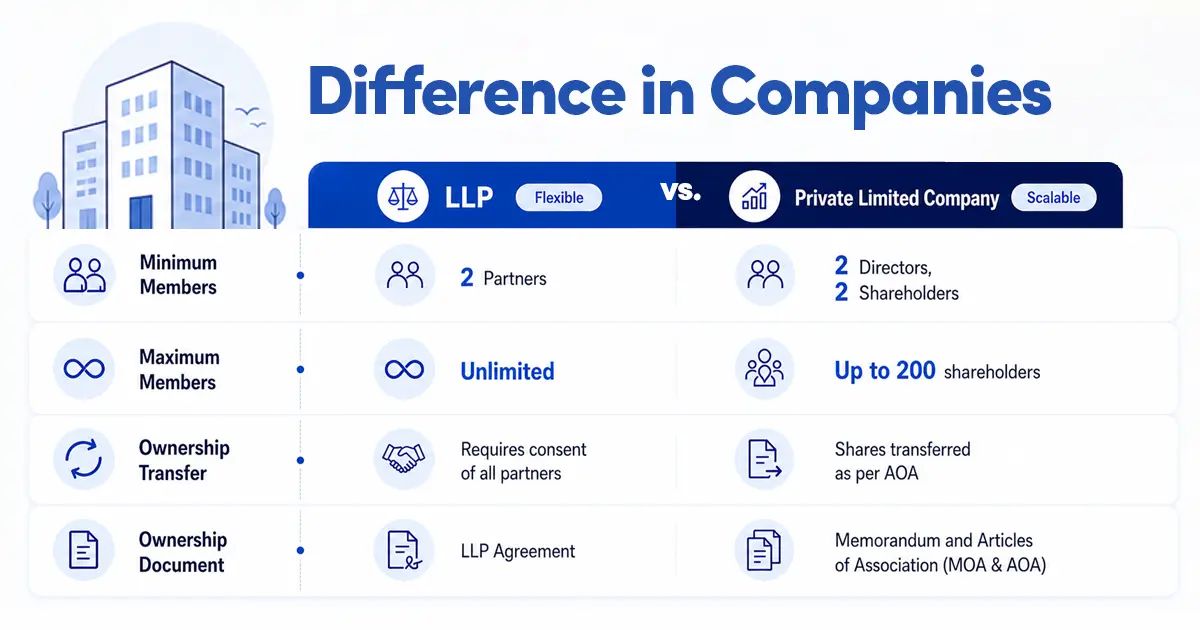
The key difference between LLP and Private Limited Company structures lies in how they are owned, managed, and funded. An LLP is owned and managed by partners under an LLP agreement, while a Private Limited Company is owned by shareholders and managed by a board of directors under the Companies Act, 2013. A Private Limited Company can issue shares and ESOPs, making it suitable for startups seeking investment. An LLP cannot offer these options, but it has fewer compliance requirements, and its partners' share of profits is not taxed again.
Although both offer limited liability and a separate legal identity, their different structures affect how they raise funds, distribute profits, and meet compliance requirements. The choice ultimately depends on your business model, funding plans, compliance capacity, and tax considerations. For instance, a Private Limited Company may suit a funding-focused startup, while an LLP may better serve a professional or owner-funded business.
In short, a company is built to grow through outside investment, while an LLP is built for partners who value flexibility and lower running costs.
Key Takeaways
An LLP is governed by the LLP Act, 2008, while a Private Limited Company is governed by the Companies Act, 2013. Both are registered with the MCA.
Only a Private Limited Company can issue shares and ESOPs, making it the preferred structure for angel and venture capital investors.
An LLP pays tax at an effective rate of 31.2%, increasing to 34.94% when income exceeds ₹1 crore. A company pays 25.17% under Section 200. However, an LLP partner’s share of profit is not taxed again.
Under Rule 24(8) of the LLP Rules, an LLP needs a statutory audit only when its turnover exceeds ₹40 lakh or its contribution exceeds ₹25 lakh. Every company, however, must undergo an annual statutory audit.
Difference Between Private Limited Company and LLP: Comparison Table
The table below sets out the Private Limited Company and LLP differences across legal structure, taxation, compliance, and funding:
Parameter | LLP | Private Limited Company |
Governing law | LLP Act, 2008 and LLP Rules, 2009 | Companies Act, 2013 |
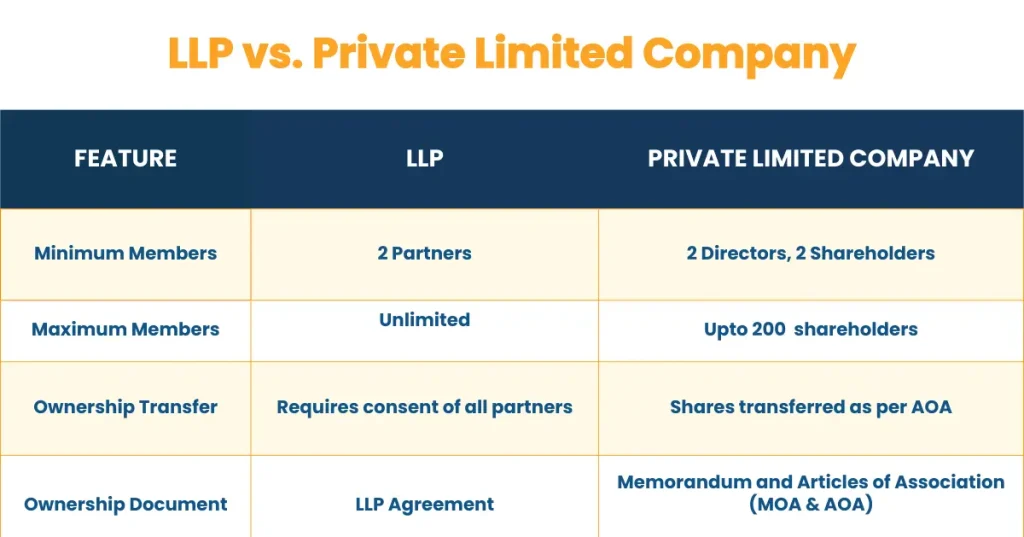
Ownership and management | At least 2 partners, run by at least 2 designated partners, one of whom must reside in India for 120 days or more in the financial year | 2 to 200 members, run by a board of 2 to 15 directors (more by special resolution), one of whom must reside in India for 182 days or more in the financial year |
Liability | Partners are liable up to their agreed contribution, but remain liable for their own wrongful acts | Shareholders are liable up to the unpaid amount on their shares |
Equity and ESOPs | Cannot issue shares or offer ESOPs; capital comes from partners' contributions and loans | Can issue equity and preference shares, debentures, and ESOPs |
Taxation | Profits taxed once at the LLP level; partners’ profit share is exempt | Profits taxed at the company level, and again as dividends in shareholders’ hands |
Annual compliance | Form 11 and Form 8; audit only if turnover exceeds ₹40 lakh or contribution exceeds ₹25 lakh; no mandatory meetings | AOC-4 and MGT-7/7A; annual statutory audit; 4 board meetings (2 for a small company) and an AGM |
Ownership Transfer | Partners join or exit through an amended LLP agreement, filed in Forms 3 and 4 | Shares transfer between members, subject to the Articles of Association |
Foreign investment | Only in sectors open to 100% FDI under the automatic route, with no FDI-linked performance conditions | Under the automatic or government route, subject to sectoral caps |
Registration cost | LLP registration fees include ₹200 for RUN-LLP and a FiLLiP fee of ₹500 to ₹5,000, based on contribution, plus state stamp duty on the LLP agreement | Pvt Ltd Company registration fees include ₹1,000 for name reservation, with no SPICe+ fee for authorized capital up to ₹15 lakh, plus state stamp duty on the MoA and AoA |
Note: Late filing costs more for a company over time. An LLP’s additional fee rises in slabs with the delay, up to 50 times the normal fee for most forms. For Form 8 and Form 11, it reaches 30 times the normal fee (15 times for a small LLP) and then grows by ₹20 a day (₹10 for a small LLP) after 360 days, with no upper limit. Separate penalties under the LLP Act may also apply.
LLP vs Pvt Ltd Company: Tax Comparison With an Example
An LLP and a Private Limited Company differ in both their tax rates and how profits are taxed. An LLP pays tax once on its profits, while a company pays corporate tax and its shareholders pay tax separately on any dividends they receive. The table below compares their tax treatment:
LLP | Private Limited Company | |
Base rate | 30% | 22% under the optional Section 200 regime; otherwise 25% (turnover up to ₹400 crore in FY 2024-25) or 30% |
Surcharge and cess | 12% surcharge above ₹1 crore of income, plus 4% cess | 10% surcharge under Section 200, plus 4% cess; regular rates attract surcharge above ₹1 crore, plus cess |
Effective rate | 31.2% (34.94% above ₹1 crore) | 25.17% under Section 200 |
Tax on profits paid to owners | None; the partners’ profit share is exempt under Schedule III, S. No. 2 | Dividends are taxed at each shareholder’s slab rate |
TDS on payments to owners | 10% TDS under Section 393(3) on salary, remuneration, commission, bonus, and interest paid to a partner above ₹20,000 a year | TDS on dividends paid to shareholders and on salaries paid to directors, at the applicable rates |
Consider a business earning ₹50 lakh in annual profit, owned equally by two people with no other income. If it operates as an LLP, it pays ₹15.60 lakh in tax, with no additional tax on the owners. As a Private Limited Company under Section 200, it pays ₹12.58 lakh in corporate tax. If it distributes the remaining profits as dividends, the owners pay another ₹3.62 lakh in tax (₹1.81 lakh each), bringing the total to ₹16.21 lakh. If the company retains the profits, the immediate tax remains ₹12.58 lakh, with no additional owner-level tax until distribution.
Note: The 22% rate under Section 200 is optional. A company that chooses it gives up most deductions and incentives, and cannot withdraw the choice in later years. An LLP that claims certain deductions, such as profit-linked deductions under Chapter VIII-C, must also pay Alternate Minimum Tax (AMT) under Section 206(2) at 18.5% of its adjusted total income if this exceeds its regular tax. Partners’ remuneration, interest on capital, and directors’ salaries can also change the final tax for either structure.
Similarities Between LLP and Private Limited Company
Although an LLP and a Private Limited Company differ in ownership, taxation, and funding, they share several legal and operational features. Both:
Have a legal identity distinct from their owners, and can own property, enter into contracts, and sue or be sued in their own names.
Protect their owners' personal assets from business debts, subject to their contributions and applicable legal exceptions.
Continue to exist even if a shareholder or partner dies, retires, or leaves the business.
Need no minimum capital contribution or paid-up capital for incorporation.
Are incorporated and regulated by the Ministry of Corporate Affairs (MCA). An LLP receives an LLP Identification Number (LLPIN), and a company receives a Corporate Identification Number (CIN).
Must have an MCA-approved name. A Private Limited Company's name ends with "Private Limited," and an LLP's with "LLP."
Must comply with tax audit requirements under Section 63 of the Income-tax Act, 2025, which apply above ₹1 crore of turnover (₹10 crore where cash receipts and payments each stay within 5%) or professional gross receipts exceed ₹50 lakh. These are separate from statutory audits, which are mandatory every year for companies but depend on turnover and contribution for LLPs.
Can obtain GST and Udyam registrations, apply for trademark protection, and seek DPIIT startup recognition if you meet the eligibility conditions.
Private Limited Company vs LLP: Which Is Better for You?
The right choice depends on how the business will raise money and what it will do with its profits. Neither structure is better in every case.
When is an LLP the Better Fit?
An LLP suits businesses that:
Run on the partners’ own capital or bank loans, with no plans to bring in equity investors.
Distribute most of their profits to the owners each year, since the partners’ profit share is exempt from further tax.
Want lighter compliance, with no mandatory board meetings and no statutory audit until turnover crosses ₹40 lakh or contribution crosses ₹25 lakh (a tax audit may still apply).
Need flexible profit sharing that partners can change through the LLP agreement rather than through a shareholding change.
Examples: CA, CS, and law firms; architecture and design studios; consultancies; family-run service businesses. For instance, two professionals starting a consulting firm with their own capital can define their roles and profit shares in an LLP agreement, without following a full corporate governance framework.
Businesses considering an LLP often weigh it against a traditional partnership as well. Our guide on the difference between LLP and partnership firm explains how the two differ.
When is a Private Limited Company the Better Choice?
A Private Limited Company suits businesses that:
Plan to raise money from angel investors, venture capital funds, or private equity, which invest through shares.
Want to reward employees with ESOPs.
Retain profits to fund growth, since the 25.17% effective rate under Section 200 is lower than an LLP’s 31.2%.
Need foreign investment in a sector that does not allow it in an LLP through the automatic route.
Bid for contracts or tenders that require or prefer a company.
Examples: Tech and SaaS startups, e-commerce brands, fintech and healthtech ventures, manufacturers, and export businesses. A technology startup planning to raise angel funding, for example, can issue shares to investors and set aside an ESOP pool for employees.
An LLP is not automatically the better choice just because it costs less to maintain. For a business planning to raise substantial external investment, the high cost of Private Limited Company compliance may be worthwhile because this structure supports equity funding.
Note: A business structure can change as funding needs and operations evolve. A business that needs equity investors or wants to offer ESOPs can convert LLP into Private Limited Company. Similarly, a company that no longer needs equity funding and wants lighter compliance can convert into an LLP.
Understanding LLP and Private Limited Company
An LLP and a Private Limited Company differ in their ownership, management, compliance requirements, and ability to raise funds. Understanding how each structure works can help you choose the right one based on your business goals, number of owners, and future funding plans.
What is an LLP?
A Limited Liability Partnership (LLP) is a separate legal entity registered under the Limited Liability Partnership Act, 2008. It combines the flexibility of a traditional partnership with the limited liability protection of a company. Partners can decide how to manage the business, divide responsibilities, and share profits through an LLP agreement filed with the MCA.
This freedom to structure the business around the partners' needs makes LLP registration a popular choice for professional firms and service businesses.
What is a Private Limited Company?
A Private Limited Company, on the other hand, has a more structured ownership and management framework under the Companies Act, 2013. Its shareholders own the business, while a board of directors oversees its operations. Under Section 2(68), its Articles of Association must restrict share transfers, limit membership to 200, and prohibit invitations to the public to subscribe to its securities.
Unlike an LLP, this share-based structure makes it easier to bring in investors and distribute ownership through shares. This is why Pvt Ltd Company Registration is a common choice for funded startups and growth-oriented businesses.
Conclusion
Choosing between an LLP and a Private Limited Company is easier when you consider your long-term business plans. Think about your funding needs, plans to offer employee equity, and whether you will reinvest or distribute profits. Changing the structure later involves fresh filings and may have tax implications.
The right founding documents are equally important. An LLP needs a well-drafted LLP agreement, while a company needs clear Articles of Association and, where applicable, a shareholders' agreement. Contact RegisterKaro for help choosing the right structure, completing registration, and handling company and LLP compliance.

Comments
Be the first to comment!