


Form MGT-7 is a form used to file the annual return with the Registrar of Companies (ROC) under Section 92 of the Companies Act, 2013. It gives the Ministry of Corporate Affairs (MCA) a yearly record of the company’s corporate details, including its shareholding, members, directors, registered office, and other prescribed information as at the close of the financial year.
For applicable companies, filing the annual return is a mandatory annual compliance requirement, regardless of whether the company carried on business during the year. The filing requirements applicable to its status continue unless the relevant statutory obligation has ceased. MGT-7 must generally be filed within 60 days of the Annual General Meeting (AGM), with a filing fee of around ₹200 to ₹600. Late filing attracts an additional fee of ₹100 per day, with no maximum cap.
Key Takeaways
- Form MGT-7 is the annual return filed with the ROC under Section 92 of the Companies Act, 2013, covering the company’s shareholding, management, and other key details as of the financial year-end.
- It must be filed within 60 days of the Annual General Meeting (AGM). For an AGM held on 30 September 2027, the due date is 29 November 2027.
- Small companies and OPCs file Form MGT-7A, a shorter version. Following the revised limits of ₹10 crore paid-up capital and ₹100 crore turnover effective 1 December 2025, more companies may qualify for MGT-7A.
- Annual returns are filed on the MCA V3 portal, and Form AOC-4 must be filed before MGT-7.
- Late filing attracts an additional fee of ₹100 per day with no maximum limit, making timely filing important.
What is the MGT-7 Form? Contents and Types
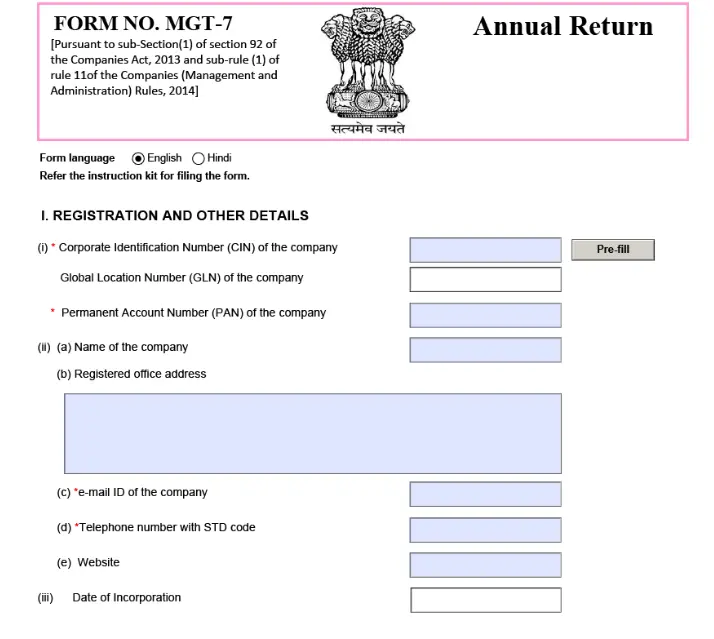
Form MGT-7 is the electronic annual return prescribed under Section 92 of the Companies Act, 2013, read with the Companies (Management and Administration) Rules, 2014. It records the company’s prescribed corporate details as they stood at the close of the financial year, including its ownership, management, share capital, and other statutory information. Its purpose is different from Form AOC-4, which is used to file the company’s financial statements.
What Does the Annual Return Capture?
MGT-7 records prescribed information about the company for the financial year, including:
- Registered office address and principal business activities
- Share capital, debentures, and shareholding pattern
- Directors, key managerial personnel, and changes during the year
- Members, meetings, remuneration, and indebtedness
- Penalties, punishments, or compounding of offenses during the year
These disclosures give the Ministry of Corporate Affairs (MCA) and other stakeholders an annual record of the company’s corporate structure and statutory particulars.
Note: MGT-7 must be filed within 60 days of the Annual General Meeting (AGM). The government filing fee is based on the company’s share capital and ranges from ₹200 to ₹600 (₹200 for companies without share capital). Late filing attracts an additional fee of ₹100 per day, with no upper limit, along with applicable penalties.
Difference Between MGT-7 and MGT-7A
MGT-7 is the standard annual return, while MGT-7A is the abridged form for eligible OPCs and Small Companies. The key differences are:
| Particular | MGT-7 | MGT-7A |
| Applicability | Companies required to file the standard annual return under the applicable rules | One Person Companies (OPCs) and eligible Small Companies |
| Format | Standard annual return | Abridged annual return |
| Small Company eligibility | Not applicable | Paid-up capital up to ₹10 crore and turnover up to ₹100 crore, subject to other statutory conditions |
| Level of disclosure | More detailed corporate and statutory information | Fewer and simpler disclosures |
| Compliance burden | Relatively higher due to broader disclosures | Lower for eligible smaller companies |
| Purpose | Records the company’s prescribed annual corporate particulars | Provides a simplified annual return for eligible OPCs and Small Companies |
MGT-7 Updates for FY 2026-27
Before filing the annual return for FY 2026-27, check three key points: the revised Small Company limits, MCA V3 filing requirements, and the applicable filing deadline.
1. Revised Small Company Limits From 1 December 2025
The Companies (Specification of Definitions Details) Amendment Rules, 2025 revised the eligibility limits for Small Companies. The paid-up capital limit increased from ₹4 crore to ₹10 crore, while the turnover limit increased from ₹40 crore to ₹100 crore, subject to the other conditions under the Companies Act.
This change may bring some companies that previously filed MGT-7 within the Small Company definition, making them eligible to file the abridged MGT-7A instead. Check your company’s status under the revised limits before selecting the annual return form.
2. MGT-7 Filing on the MCA V3 Portal
MGT-7 and MGT-7A are now filed through the MCA V3 portal. Signatories must register as Business Users and associate their Digital Signature Certificate (DSC) with their MCA profile before filing.
The financial statements must be filed through AOC-4 before MGT-7/MGT-7A, as the annual return is filed after the financial statement filing.
3. MGT-7 Due Date for FY 2026-27
The annual return must generally be filed within 60 days of the AGM. If the AGM is held on 30 September 2027, the MGT-7 or MGT-7A filing deadline will be 29 November 2027.
Who Must File MGT-7? Applicability and Exemptions
Under Section 92 of the Companies Act, 2013, companies are generally required to file an annual return with the ROC in the applicable form, either MGT-7 or MGT-7A. The form depends on the company’s type and whether it meets the conditions for filing the abridged annual return.
- MGT-7: Filed by companies that are not eligible for MGT-7A, including private and public companies that exceed the Small Company limits. It also applies to companies excluded from the Small Company definition, such as holding companies, subsidiary companies, and Section 8 companies, regardless of their size.
- MGT-7A: Filed by One Person Companies (OPCs) and eligible Small Companies that meet the prescribed conditions, including the applicable paid-up capital and turnover limits.
Note: There is no general exemption from annual return filing because a company is dormant or has not carried on business. The filing obligation continues until the company is formally struck off, dissolved, or otherwise ceases to have the applicable filing obligation.
Which Attachments are Required to File MGT-7?
MGT-7 includes an Attachments section where the company uploads the documents required to support the information reported in the annual return. The attachments depend on the company’s circumstances and the requirements applicable to that filing.
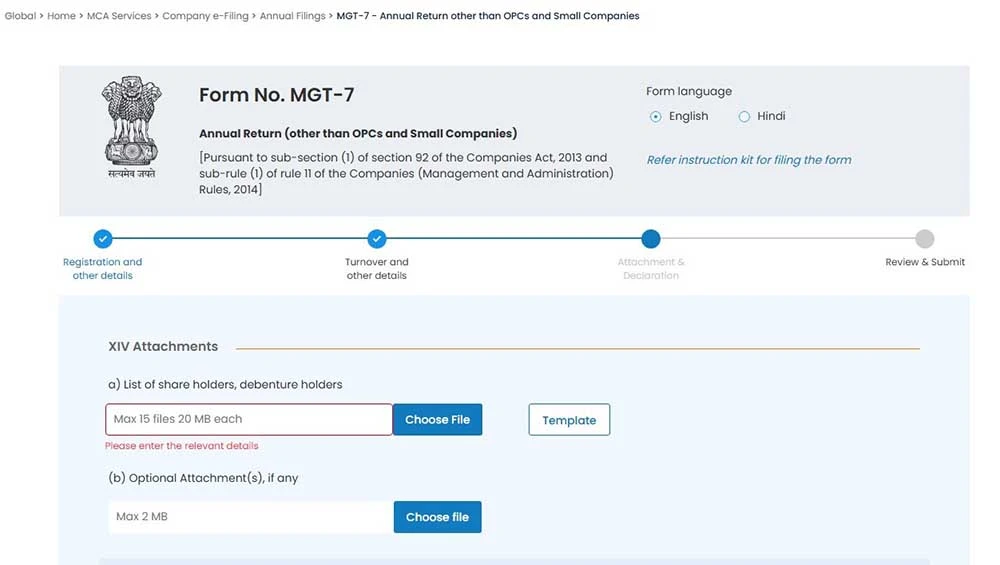
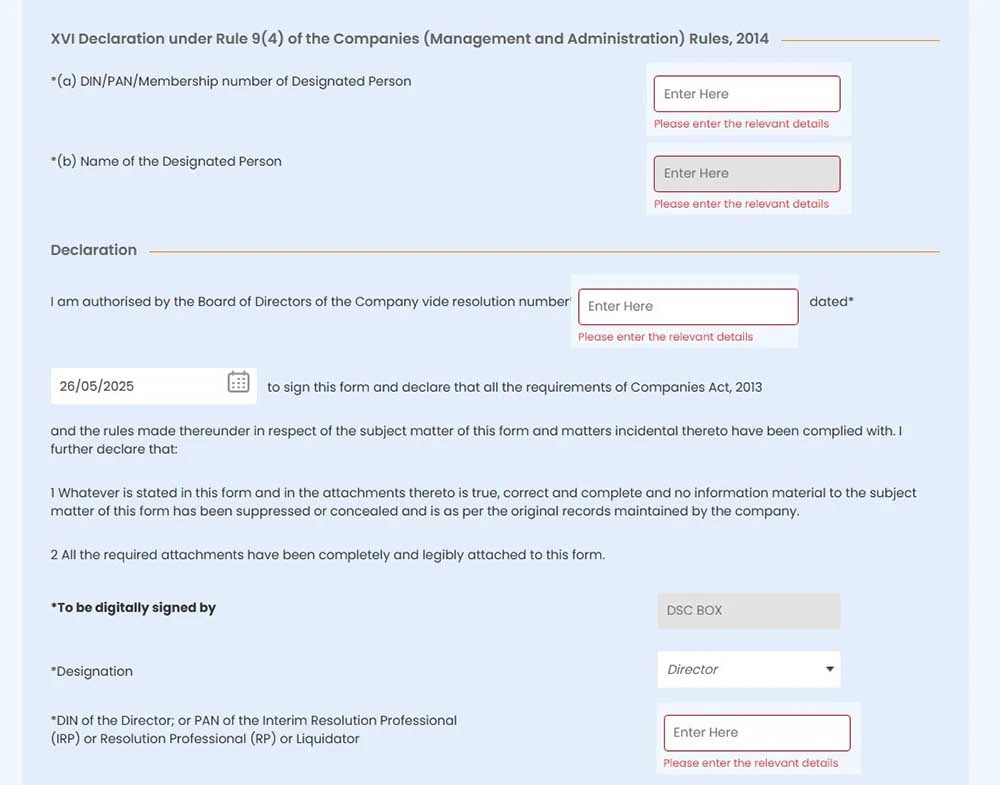
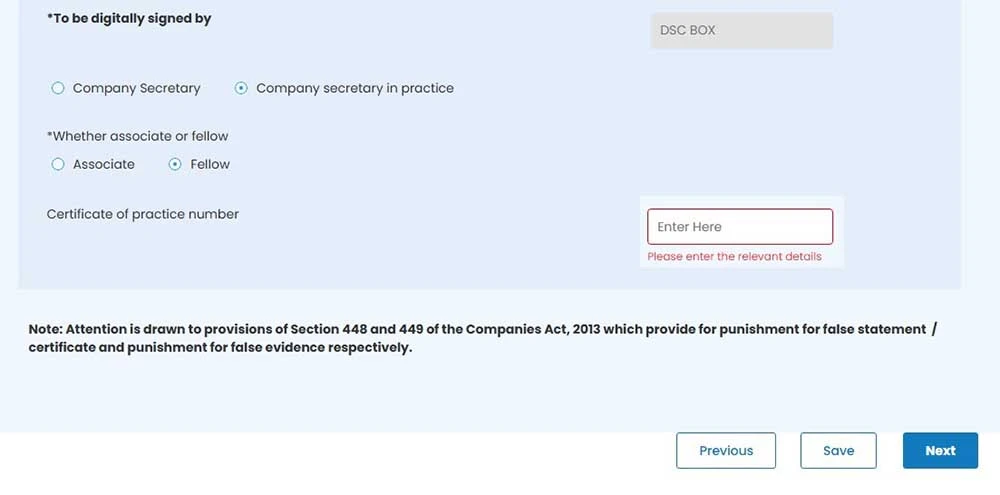
The key attachments include:
- List of shareholders and debenture holders: The prescribed list of members and debenture holders as at the close of the financial year. This is a major attachment required with MGT-7.
- Approval letter for AGM extension: Required where the company has obtained approval to extend the time for holding its AGM.
- MGT-8 certification: Listed companies, and companies meeting the prescribed paid-up capital of ₹10 crore or more or turnover of ₹50 crore or more, must obtain certification of the annual return from a practicing Company Secretary in Form MGT-8 and attach it with the filing.
- Photograph of the registered office (V3 requirement): The V3 versions of AOC-4 and MGT-7/MGT-7A require a photograph showing an external view of the building, with the company name and registered office address visible on the signage.
- Other supporting documents: Additional documents may be attached where required to explain or support specific disclosures in the annual return.
Note: On the MCA V3 portal, the board and director details entered must match MCA records exactly, or the form may be rejected at validation.
Tips for Preparing MGT-7 Attachments
Once you have identified the required attachments, review them carefully before uploading to avoid validation errors and inconsistencies in the filing.
- Use the MCA Excel template: Prepare the shareholder and debenture-holder list using the prescribed Excel template available on the MCA portal. Do not upload an independently created format if the MCA requires its specified template.
- Provide the required shareholder details: Enter mandatory particulars such as PAN and folio numbers, along with the required gender-wise breakup of shareholders.
- Reconcile before filing: Match the shareholder and debenture-holder details with the company’s statutory records to identify discrepancies before submission.
- Meet portal requirements: Check that each attachment meets the file format, size, and other technical specifications stated in the MCA instruction kit.
- Review before submitting: Verify all attachments and disclosures carefully because corrections after filing may require a separate MCA process.
Note: Eligible Small Companies and One Person Companies (OPCs) filing MGT-7A are not required to obtain MGT-8 certification.
What is the Due Date for Filing MGT-7?
MGT-7 must be filed within 60 days of the company’s Annual General Meeting (AGM) under Section 92 of the Companies Act, 2013. The filing deadline therefore depends on the date of the AGM.
- A company generally must hold its AGM within six months from the close of the financial year, but not later than 30 September. The first AGM has a separate nine-month timeline.
- If the AGM is held on 30 September, the MGT-7 filing deadline is 29 November of the same year.
- If the company does not hold its AGM, MGT-7 must still be filed within 60 days from the date on which the AGM should have been held, along with the prescribed reasons for not holding the AGM.
Late filing attracts additional fees and applicable penalties. Companies should therefore track the AGM date and annual return deadline separately to avoid delays.
How to File MGT-7 on the MCA V3 Portal?
MGT-7 is filed electronically through the MCA V3 portal. Before starting, register the authorized signatory as a Business User, associate the required Class 3 DSC, and file AOC-4 for the same financial year. The filing process is:
Step 1: Log in to the MCA V3 portal: Sign in with your registered Business User account. New users must complete V3 registration before filing.
Step 2: Select the form: Open the annual filing section and choose MGT-7 or MGT-7A, depending on the company’s eligibility. The form is available as an online web form.
Step 3: Enter company details: Provide the required information on registration, business activities, share capital, shareholding, directors, KMP, meetings, and other prescribed particulars.
Step 4: Upload attachments: Attach the shareholder and debenture-holder list along with any other applicable documents in the prescribed format.
Step 5: Sign the form: Affix the authorized signatory’s Class 3 DSC and complete the applicable professional certification/verification, where applicable.
Step 6: Submit the form: Submit the completed webform and note the Service Request Number (SRN) generated by MCA.
Step 7: Pay the filing fee: Complete the online payment within the applicable payment window. Save the acknowledgement and challan for your records.
Note: On the MCA V3 portal, MGT-7 and MGT-7A are filled as online webforms; there is no separate form to download, unlike the earlier V2 PDF utility.
What are the Consequences of Non-Filing MGT-7?
Filing the annual return is mandatory for applicable companies under Section 92 of the Companies Act, 2013. Missing the deadline can result in additional fees, penalties, and further compliance consequences.
| Consequence | What it means | Who it affects |
| Daily additional fee | An additional fee of ₹100 per day applies from the day after the due date until the annual return is filed, with no maximum cap. | Company |
| Penalty under Section 92(5) | A penalty of ₹10,000, plus ₹100 per day for continuing default, subject to a maximum of ₹2,00,000 for the company and ₹50,000 for each officer in default. Section 446B provides a reduced penalty for eligible Small Companies and OPCs. | Company and officers in default |
| Compliance impact | Persistent non-filing remains part of the company’s MCA compliance record and may create difficulties in dealings with banks, investors, or authorities. | Company |
| Strike-off and director disqualification | A company that does not carry on business or operations for two consecutive financial years can be liable for strike-off under Section 248. Separately, if a company fails to file its financial statements or annual returns for three consecutive financial years, its directors are disqualified for five years under Section 164(2). | Company and directors |
To avoid these consequences, track the annual return deadline each year and prepare the required information and attachments in advance. Also confirm whether the company should file MGT-7 or MGT-7A under the current eligibility criteria.
Get your MGT-7 filed accurately and on time. RegisterKaro’s compliance experts handle your MCA V3 filing, including shareholder data reconciliation, required attachments, and submission before the deadline.
