


Running a business is not just about making profits; it’s also about staying legally compliant. For a One Person Company (OPC), this responsibility comes in the form of annual compliance requirements that must be fulfilled every year.
Annual compliance for a One Person Company refers to the set of legal and regulatory requirements that an OPC must complete annually, including:
- Filing financial statements
- Filing annual returns
- Maintaining statutory registers
- Completing tax-related obligations
These filings are not just formalities; they act as proof that the company is operating transparently and in accordance with the law.
In this blog, we explain what annual compliance for a One Person Company involves, the penalties for non-compliance, and the key benefits of staying updated with mandatory legal requirements.
Why Annual Compliance Matters for an OPC?
Every business stays strong not only by earning profits but also by following the law. Annual compliance ensures legal safety, credibility, and trust in the market.
For a One Person Company (OPC), formed under the Companies Act, 2013, with just one member, this becomes even more important. While companies enjoy limited liability and legal recognition through OPC registration online, they must also fulfill their annual compliance requirements.
- Avoiding Penalties and Legal Issues: If a company does not meet its annual ROC compliance for OPC, it may face fines and legal actions against the company and its director. For example, missing the deadline to file the annual return (Form MGT-7A) or financial statement (Form AOC-4) attracts a penalty of ₹100 per day until you complete the filing. Timely compliance helps avoid such consequences.
- Mandatory Compliance from Incorporation: OPCs must be aware of and complete all required legal compliance from the time of incorporation. This includes filings, financial statements, and other statutory obligations.
- Demonstrating Transparency and Accountability: Adhering to annual compliance shows investors, shareholders, and stakeholders that the company operates in a transparent and accountable manner.
- Accurate Financial Reporting: Maintaining and submitting precise financial records ensures stakeholders have reliable information about the company’s performance and financial health.
- Building Trust and Protecting Reputation: Fulfilling compliance obligations fosters trust among investors, clients, and partners while safeguarding the company’s reputation in the business community.
- Smooth Functioning of the Company: Staying informed about applicable laws and completing obligations on time ensures the OPC can operate efficiently without disruptions.
What are the Important ROC Compliances for an OPC?
One Person Companies in India must follow several legal and regulatory requirements to operate smoothly and avoid penalties:
| Compliance Name | Compliance Description | Associated Forms | Deadline | Penalty |
| Appointment of First Auditor | Appoint a practicing Chartered Accountant as the first auditor within 30 days of incorporation. | ADT-1 | Within 30 days of incorporation | Not Applicable (for first auditor) |
| Commencement of Business (Form INC-20A) | File a declaration for commencement of business within 180 days of OPC incorporation. | INC-20A | Within 180 days of incorporation | Company: Rs. 50,000/-; Officer: Rs. 1,000/- per day (max Rs. 1,00,000/-) |
| Annual Board Meetings | Conduct at least one board meeting in each half of the calendar year, with a minimum 90-day gap between meetings. | Not Applicable | At least once a year | Company: Rs. 25,000/-; Officer: Rs. 5,000/- |
| Annual Return (Form MGT-7A) | File the annual return with the ROC. Includes details of shareholders and directors. | MGT-7A | Within 60 days from the date the AGM would have been held (late November) | Company: Rs. 10,000/-; Officer: Rs. 50,000/-; Continuing failure: additional Rs. 100/day |
| Appointment of Subsequent Auditor | Appoint a new auditor using Form ADT-1 within 15 days of the first AGM. | ADT-1 | Within 15 days of concluding the first AGM | Company: Rs. 25,000–5,00,000/-; Officer: Rs. 10,000–1,00,000/- |
| Auditor Tenure | The appointed auditor serves until the 6th AGM. | Not Applicable | Not Applicable | Auditor rotation does not apply to OPCs |
| Director KYC (Form DIR-3 KYC) | Directors holding DIN must submit KYC for the financial year by September 30 of the next year. | DIR-3 KYC | By September 30 of the next financial year | Rs. 5,000/- |
| Disclosure of Interest (Form MBP-1) | Directors must declare their interest in other entities at the first board meeting each year. | MBP-1 | First board meeting of the financial year | Director: Rs. 1,00,000/-; Up to 1 year imprisonment for non-compliance |
| E-form DPT-3 (Return of Deposits) | File a return detailing deposits and particulars not considered deposits as of March 31. | DPT-3 | On or before June 30 | Company: Rs. 10,000/-; Officer: Rs. 50,000/-; Continuing violation: Rs. 1,000/day |
| Financial Statements (Form AOC-4) | File audited financial statements electronically with the ROC within 180 days of the financial year-end. | AOC-4 | Within 180 days of the financial year-end | Company: Rs. 10,000/-; Directors: Rs. 10,000/-; Continuing failure: Rs. 100/day (max Rs. 2,00,000/- for company, Rs. 50,000/- for officer) |
| Income Tax Filing | File income tax returns (ITR) annually, reporting income, expenses, and deductions. | Not Applicable | July 31 for individuals; October 31 for audited businesses | Rs. 10,000/- |
| Maintenance of Statutory Registers | Maintain registers as per Section 88, e.g., share transfers, director changes, etc. | Provisions under the Companies Act, 2013 | Ongoing | Non-maintenance may attract liabilities |
| Payment of Stamp Duty on Share Certificates | Pay stamp duty within 30 days of issuing share certificates. | Not Applicable | Within 30 days of issue | Not Specified |
| Statutory Audit | A Chartered Accountant conducts a review of accounts; the report is filed using AOC-4. | AOC-4 | Before filing AOC-4 | Auditor: Rs. 25,000–1,00,000/- |
| TDS, GST, PF, and ESI Compliance | Comply with applicable regulations for TDS, GST, PF, and ESI based on business operations. | Applicable forms | As per the respective laws | Penalties as per the respective regulations |
| Director’s Compliance | Declaration by directors proving non-disqualification under Section 164(2) of the Companies Act | DIR-8 | Beginning of each financial year | Removal of OPC from ROC Register and Penalties |
| MSME Suppliers Payment | Filed for outstanding payments to MSME suppliers pending more than 45 days. | MSME-1 | Half-yearly (by April 30 and October 31) | Penalties of ₹20,000 on OPC and directors |
Which Documents Do You Need for OPC Annual Compliance in India?
Every OPC must keep the following documents ready to complete its annual compliance and maintain clear financial records:
- Purchase and sales receipts: Retain all receipts for the year, as they verify the company’s transactions.
- Expense invoices: Maintain all expense invoices to track outflows and support the audit and tax filings.
- Bank statements: Keep statements for all company accounts from April 1 to March 31 to reconcile accounts and confirm cash flow.
- GST returns: Provide all GST return details with the related sales and purchase invoices if the OPC holds GST registration.
- TDS challans and returns: Submit details of all TDS payments and returns where applicable, which supports tax compliance and credit claims.
- Financial statements: Prepare the balance sheet and profit and loss account, which show the company’s financial health.
- Director’s report: Present the director’s account of the company’s performance, compliance, and operations for the year.
- Member details: Record the sole member’s information, including shareholding.
- Director details: Maintain each director’s details, roles, and activities during the year.
What are the Key Registrations for One Person Companies?
Do you know which registrations your OPC needs after formation? Here are the important ones your company must get to stay compliant.
1. PAN and TAN Registration
Every One Person Company must get a Permanent Account Number (PAN) and a Tax Deduction and Collection Account Number (TAN) from the Income Tax Department. These are necessary for filing taxes and handling financial transactions.
2. GST Registration
If your OPC’s annual turnover crosses the set limit, GST registration is compulsory. You can apply for it through the GST portal, which explains the process step by step.
3. Shop and Establishment Registration
In many states, you may need to register your business under the Shop and Establishment Act. This registration proves that your business premises and work conditions follow the law.
4. Professional Tax Registration
When your OPC hires employees, register for Professional Tax in states where it is required. The rules vary from state to state, so make sure you follow the local guidelines.
5. EPF and ESI Registration
If your OPC has employees, you might also need to register under the Employees’ Provident Fund (EPF) and the Employees’ State Insurance (ESI). These registrations help provide employee benefits and social security.
Which Corporate Stationery Do You Need for OPC Annual Compliance?
After registering a One Person Company (OPC), arrange the necessary stationery items. These not only help in day-to-day operations but also ensure annual compliance for an One Person Company with legal requirements:
- Name Board: Every company, including an OPC, must display its name and the registered office address on a board outside every office or business place.
- Company Rubber Stamp: It is useful to have two rubber stamps – one round stamp with the company’s name and one straight stamp with the company’s name and the designation of the authorized signatory. Use these on documents like board resolutions, bank account forms, cheques, and other legal papers.
- Letterhead: Print the company’s name and registered office address on all letterheads, invoices, notices, and other official papers.
Note: Always display the words “One Person Company” in brackets below an OPC’s name wherever it is printed, displayed, or engraved.
What Records Must an OPC Maintain Regularly?
Part of the OPC compliance requirements, it is necessary to maintain certain statutory registers, a minutes book, and other secretarial records. Update these regularly to stay compliant with legal rules.
The OPC must carefully keep the following records:
- Statutory Registers: These include the Register of Members, Register of Directors, Register of Charges, and any other registers required by law. They must always be accurate and up to date.
- Minutes Book: An OPC has to maintain a minutes book to record the proceedings of board meetings, general meetings, or committee meetings. All resolutions, decisions, and discussions should be written down in order.
- Secretarial Records: The OPC must also keep copies of annual returns, resolutions passed, agreements, contracts, and other important documents. These records should be well-organized and easy to access when needed.
Regular maintenance of these records is very important as it helps an OPC ensure compliance, accountability, and transparency.
What Items Should the Board Include in a One Person Company (OPC) Report?
Prepare the Board’s Report for an OPC using the standalone financial statements and present it in a simplified form. The key points to include are:
- Web Address for Annual Return: Provide the web address where the company publishes its annual return (as per Section 92(3)), if applicable.
- Number of Board Meetings: State the total number of Board meetings held during the year.
- Directors’ Responsibility Statement: Include the Directors’ Responsibility Statement under Section 134(5), confirming that the directors have properly followed financial and operational duties.
- Fraud Reporting Details: Report all fraud cases identified by auditors under Section 143(12), except those required to be reported to the Central Government.
- Explanations on Auditor’s Remarks: Provide the Board’s comments or explanations on any qualifications, reservations, adverse remarks, or disclaimers in the auditor’s report.
- State of the Company’s Affairs: Give an overview of the current condition and performance of the company.
- Financial Summary/Highlights: Include key financial figures or important highlights from the year.
- Material Changes Post Financial Year-End: Mention significant changes in the business or its operations after the financial year-end that could affect the company’s financial position.
- Changes in Directorship: Specify any new appointments or resignations of directors during the year.
- Significant Orders Affecting Future Operations: Highlight any important orders from regulators, courts, or tribunals that may impact the company’s future operations or going concern status.
What are the Key Compliance Requirements for an OPC?
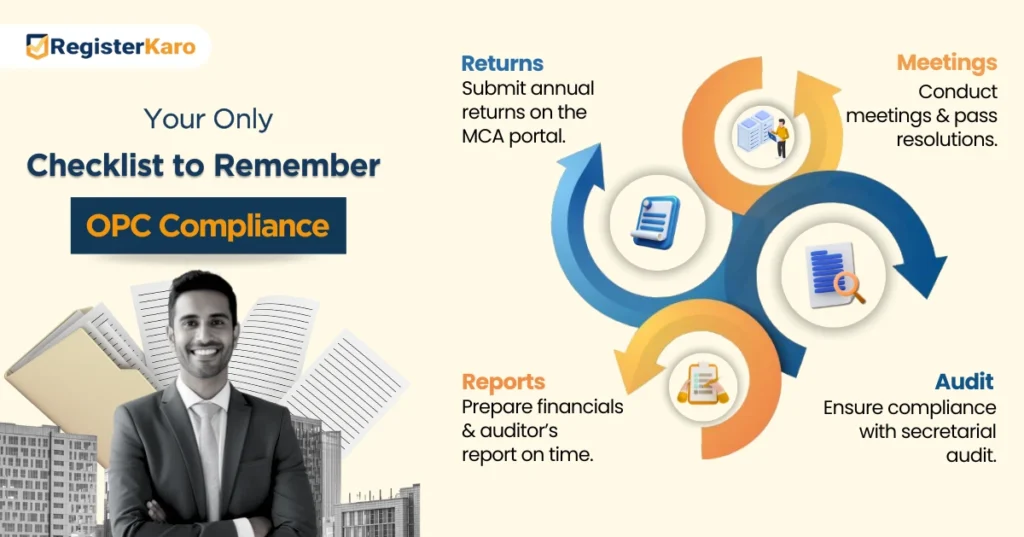
A One Person Company (OPC) must follow certain legal and regulatory obligations every year to stay compliant and operate smoothly. These requirements cover board meetings, audits, financial filings, tax compliance, and statutory record maintenance.
1. Board Meeting Requirements
As per Section 173 of the Companies Act 2013, an OPC must hold at least one Board meeting in each half of a calendar year, with at least 90 days between meetings. If the OPC has only one director, quorum rules do not apply.
Officers who fail to give notice of the Board meeting can be penalized ₹5,000, and the company may be fined ₹25,000.
Note: If there is only one director, the OPC is not required to hold Board meetings.
2. Appointment of Auditor
Under Section 139 of the Companies Act, an OPC must appoint an auditor, usually a Chartered Accountant firm, to audit its accounts and issue an audit report. Auditor rotation rules do not apply to OPCs.
3. Filing of Annual Return
OPCs must file their annual return using Form MGT-7A within 60 days from the date on which the AGM would have been held, which falls in late November for a March year-end. This return records details of the company’s shareholders, members, and directors.
4. Financial Statement Submission
OPCs are required to file financial statements, including the Balance Sheet, Profit & Loss Account, and Director’s Report using Form AOC-4 within 180 days from the financial year-end.
5. Disclosure of Interest by Directors
Directors must declare any interest in other entities annually at the first Board meeting using Form MBP-1. Non-compliance may result in imprisonment of up to one year for directors in default.
6. KYC Compliance for Directors
Directors holding a Director Identification Number (DIN) must submit Form DIR-3-KYC by September 30 of the next financial year.
7. Filing Form DPT-3
Form DPT-3, which reports deposits and particulars not considered as deposits as of March 31, must be filed annually by June 30.
8. Maintaining Statutory Registers
OPCs must maintain registers and update them for events like share transfers, director appointments or resignations, changes in nominee or bank signatories, and auditor changes. Failure to file annual financial statements can lead to a daily penalty of ₹100, up to a maximum of ₹10,00,000.
9. Income Tax Filing
OPCs must file income tax returns annually by July 31 for individuals and September 30 for businesses. Returns should include income, expenses, and deductions. Late filing can result in a penalty of ₹10,000.
10. GST Compliance
OPCs registered under GST must file returns on time. Companies with an annual turnover of up to ₹5 crores file quarterly, while those above ₹5 crores file monthly. OPCs with turnover above ₹2 crores must also file an annual return and get their accounts audited. Timely filing helps avoid penalties and interest charges.
What are the Timelines and Filing Requirements for OPCs?
Missing deadlines can lead to heavy penalties and legal issues. Here’s a simple checklist to help you stay on track:
- Within 60 Days: Complete certain filings within 60 days of incorporation.
- Annually: Every financial year, you need to file annual returns, financial statements, and the auditor’s report.
- As per State Guidelines: Some registrations, like Shop and Establishment, have timelines that depend on the state rules.
Set up reminders or use automated systems to complete your OPC filings on time.
Conclusion
Staying compliant is crucial for a One Person Company (OPC) to operate smoothly, maintain its legal standing, and protect its reputation. Following all annual compliance requirements for OPC not only helps avoid penalties and fines but also builds trust with investors, clients, and stakeholders.
By planning and keeping track of deadlines, OPC owners can focus on growing their business without worrying about legal or regulatory issues.
