
Form MGT-14 is an e-form used by companies to file specified board and shareholder resolutions, along with certain agreements, with the Registrar of Companies (ROC) under Section 117 of the Companies Act, 2013, read with Rule 24 of the Companies (Management and Administration) Rules, 2014. It records significant corporate decisions, including changes to a company’s constitutional documents and other matters that the law requires companies to report to the Ministry of Corporate Affairs (MCA).
Companies must generally file MGT-14 within 30 days of passing a reportable resolution or entering into a reportable agreement. However, certain exemptions apply, including one for eligible private companies from filing specified Board resolutions under Section 179(3). This filing keeps official corporate records up to date and supports regulatory oversight of significant company decisions. Late filing attracts additional fees and may also trigger penalties under Section 117(2) for the company and every officer in default, starting at ₹10,000.
Key Takeaways
- Form MGT-14 is filed with the Registrar of Companies (ROC) under Section 117 of the Companies Act, 2013, to report specified Board and shareholder resolutions and certain agreements. “MGT” stands for “Management.”
- Companies must generally file MGT-14 within 30 days of passing a reportable resolution or entering into a reportable agreement, as required by Section 117(1), subject to applicable exemptions.
- All companies must file applicable special resolutions, while public companies must file applicable Board resolutions under Section 179(3). Private companies, including OPCs, are exempt only from filing Section 179(3) Board resolutions, under the MCA notification dated June 5, 2015, provided they have not defaulted in filing their financial statements or annual returns. They must still file special resolutions.
- Filing fees generally range from ₹200 to ₹600, depending on the company’s nominal share capital. Late filings attract additional fees ranging from 2 to 12 times the normal fee, depending on the delay.
- Late or missed filings can attract penalties under Section 117(2) of ₹10,000 plus ₹100 per day, subject to a maximum of ₹2,00,000 for the company and ₹50,000 for each officer in default.
- A late MGT-14 can be filed at any time by paying the additional fee under Section 403. Late filing does not remove the Section 117(2) penalty.
What is the MGT-14? Meaning & Full Form
Form MGT-14 is a form filed with the Registrar of Companies (ROC) to report specified resolutions and agreements passed at a company’s board or general meetings under the Companies Act, 2013. In the form, “MGT” stands for “Management” and identifies the form as part of the series prescribed under the Companies (Management and Administration) Rules, 2014.
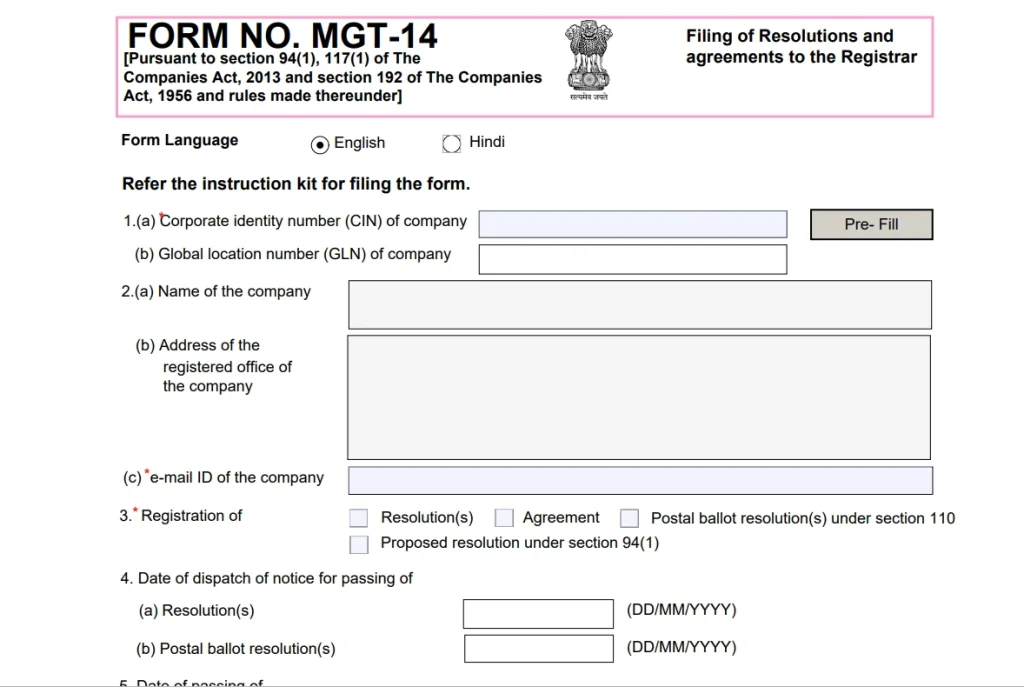
This form records reportable corporate decisions in the MCA records, keeping the regulator informed of significant company resolutions and agreements. This record serves two purposes:
- It gives the MCA oversight of the major decisions a company takes.
- It adds most filed resolutions to the public record. However, board resolutions filed under Section 117(3)(g) are an exception: no person can inspect or obtain copies of them under Section 399.
Why Do Companies Need to File Form MGT-14?
Companies file Form MGT-14 to meet their disclosure obligations under the Companies Act, 2013. The form serves to:
- Notify the ROC of special resolutions passed by members.
- Report board resolutions that require filing under the law.
- Record specified changes to the company’s structure, management, or operations.
- Keep official records of reportable corporate decisions. Most of these records are available for public inspection, except Section 179(3) Board resolutions.
In short, MGT-14 ensures that major company decisions remain traceable and compliant with MCA regulations.
When Do Companies Need to File Form MGT-14? Different Scenarios
Companies must generally file Form MGT-14 within 30 days of passing a resolution or entering into an agreement covered by Section 117(3) of the Companies Act, 2013.
Common scenarios that require an MGT-14 filing include:
- Passing special resolutions in general meetings.
- Board resolutions under Section 179(3) (applicable to public companies; private companies are exempt).
- Entering into agreements specified under Section 117(3).
- Resolutions that alter the company’s structure, such as changes to the MOA or AOA.
- Board resolutions authorizing significant financial decisions, such as borrowing money or investing the company’s funds (for public companies).
- Filing by an Interim Resolution Professional (IRP), Resolution Professional, or liquidator, where applicable. The declaration block in Form MGT-14 changes depending on which of these professionals signs the form.
Which Resolutions and Agreements Require Filing MGT-14?
Section 117(3) of the Companies Act, 2013, specifies the resolutions and agreements that companies must file using Form MGT-14. These fall into three broad categories:
1. Special Resolutions: All Companies [Section 117(3)(a)]
Companies must file special resolutions in MGT-14, whether public or private, subject to applicable exemptions. Under Section 114(2) of the Companies Act, 2013, a resolution qualifies as a special resolution when the votes cast in favor are at least three times the votes cast against. This is commonly described as a 75% majority of the votes cast by members. Special resolutions are member resolutions, passed at a general meeting or by postal ballot.
Companies use special resolutions for significant corporate decisions, including:
- Altering the Memorandum of Association (MOA)
- Altering the Articles of Association (AOA)
- Shifting the registered office from one state to another under Section 13(4), which requires a special resolution altering the MOA and Central Government approval
- Shifting the registered office outside the local limits of a city, town or village under Section 12(5)
- Reducing share capital
- Approving a buy-back of securities, where a special resolution is required
- Approving a private placement of shares or other securities transactions where the Act specifically requires a special resolution
- Approving the sale, lease or disposal of an undertaking under Section 180(1)(a), or borrowing beyond the limits in Section 180(1)(c). These require a special resolution, so they are filed under clause (a).
- Changing the company name, which requires a special resolution and alteration of the MOA/AOA (filed in MGT-14 along with the name-change approval process)
2. Board Resolutions Under Section 179(3): Public Companies Only [Section 117(3)(g)]
Public companies must file Board resolutions passed under Section 179(3). These cover the Board’s exercise of key powers, including resolutions to:
- Make calls on shareholders for unpaid share capital
- Authorize the buy-back of securities
- Issue securities, including debentures
- Borrow money
- Invest the company’s funds
- Grant loans, or provide guarantees or security for loans
- Approve the financial statements and the Board’s report
- Diversify the company’s business
- Approve an amalgamation, merger, or reconstruction
- Make political contributions, appoint or remove key managerial personnel, and appoint internal auditors and the secretarial auditor (matters added by Rule 8 of the Companies (Meetings of Board and its Powers) Rules, 2014)
- Take over or acquire a controlling or substantial stake in another company
Notes:
- Under the MCA exemption notification G.S.R. 464(E) dated June 5, 2015, private companies are exempt from filing Board resolutions under Section 117(3)(g), subject to conditions. Paragraph 2A, inserted by G.S.R. 583(E) dated June 13, 2017, limits this exemption to private companies that have not defaulted in filing their financial statements under Section 137 or their annual returns under Section 92. A private company in either default must file MGT-14 for applicable Board resolutions under Section 179(3).
- Banking companies, and notified classes of NBFCs and housing finance companies, do not need to file Section 179(3)(f) resolutions to grant loans, give guarantees or provide security in the ordinary course of their business.
3. Other Specified Resolutions and Agreements [Section 117(3)]
Companies must also file the following resolutions and agreements, where applicable:
- Clause (b): Resolutions agreed to by all members that would otherwise require a special resolution.
- Clause (c): Board resolutions or agreements relating to the appointment, reappointment, renewal, or variation of the terms of a managing director.
- Clause (d): Resolutions or agreements that bind a particular class of members.
- Clause (f): Resolutions for voluntary liquidation under Section 59 of the Insolvency and Bankruptcy Code, 2016.
- Clause (h): Any other resolution or agreement that may be prescribed and placed in the public domain.
Clause (e), which covered resolutions consenting to the Board’s powers under Section 180(1)(a) and (c), was omitted with effect from 7 May 2018. Such resolutions are now filed as special resolutions under clause (a).
Note: The subject matter alone does not determine whether MGT-14 is required. Identify the specific provision under which the resolution was passed and check whether Section 117 requires filing. Ordinary resolutions generally do not require MGT-14 unless a specific provision mandates it.
Applicability of MGT-14 Form: Public vs Private Companies
Whether a company must file Form MGT-14 depends on the resolution passed and the company’s legal structure. Here’s how the filing requirement applies to each type of company:
| Company Type | MGT-14 Filing Requirements | Section 179(3) board resolutions |
| Public limited companies | File special resolutions, board resolutions under Section 179(3), and the other resolutions or agreements specified in Section 117(3). | Must file. |
| Private limited companies | File special resolutions and the other reportable resolutions or agreements under Section 117(3) after Pvt Ltd Company registration. | Exempt under the MCA notification dated 5 June 2015. |
| One Person Companies (OPCs) | File special resolutions and other reportable items; the sole member’s decisions are recorded under Section 122 and filed where the law requires. | As a type of private company, an OPC benefits from the Section 179(3) filing exemption. |
Important: These exemptions are not fixed. Companies must regularly check updates issued by the Ministry of Corporate Affairs (MCA) to stay compliant.
Due Date for Filing MGT-14
Under Section 117(1) of the Companies Act, 2013, companies must generally file Form MGT-14 with the ROC within 30 days of passing the resolution or entering into the agreement.
Key points to remember:
- Meeting resolutions: The 30-day period starts on the date the resolution is passed at the board or general meeting.
- Resolutions by circulation: The period starts when the resolution is approved by the required majority of directors (for board resolutions, under Section 175).
- Postal ballot and e-voting: The resolution is treated as passed on the last date set for receiving ballots or e-votes, under Secretarial Standard 2.
- IFSC companies: Specified private and public companies in an International Financial Services Center get 60 days instead of 30, under MCA notifications dated January 4, 2017.
- Calendar days: The 30-day deadline includes calendar days, not just working days, and no separate grace period applies. Filing on day 31 counts as late and attracts additional filing fees, with a possible penalty under Section 117(2).
Missing the deadline does not automatically invalidate the resolution, but it can expose the company and its officers to additional fees and statutory penalties.
Filing MGT-14 After the Due Date
Missing the 30-day deadline does not prevent a company from filing Form MGT-14. A company can still submit the form through the MCA portal, but the consequences depend on the applicable filing requirements:
- Late filing: Under Section 403 of the Companies Act, 2013, the company can file MGT-14 after the deadline by paying the applicable additional fee. Condonation is not required simply to submit a delayed filing.
- Condonation of delay: Section 460 separately allows the Central Government to condone certain filing delays through Form CG-1, subject to approval. This is a discretionary remedy, not an automatic extension or substitute for timely filing.
Filing MGT-14 within the prescribed 30-day period remains the best way to avoid additional fees and potential penalties.
Documents Required for Form MGT-14
Filing MGT-14 requires the resolution and its supporting papers. What you attach depends on the resolution being filed:
Mandatory Attachments
- Certified copy of each resolution, with the explanatory statement under Section 102 where one applies
- Altered MOA or AOA, where the resolution changes either
- Copy of the agreement, where the filing relates to an agreement
Additional Documents (Where Applicable)
- Notice of the meeting
- Extract of the minutes where the resolution appears
- Any other document relevant to the specific resolution
Note: Ensure all attachments are clear, certified or self-attested by the authorized signatory, and uploaded in PDF/JPG format to avoid pre-scrutiny errors and processing delays. Each file is limited to 2 MB; the total submission cannot exceed 10 MB, and you can upload up to five optional attachments. Attach the altered MOA and AOA through the linked e-MoA and e-AoA forms.
Details Required for Filing MGT-14 Form
The MGT-14 form captures the company, the meeting, and the resolution in detail. The details required for filing Form MGT-14 are:
| Category | Details captured in the MGT-14 form |
| Company details | Corporate Identification Number (CIN), Global Location Number (GLN), company name, registered office address, and email ID |
| Filing type | Whether the filing is for resolution(s), an agreement, or postal-ballot resolution(s) under Section 110, and the number of resolutions filed |
| Dates | Date of dispatch of the notice and the date the resolution was passed |
| Resolution particulars | The section of the Companies Act, 2013 (and the 1956 Act, if applicable) under which it was passed; the purpose and subject matter of the resolution; the authority that passed it (Board, shareholders, class of members, or creditors); and its type (ordinary, special, or requisite majority) |
| Related form reference | SRN of Form INC-28, where applicable (e.g., a condonation or court/Tribunal order) |
| Attachments | Certified copy of the resolution(s) with the explanatory statement under Section 102, and the altered MOA/AOA where relevant |
How to File MGT-14 Form on MCA (Step-by-Step)
MGT-14 is filed as a web-based form on the MCA V3 portal. Follow these steps to file it:
Step 1: Log in at mca.gov.in, go to MCA Services → e-Filing → Company Forms Download, and select Form MGT-14. Enter the company’s CIN so its details auto-populate, then complete all mandatory fields (see the “Details Required” section above).
Note: On the MCA V3 portal, MGT-14 is filled as an online web form; there is no separate form to download, unlike the earlier V2 utility.
Step 2: Complete the web form and attach the required documents as PDF files. The V3 portal runs its validation checks automatically when you submit the form.
Step 3: Submit the completed web form. The portal validates the details and generates an SRN, after which the application status changes to “Pending for DSC upload.” Affix the Digital Signature Certificate (DSC) belonging to an authorized director or company secretary.
Step 4: Pay the applicable filing fee (₹200–₹600, based on nominal share capital) and the additional fee for delayed filing through the MCA payment gateway. The filing is complete once payment succeeds; save the SRN and retain the challan for your records.
Note: After you submit the form and pay the fee, the MCA system sends an acknowledgment email confirming receipt of your filing. The ROC then processes the form, and you can track its status on the MCA portal using the SRN. If the resolution changes the company’s object clause, the Registrar registers the special resolution and issues a certificate of registration of the special resolution after completing the process, confirming that the alteration has taken effect.
MGT-14 Filing Fees
The MCA form MGT-14 filing fee depends on the company’s nominal share capital:
| nominal share capital | Normal Fee |
| Less than ₹1,00,000 | ₹200 |
| ₹1,00,000 to ₹4,99,999 | ₹300 |
| ₹5,00,000 to ₹24,99,999 | ₹400 |
| ₹25,00,000 to ₹99,99,999 | ₹500 |
| ₹1,00,00,000 or more | ₹600 |
Note: A company without share capital pays a flat ₹200 fee for MGT-14.
Additional Fees for Late Filing of MGT-14
If MGT-14 is filed after the 30-day deadline, additional fees apply as a multiple of the normal fee, based on the length of the delay:
| Period of delay | Additional fee |
| Up to 30 days | 2× normal fee |
| More than 30 and up to 60 days | 4× normal fee |
| More than 60 and up to 90 days | 6× normal fee |
| More than 90 and up to 180 days | 10× normal fee |
| More than 180 days and up to 270 days | 12× normal fee |
Note: These additional fees are separate from, and in addition to, the penalty under Section 117(2). The ₹100 per day additional fee applies to filings under Sections 92 and 137, which is why Forms MGT-7 and AOC-4 use this rate. MGT-14 follows the multiple-based additional fee structure. Government fee slabs may be revised from time to time, so confirm the current fees on the MCA portal before filing.
MGT-14 Penalties for Non-Compliance
Non-filing of Form MGT-14 attracts additional ROC fees and a statutory penalty under Section 117(2) of the Companies Act, 2013. The penalties, as amended by the Companies (Amendment) Act, 2020, are:
| Defaulting Party | Penalty Structure |
| Company | ₹10,000 initial penalty + ₹100 per day for continuing failure (Maximum: ₹2,00,000) |
| Every officer in default (including a liquidator, if any) | ₹10,000 initial penalty + ₹100 per day for continuing failure (Maximum: ₹50,000) |
The penalty calculation begins from the 31st day after the resolution date. Both the company and the responsible officers face separate penalty proceedings.
Notes:
- The daily penalty continues until the default is rectified or otherwise dealt with under the applicable law.
- The company and each officer in default may be penalized separately. The officer’s liability is not an alternative to the company’s penalty.
- The Companies (Amendment) Act, 2019 converted the default under Section 117(2) from a fine-based offence into a civil penalty, and the Companies (Amendment) Act, 2020 reduced the penalty amounts to the current levels.
Common Mistakes to Avoid While Filing MGT-14
Errors in resolution classification, documentation, or filing deadlines can lead to additional fees, penalties, or resubmissions. Avoid these common mistakes while filing Form MGT-14:
- Missing the 30-day deadline: The filing period starts when the resolution is passed. Late filing can attract additional fees and penalties under Section 117(2).
- Misapplying the private-company exemption: Private companies are exempt from filing board resolutions under Section 179(3), but must still file applicable special resolutions and other reportable items.
- Filing MGT-14 for ordinary resolutions: An increase in authorized capital under Section 61 needs form SH-7, not MGT-14, unless the articles are also altered by special resolution.
- Filing the wrong resolutions: Misclassifying ordinary and special resolutions or board and shareholder decisions can result in missed mandatory filings or unnecessary submissions.
- Uploading incomplete attachments: Missing certified resolutions, meeting notices, explanatory statements, or altered MOA/AOA documents, where applicable, can delay processing. Ensure all attachments are legible and properly executed.
- Using an invalid DSC or omitting certification: An expired or unregistered digital signature, or missing professional certification where required, can prevent successful filing.
Review the resolution, filing deadline, company details, and supporting documents before submission to reduce avoidable errors and compliance costs.
Conclusion
Staying compliant with MGT-14 involves spotting which resolutions are reportable, confirming whether an exemption applies, and filing within 30 days. Missing these can lead to additional fees and penalties for both the company and its officers in default.
If you need help managing these requirements, RegisterKaro can identify resolutions that require filing, prepare the necessary documents, and submit Form MGT-14 to the ROC. If a filing deadline has been missed, the team can also assist with an application for condonation of delay under Section 460, where applicable. Contact us for support with your Private Limited Company compliance requirements.
